Research / Earnings and valuation
Welltower Stock Q3 2026:Seniors Housing NOI Up 21% as FFO Guidance Rises
As of: Figures are as of Welltower Inc.'s third-quarter 2026 results and supplement (the quarter ended 30 September 2026, reported 26 October 2026 in a Form 8-K) and its Form 10-Q for that quarter, filed on 27 October 2026. Welltower's fiscal year is the calendar year, so its Q3 2026 covers July to September 2026. The share price used in our valuation is the NYSE close of WELL on 2 November 2026, $239.00; analyst data were accessed on 2 November 2026. Published 2 November 2026.
The short answer. Welltower stock Q3 2026 is a story of fuller senior living communities and a very large buying programme. In the three months to 30 September 2026, total revenues rose 38.4% to $3,715.8m and normalized funds from operations (FFO), the cash earnings measure REITs use, rose 24.6% to $1.67 a diluted share. Same-store net operating income (NOI) from seniors housing operating properties, the communities where Welltower takes the operating profit rather than a fixed rent, rose 21.0% as occupancy climbed 320 basis points and revenue per occupied room rose 5.3%. Welltower raised its 2026 normalized FFO guidance for the third time this year, to $6.47-6.53 a share, and said it had $21.0bn of investments closed or under contract in 2026. Our discounted cash flow model gives $164.18 a share, against a $239.00 close on 2 November 2026; below we show which assumptions drive that gap and how far it moves when you change them.
Key takeaways
- Revenue rose 38%, FFO per share 25%. Total revenues were $3,715.8m, up from $2,685.7m, and normalized FFO was $1,258.5m, or $1.67 a diluted share, up from $1.34. The share count rose 10.1% to 754.9m.
- Seniors housing operating drove the quarter. Same-store NOI in that segment rose 21.0% to $604.3m across 1,052 properties, on organic revenue growth of 9.1%, 320 basis points more occupancy and a 310 basis point wider margin.
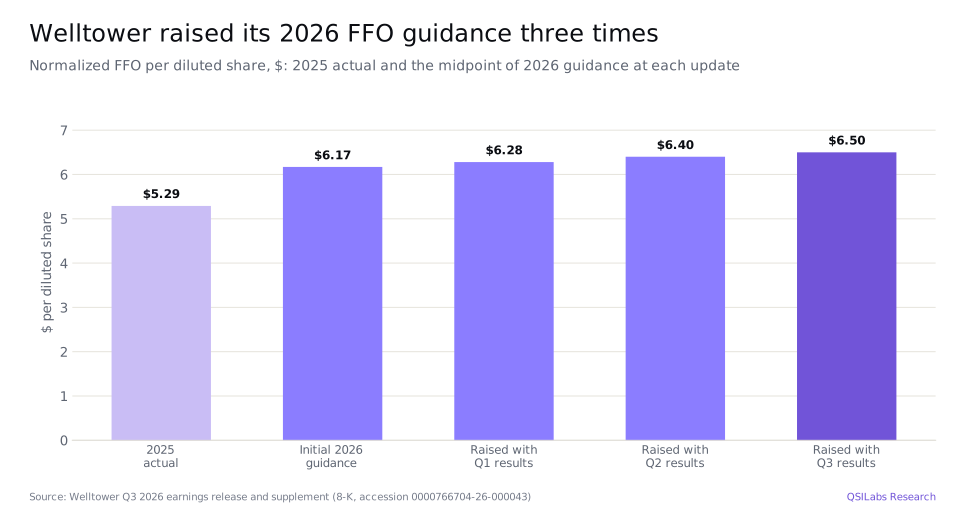
- Guidance rose for the third time. The 2026 normalized FFO midpoint went to $6.50 a share from $6.40, after $6.17 at the start of the year and $6.28 after the first quarter. The midpoint is 22.9% above 2025's $5.29.
- Buying continued at scale. Welltower made $13.3bn of acquisitions and loan fundings in the first nine months at a 6.2% initial yield, sold or was repaid $4.1bn at 7.0%, and had a further $7.7bn closed or under contract after the quarter.
- Leverage rose from a low base. Net debt was $17.26bn, 3.02 times annualized adjusted EBITDA and 9.2% of enterprise value; Welltower funded much of its buying with $7.56bn of new shares sold through its at-the-market programme.
- Our value: $164.18 a share, against a $239.00 close on 2 November 2026. A two-stage cross-check gives $130.88 and a scenario with a single global REIT beta gives $172.58; analysts' average target is $260.68.
- What to watch. Occupancy and pricing in seniors housing into 2027, the returns on the $21bn of 2026 investments, how much more stock Welltower issues, and whether interest rates and the cost of capital stay where they are.
Key numbers from Welltower's Q3 2026 earnings
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total revenues | $3,715.8m | $2,685.7m | +38.4% |
| Resident fees and services | $3,121.1m | $2,061.4m | +51.4% |
| Rental income | $488.6m | $499.5m | -2.2% |
| Net income | $414.8m | $282.2m | +47.0% |
| Diluted earnings per share | $0.54 | $0.41 | +31.7% |
| NAREIT FFO per diluted share | $1.42 | $1.20 | +18.3% |
| Normalized FFO | $1,258.5m | $919.2m | +36.9% |
| Normalized FFO per diluted share | $1.67 | $1.34 | +24.6% |
| Adjusted EBITDA | $1,430.7m | $1,062.8m | +34.6% |
| Seniors housing operating same-store NOI | $604.3m | $499.5m | +21.0% |
| Total same-store NOI | $820.0m | $708.3m | +15.8% |
| Dividend per share | $0.85 | $0.74 | +14.9% |
Source: Welltower Q3 2026 earnings release and supplement (Form 8-K).
Welltower Q3 2026 earnings: what happened
Welltower reported third-quarter results on 26 October 2026. Total revenues rose 38.4% to $3,715.8m from $2,685.7m. Almost all of the growth came from resident fees and services, the revenue from communities Welltower owns and runs through operating partners, which rose 51.4% to $3,121.1m. Rental income from properties leased to operators and health systems fell 2.2% to $488.6m, and interest income was $83.3m. For the first nine months, revenues were $10,612.3m, up 38.6% from $7,657.0m.
Net income rose to $414.8m from $282.2m, and diluted earnings per share rose to $0.54 from $0.41. REITs are usually judged on funds from operations instead, which add back the depreciation of their buildings. NAREIT FFO was $1.42 a diluted share, against $1.20, and normalized FFO, which also excludes one-off items such as transaction costs, was $1.67, against $1.34. Over nine months normalized FFO per share was $4.74, up 23.8% from $3.83.
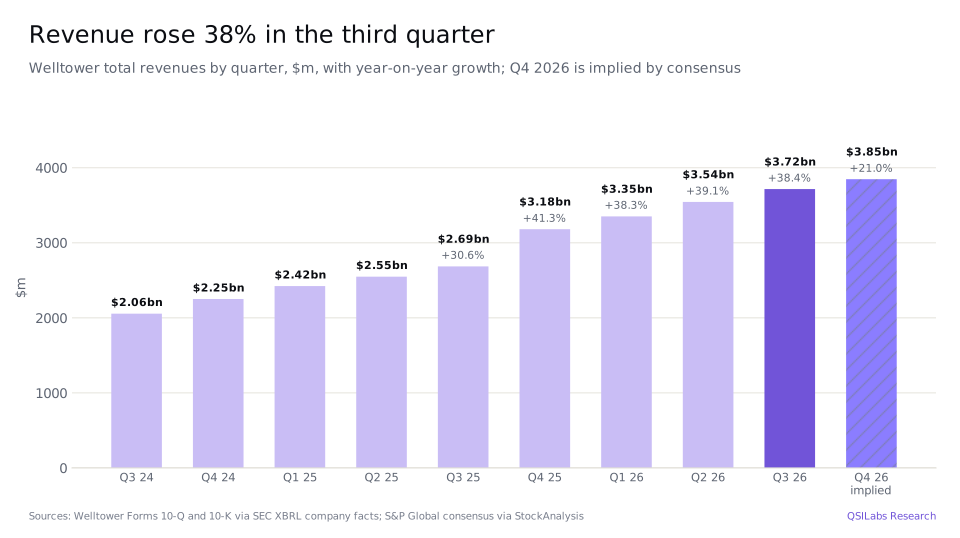
Adjusted EBITDA rose 34.6% to $1,430.7m, a margin of 39%, against 40% a year earlier. Welltower has much more profit than it did a year ago because it owns many more properties: its seniors housing operating portfolio grew from 1,199 properties and 131,792 units at the end of September 2025 to 1,810 properties and 176,652 units a year later. The share count grew too, by 10.1% to 754.9m diluted shares, which is why normalized FFO rose 36.9% in total but 24.6% per share.
On 26 October the board declared a quarterly dividend of $0.85 a share, payable on 19 November to shareholders registered on 10 November, Welltower's 222nd consecutive quarterly cash dividend. It is 14.9% higher than the $0.74 paid a year earlier and is 51% of third-quarter normalized FFO per share.
- 31 Dec 2025WELL closes 2025 at $185.61; 2025 normalized FFO was $5.29 a shareYahoo; 8-K supplement
- Initial guidanceFirst 2026 normalized FFO guidance midpoint of $6.17 a share8-K supplement
- 22 Jan 202652-week closing low of $181.96Yahoo Finance
- Q1 2026 resultsGuidance midpoint raised to $6.288-K supplement
- Q2 2026 resultsGuidance midpoint raised to $6.408-K supplement
- July 2026C$1.15bn of Canadian dollar senior notes issued at a 3.95% weighted coupon8-K supplement
- 24 Jul 202652-week closing high of $252.07Yahoo Finance
- 12 Aug 2026Shares go ex-dividend for a quarterly dividend of $0.85, up from $0.74Yahoo Finance
- 1 Oct 2026C$2.2bn Canadian portfolio of 27 properties closesForm 10-Q
- 26 Oct 2026Q3 results: revenue up 38%, normalized FFO $1.67 a share; guidance midpoint raised to $6.50; WELL closes at $240.618-K; Yahoo
- 27 Oct 2026Conference call; WELL closes at $226.72, down 5.8%8-K; Yahoo
- 2 Nov 2026WELL closes at $239.00, the price used in our valuationYahoo Finance
- 19 Nov 2026$0.85 dividend to be paid, Welltower's 222nd consecutive quarterly cash dividend8-K
Why is seniors housing operating NOI growing so fast?
Because Welltower carries the operating results of these communities. In its seniors housing operating segment, Welltower owns the buildings and pays an operator a management fee, so it keeps the profit after costs. When more rooms fill and rents rise faster than wages and other costs, most of the extra revenue drops through to NOI. That is different from a triple-net lease, where the tenant pays a fixed, slowly rising rent and keeps the operating upside.
In the third quarter, same-store seniors housing operating revenue rose 9.1%. Average occupancy in those 1,052 properties was 90.2%, against 87.0% a year earlier, and revenue per occupied room (RevPOR) rose 5.3% to $6,066 a month from $5,759. The NOI margin widened by 310 basis points, and same-store NOI rose 21.0% to $604.3m from $499.5m.
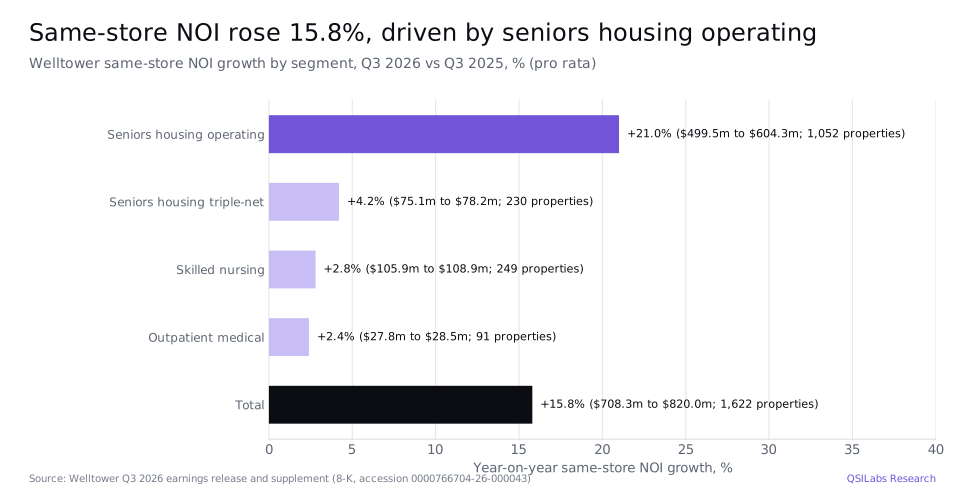
The leased segments grew much more slowly: same-store NOI rose 4.2% in seniors housing triple-net, 2.8% in skilled nursing and 2.4% in outpatient medical, the segment Welltower has been selling. Across all 1,622 same-store properties NOI rose 15.8% to $820.0m.
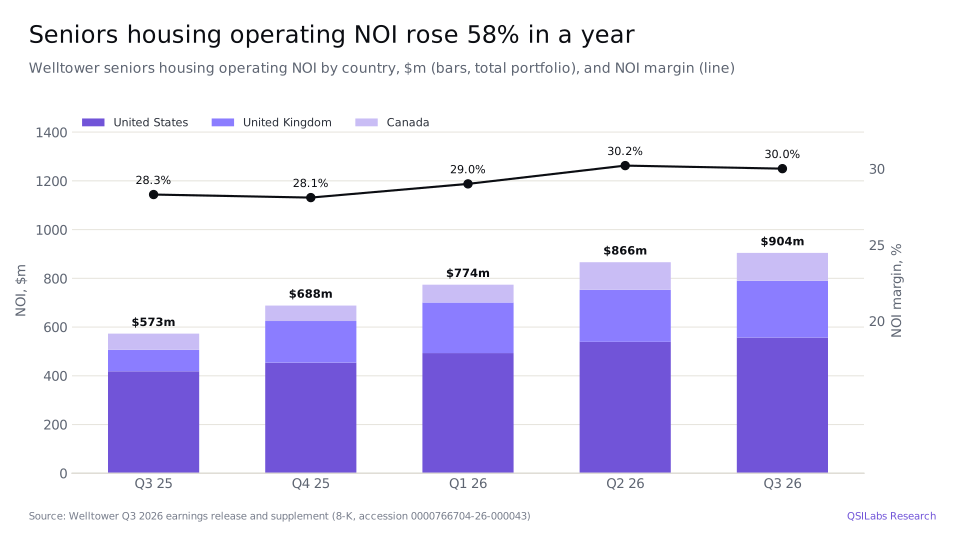
Across the whole seniors housing operating portfolio, including properties bought in the past year, NOI rose 57.8% to $904.3m and the margin was 30.0%, against 28.3%. The United States produced $557.0m, the United Kingdom $233.0m and Canada $114.3m. UK NOI has risen from $88.1m a year ago as the UK portfolio grew from 9,445 units to 36,257, and Canadian NOI rose after Welltower added about 5,700 units in the second quarter.
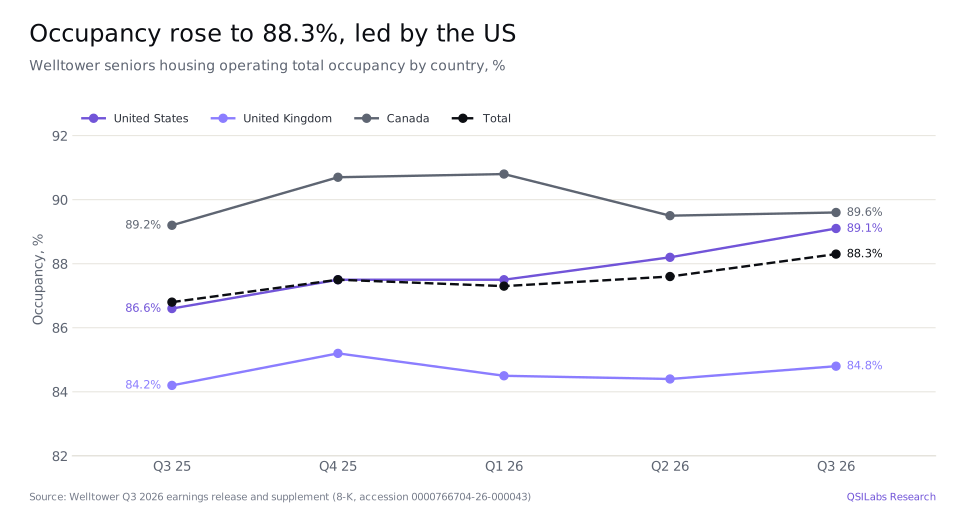
Total occupancy across the operating portfolio rose to 88.3% from 86.8%. The US led with 89.1%, up from 86.6%; Canada was 89.6% and the UK 84.8%. These are total-portfolio figures, so they include newly bought communities, some of which are still filling up.
Seniors housing operating properties now produce 70.0% of Welltower's annualized in-place NOI of $5.08bn. Skilled nursing produces 15.8%, seniors housing triple-net 11.9% and outpatient medical 2.3%. By country, 67.1% comes from the US, 24.0% from the UK and 8.9% from Canada. The largest operating partners are Barchester, with 10.2% of in-place NOI, Cogir with 8.2% and Avir with 7.3%.
How much is Welltower investing, and how is it paying?
Welltower made $13.3bn of pro rata acquisitions and loan fundings in the first nine months of 2026 at an average initial yield of 6.2%, including $3.9bn in the third quarter at 5.3%, spread over more than 30 transactions with a median size of $38m. Including development funding, gross investments were $13.7bn at 6.3%. Against that it sold properties or was repaid loans totalling $4.1bn at a 7.0% yield, including $2.1bn of outpatient medical buildings and $1.2bn of loan repayments, and it expects about $1.9bn more of dispositions over the next 12 months.
After the quarter, Welltower said it had a further $7.7bn closed or under contract, taking 2026 to $21.0bn. The 10-Q describes two of the larger deals: a C$2.2bn portfolio of 27 Canadian properties that closed on 1 October, with C$639m of secured debt assumed, and a 62-property US portfolio of about $2.6bn, to be leased under a triple-net master lease and paid for with cash and new operating partnership units, which Welltower expects to close in the fourth quarter.
Most of the money has come from new equity. In the first nine months Welltower sold 34.6m shares through its at-the-market programme at an average of $218.07, raising $7.56bn, and it sold another 1.6m shares in October; $4.86bn of capacity remains. In July it issued C$1.15bn of Canadian dollar senior notes, C$750m at 3.85% due 2031 and C$400m at 4.15% due 2033. Welltower said it had about $9.5bn of available liquidity.
Total debt was $19.67bn at 30 September 2026, against cash and restricted cash of $2.42bn, giving net debt of $17.26bn. That is 3.02 times annualized adjusted EBITDA, against 2.36 times a year earlier, when Welltower held $6.94bn of cash, and 9.2% of enterprise value. Its credit ratings are A- and A3.
What did Welltower change in its 2026 guidance?
Welltower raised its 2026 normalized FFO guidance to $6.47-6.53 a share from $6.36-6.44, and its net income guidance to $3.31-3.37 a diluted share. The $6.50 midpoint is 22.9% above 2025's $5.29. Welltower's bridge attributes $0.67 of the increase from 2025 to seniors housing operating NOI, $0.505 to investment and financing activity, $0.02 to outpatient medical and triple-net, $0.035 to income taxes and other items, and minus $0.02 to general and administrative costs.
For seniors housing operating, Welltower now expects same-store NOI growth of 20.25% to 21.75%, 21.0% at the midpoint and 100 basis points higher than before, from revenue growth of 9.3%, a 350 basis point rise in occupancy, RevPOR growth of 5.1% and expense growth of 4.6%. Total same-store NOI is expected to grow 15.0% to 16.25%. General and administrative costs are guided at $267m to $272m.
The guidance includes only investments, dispositions and capital transactions already announced. The 2027 numbers will depend on how fast the $21bn of 2026 investments add NOI and how many new shares Welltower issues to pay for more.
Welltower stock performance in 2026
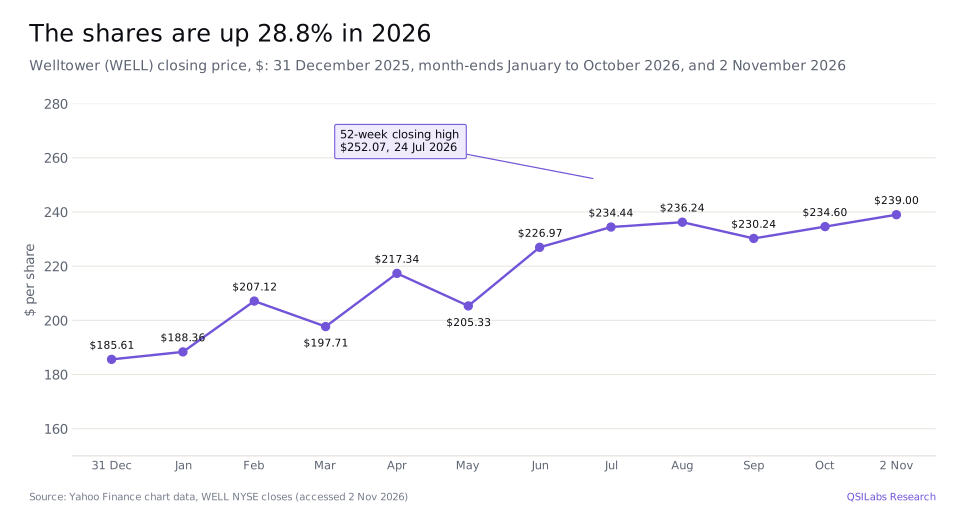
Welltower closed at $239.00 on 2 November 2026, up 1.9% on the day and 28.8% from $185.61 at the end of 2025. The shares hit a 52-week closing low of $181.96 on 22 January and a closing high of $252.07 on 24 July. They closed at $240.61 on 26 October, the day the results were released, and at $226.72 the next day, down 5.8%, before recovering.
At $239.00 the shares trade at 36.8 times the $6.50 midpoint of 2026 normalized FFO guidance, and the $3.40 annual dividend gives a yield of 1.4%. Counting operating partnership and exchangeable units and the dilutive effect of exchangeable notes, there are 752.2m shares, which puts the equity value at about $179.8bn.
Welltower stock Q3 2026: is WELL overvalued?
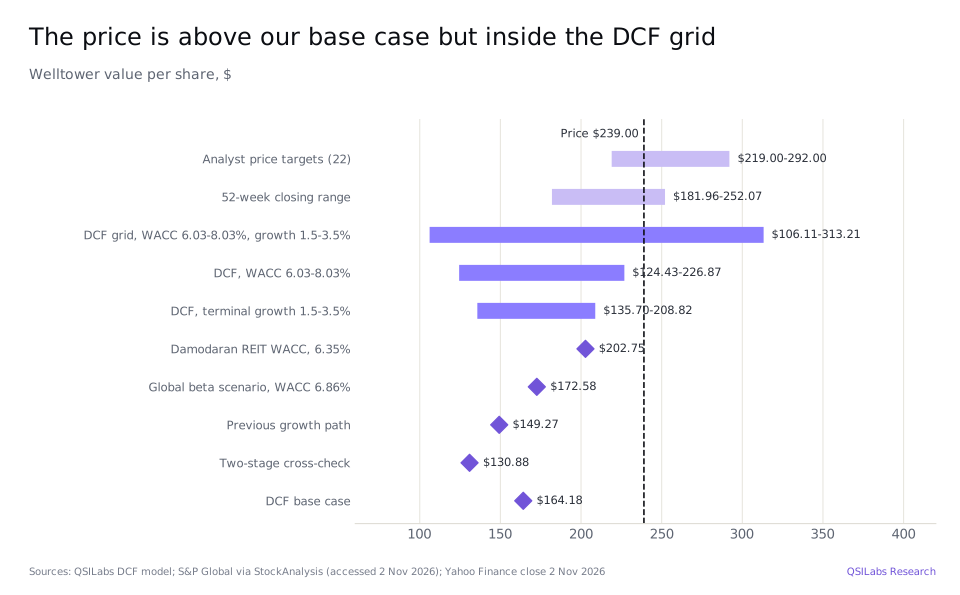
On our numbers, the shares trade above the value of their cash flows. Our discounted cash flow model gives $164.18 a share, 31% below the $239.00 close on 2 November 2026. The 22 analysts tracked by S&P Global see it differently: their consensus rating is Buy, with an average price target of $260.68, a median of $260 and a range from $219 to $292. In November, 13 rated it a Strong Buy, 6 a Buy and 3 a Hold.
Method
We value Welltower on its operating cash flow before financing. For each year to 2035 we forecast revenue excluding straight-line rent, and an operating profit equal to normalized FFO less straight-line rent and recurring capital spending, plus interest expense. We apply no tax: Welltower is a REIT and its income tax line has been close to nil, an expense of $2.7m in 2024 and net benefits of $7.1m in 2025 and $43.2m in the first nine months of 2026. We deduct acquisitions, net of dispositions, as capital spending and add the NOI they bring at the yield Welltower discloses. We discount the result at a 7.03% cost of capital and assume growth of 2.5% a year after 2035.
For 2026, revenue excluding straight-line rent is $10,368.6m for the first nine months and $3,749.4m for the fourth quarter, which is consensus revenue of $14.46bn less reported nine-month revenue and $98.3m of straight-line rent: $14,118m in all. Operating profit on our definition is $3,520.8m for nine months and $1,288.7m for the fourth quarter, implied by the midpoint of the raised normalized FFO guidance, so the 2026 margin is 34.07%, which we hold after that. Net investment in 2026 is $16.9bn: $9.6bn in the first nine months after dispositions and the $7.7bn closed or under contract after the quarter.
For 2027 revenue growth is 16.9%, in line with consensus revenue of $16.90bn, and for 2028 11.7%, in line with S&P Global's forecast of 20.31% annual revenue growth over three years from 2025. Those paths imply acquisitions of $6.76bn in 2027 and $3.69bn in 2028 at the 6.2% yield Welltower achieved in 2026; we then cut acquisitions to 80%, 60%, 40% and 20% of the 2028 level from 2029 to 2032 and to nil after that. Growth from existing properties is 5.92% a year from 2027 to 2031, Mordor Intelligence's forecast for the US senior living market, 4.47% in 2032 and 2033, Grand View Research's forecast to 2033, and then fades to 2.5% by 2035. Total revenue growth slows from 9.2% in 2029 to 7.5% in 2031, 4.7% in 2033 and 2.5% in 2035.
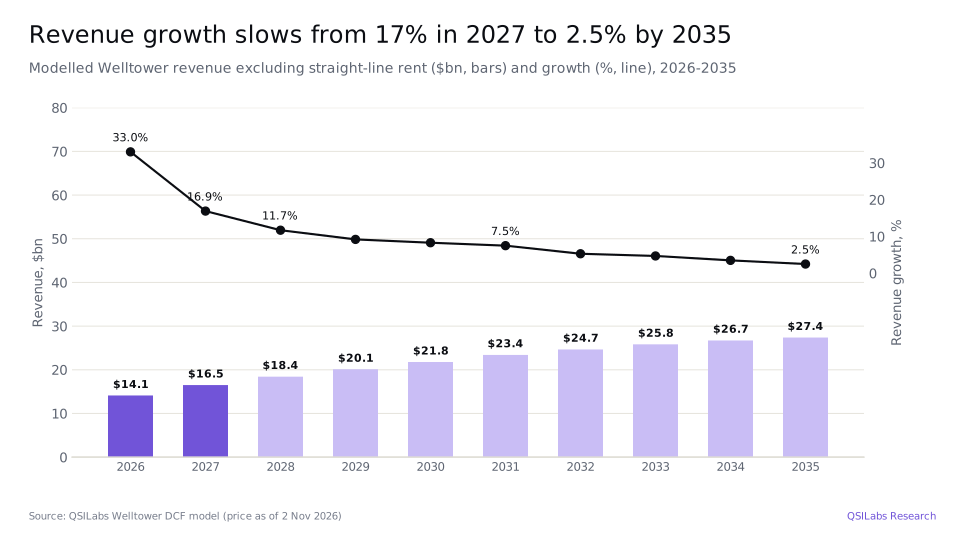
Free cash flow is negative in 2026, at minus $12.1bn for the full year, and in 2027, at minus $1.1bn, because acquisitions exceed operating profit; it turns positive in 2028, at $2.6bn, and reaches $9.3bn by 2035. Only the part of 2026 after 2 November is discounted. At a 6.2% initial yield growing 2.5% a year, an acquisition earns an unlevered return of about 8.7%, above our 7.03% cost of capital, so on our assumptions each $1 invested adds about $0.37 of value.
The 7.03% cost of capital uses Damodaran's January 2026 data for US REITs, which we use because 60.9% of Welltower's revenue comes from the US: a cost of equity of 7.98%, from a 5.12% risk-free rate, a beta of 0.64 and a US equity risk premium of 4.46%, weighted at 54.2%, and a pre-tax cost of debt of 5.90% with no tax shield, because Welltower pays almost no income tax, weighted at 45.8%. That debt weight is the industry average; Welltower's own debt is only about 10% of its capital at market value. The terminal value is 77.8% of our enterprise value of $145.81bn.
From enterprise value we add cash and restricted cash of $2.42bn and deduct debt of $20.16bn, which is Welltower's total debt of $19.67bn, including commercial paper, senior unsecured and secured debt and finance leases, plus its $0.49bn share of joint-venture debt. We also deduct $4.57bn for the cash Welltower has spent or committed since 30 September that our 2026 cash flow does not yet carry, mainly the $7.7bn of fourth-quarter investments, net of about one month of operating cash flow. That gives equity value of $123.49bn, or $164.18 a share on 752.2m shares, which include operating partnership and exchangeable units. We leave the October share sales out, together with their proceeds.
Our previous model, dated 26 October and priced at $240.61, gave $146.38. It assumed a 7.5% yield on new investments, fewer fourth-quarter investments and 782.7m shares, a count that included some units twice. Run on today's price, share count and balance sheet, that path gives $149.27; replacing it with the consensus, company and industry path above adds about $14.91 a share.
How the number moves if you argue with us
The table shows our value per share at different costs of capital and terminal growth rates. The $239.00 price sits inside the grid: it needs a cost of capital of about 6.0% to 6.5% with terminal growth of 2.5% to 3.0%.
| Cost of capital | Growth 1.5% | Growth 2.0% | Growth 2.5% | Growth 3.0% | Growth 3.5% |
|---|---|---|---|---|---|
| 6.03% | $178.68 | $199.79 | $226.87 | $262.91 | $313.21 |
| 6.53% | $155.01 | $171.28 | $191.59 | $217.66 | $252.34 |
| 7.03% | $135.70 | $148.52 | $164.18 | $183.73 | $208.82 |
| 7.53% | $119.65 | $129.95 | $142.30 | $157.37 | $176.19 |
| 8.03% | $106.11 | $114.51 | $124.43 | $136.32 | $150.83 |
The cost of capital is the biggest question. Our base case uses the US REIT industry's 45.8% debt weight, far above Welltower's own 10%. A scenario with a single global REIT beta, unlevered and relevered at Welltower's own ratio of debt to equity, and an equity risk premium of 4.70% weighted by where Welltower earns its revenue (60.9% in the US, 31.7% in Europe and 7.4% in Canada), gives a cost of capital of 6.86% and a value of $172.58 a share. Damodaran's published US REIT cost of capital of 6.35%, which includes a tax shield on debt that Welltower does not really get, gives $202.75. A two-stage version of the model, which fades returns on new investment over a further ten years, gives $130.88.
Our numbers and the market's can both be right only if Welltower keeps growing faster for longer than our forecast, keeps investing at yields well above its cost of capital beyond 2032, widens its margins further, or is valued at a cost of capital near 6%. The 21% NOI growth in seniors housing operating shows the first is possible; we think the price already assumes a good deal of it.
Risks to the Welltower investment case
- Operating exposure. Seventy per cent of in-place NOI comes from seniors housing operating properties, where Welltower bears the operating costs. Slower occupancy gains, weaker pricing or faster wage growth would hit NOI directly; guidance assumes expense growth of only 4.6% in 2026.
- Acquisition returns. Welltower bought $13.3bn of properties and loans in nine months and has $7.7bn more closed or under contract. Integrating that much, and earning more than the 6.2% average initial yield, is not certain, and the third-quarter yield was 5.3%.
- Dilution. The diluted share count rose 10.1% in a year, and Welltower sold $7.56bn of stock in nine months. If the share price fell, funding growth with equity would become less attractive.
- Interest rates and funding. Net debt rose to 3.02 times adjusted EBITDA from 2.36 times. Higher rates would raise borrowing costs and could lower the value investors put on REIT cash flows.
- Concentration in operators and countries. Barchester, Cogir and Avir together produce about a quarter of in-place NOI, and 24.0% of NOI comes from the UK, which adds currency and regulatory risk.
- Valuation risk. At $239.00 the shares trade at 36.8 times guided 2026 normalized FFO and 45.6% above our base case. Slower growth or a higher cost of capital would widen the gap.
FAQ
What value does QSILabs put on Welltower stock?
Our discounted cash flow model gives $164.18 a share, against a $239.00 close on 2 November 2026. Across costs of capital from 6.03% to 8.03% and terminal growth from 1.5% to 3.5% the value ranges from $106.11 to $313.21. A two-stage cross-check gives $130.88 and a scenario with a single global REIT beta $172.58.
Should I buy Welltower stock after the Q3 2026 results?
We do not give personal advice. The third quarter showed 21% same-store NOI growth in seniors housing operating, a third guidance increase and continued heavy investment. On our numbers the shares trade above the value of their cash flows unless growth lasts longer or the cost of capital is lower than we assume, so read the risks above before deciding.
How much revenue did Welltower make in its latest quarter?
Welltower reported total revenues of $3,715.8m for the third quarter of 2026, the three months to 30 September, up 38.4% from $2,685.7m. Resident fees and services were $3,121.1m and rental income $488.6m. Net income was $414.8m, or $0.54 a diluted share.
What is normalized FFO, and how much did Welltower earn on that basis?
Funds from operations add property depreciation and gains or losses on property sales back to net income; normalized FFO also removes one-off items such as transaction costs. Welltower's normalized FFO was $1,258.5m, or $1.67 a diluted share, in the third quarter of 2026, up from $1.34 a year earlier.
How full are Welltower's senior living communities?
Same-store occupancy in its seniors housing operating portfolio was 90.2% in the third quarter of 2026, up from 87.0% a year earlier. Across the whole operating portfolio, including recent purchases, occupancy was 88.3%: 89.1% in the US, 89.6% in Canada and 84.8% in the UK.
What dividend does Welltower pay?
Welltower pays a quarterly dividend of $0.85 a share, up from $0.74 a year earlier, or $3.40 a year. At the $239.00 close on 2 November 2026 that is a yield of 1.4%. The next payment, on 19 November 2026, will be its 222nd consecutive quarterly cash dividend.
What price target do analysts have for WELL?
The 22 analysts tracked by S&P Global have an average target of $260.68, about 9% above the $239.00 close on 2 November 2026, with a median of $260, a low of $219 and a high of $292. Their consensus rating is Buy.
How much debt does Welltower have?
Total debt was $19.67bn at 30 September 2026, against cash and restricted cash of $2.42bn, so net debt was $17.26bn, or 3.02 times annualized adjusted EBITDA. Net debt was 9.2% of enterprise value and Welltower is rated A- and A3.
How did Welltower shares react to the results?
Welltower released its results on 26 October 2026, when the shares closed at $240.61. They fell 5.8% to $226.72 the next day, the day of the conference call, and then recovered to $239.00 by 2 November 2026.
Sources
- Welltower Inc., third-quarter 2026 earnings release and supplement (Form 8-K, 26 Oct 2026; accession 0000766704-26-000043) www.sec.gov
- Welltower Inc., Form 10-Q for the quarter ended 30 Sep 2026 (filed 27 Oct 2026; accession 0000766704-26-000046) www.sec.gov
- SEC XBRL company facts for Welltower Inc. (CIK 766704): quarterly and annual revenues and income taxes from Forms 10-Q and 10-K data.sec.gov
- StockAnalysis: Welltower forecast and analyst ratings, S&P Global data (last updated 2 Nov 2026; accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: Welltower statistics (accessed 2 Nov 2026) stockanalysis.com
- Mordor Intelligence, United States Senior Living Market report (accessed 2 Nov 2026) www.mordorintelligence.com
- Grand View Research, U.S. Senior Living Market report (accessed 2 Nov 2026) www.grandviewresearch.com
- Yahoo Finance chart data: WELL closing prices and dividends (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry (US and global), January 2026 pages.stern.nyu.edu
- QSILabs Welltower discounted cash flow model (internal; price as of 2 Nov 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: UnitedHealth stock Q3 2026: medical costs and Optum, Abbott stock Q3 2026: nutrition spin-off and Libre, Home Depot stock Q3 2026: Pro, SRS and housing and Verizon stock Q3 2026.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.