Research / Earnings and valuation
UnitedHealth Stock Q3 2026:Medical Care Ratio Falls to 88.4% as Profit Rebounds
As of: Figures are as of UnitedHealth Group's third-quarter 2026 results (the quarter ended 30 September 2026, reported 13 October 2026 in a Form 8-K) and its Form 10-Q for the quarter ended 30 June 2026. UnitedHealth's fiscal year is the calendar year, so Q3 2026 is the July-September 2026 quarter. The Q3 2026 Form 10-Q had not been filed when we checked EDGAR on 2 November 2026. The share price is the NYSE close of UNH on 30 October 2026, $406.97. Published 2 November 2026.
The short answer. UnitedHealth stock Q3 2026 rests on a quarter of recovering profit rather than growth. In the three months to 30 September 2026, UnitedHealth Group's revenue was flat at $112.7bn, but its medical care ratio fell to 88.4% from 89.9%, earnings from operations rose 52% to $6.6bn and adjusted earnings per share rose to $4.69 from $2.92. The company raised its full-year 2026 outlook to at least $19.50 of GAAP EPS and at least $20.50 of adjusted EPS. It also served 1.8m fewer medical members than a year earlier as it priced for margin. Our discounted cash flow model values UnitedHealth at $380.02 a share, against a $406.97 close on 30 October 2026. The shares price in a fuller margin recovery than we assume.
Key takeaways
- Revenue flat, profit up. Q3 2026 revenue was $112,694m, down 0.4% from $113,161m. Earnings from operations rose to $6,563m from $4,315m, and net earnings attributable to shareholders rose 75% to $4,110m.
- Medical care ratio of 88.4%. Medical costs took 88.4% of premiums, down from 89.9% a year earlier. The quarter included $610m of favourable reserve development for earlier 2026 dates of service; without it, the ratio would have been about 89.1%.
- Both halves of the group earned more. UnitedHealthcare's operating margin rose to 3.3% from 2.1%. Optum's rose to 5.6% from 3.6%, led by Optum Health, whose earnings from operations rose to $735m from $41m.
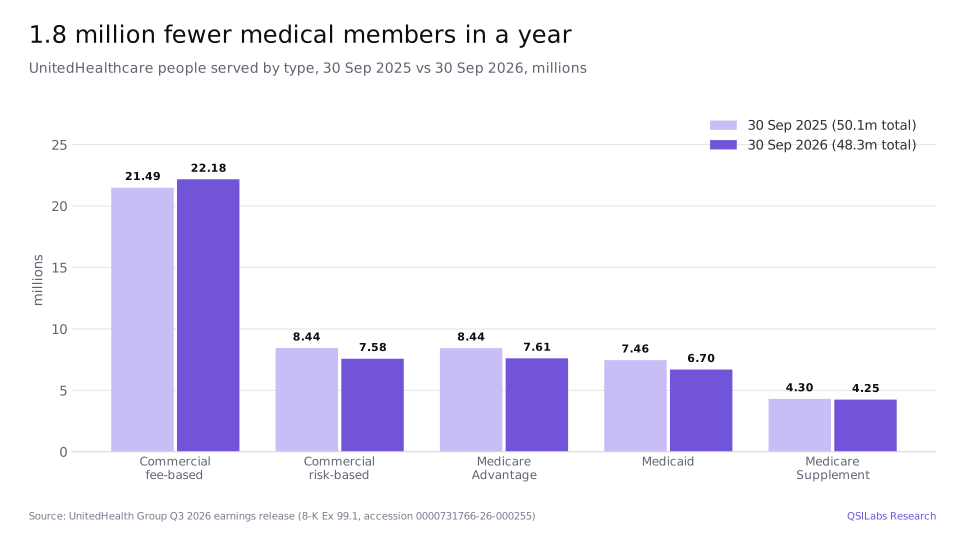
- Fewer members. UnitedHealthcare served 48.3m medical members at 30 September, down from 50.1m a year earlier. Medicare Advantage fell to 7.6m from 8.4m and Medicaid to 6.7m from 7.5m.
- Guidance raised. UnitedHealth now expects 2026 adjusted EPS of at least $20.50 and GAAP EPS of at least $19.50. After $18.30 of adjusted EPS in the first nine months, that implies at least $2.20 in Q4.
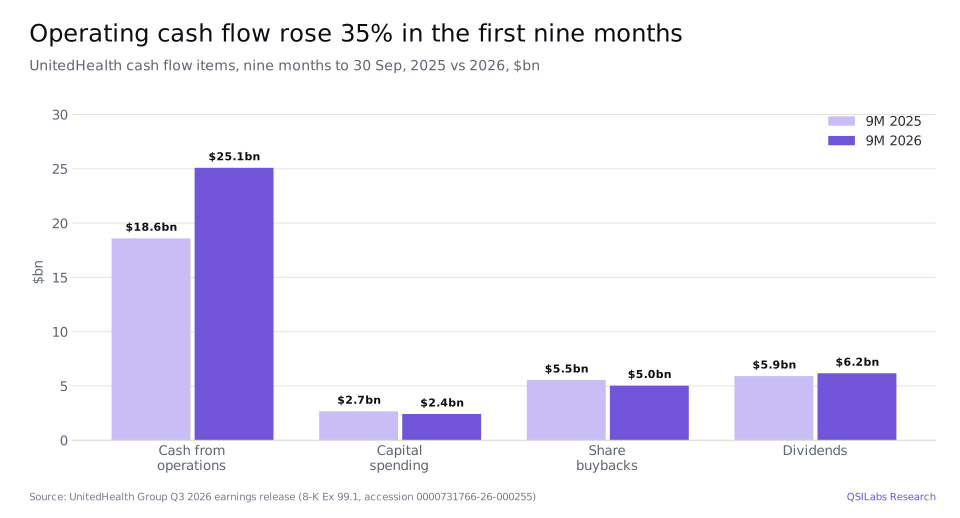
- Cash and returns. Operating cash flow was $25.1bn in the first nine months, up 35%. UnitedHealth paid $6.2bn of dividends and bought back $5.0bn of stock.
- Our value: $380.02 a share, about 7% below the $406.97 close on 30 October 2026. A two-stage cross-check gives $374.73. The average of 26 analyst targets is $476.64.
- What to watch. Q4 2026 results and the 2027 outlook, which will show how much of the 2026 margin repair carries into 2027 premium rates, membership and the Medicare Advantage medical care ratio.
Key numbers from UnitedHealth's Q3 2026 earnings
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $112,694m | $113,161m | -0.4% |
| Premium revenue | $87,078m | $88,979m | -2.1% |
| Medical costs | $76,982m | $79,958m | -3.7% |
| Medical care ratio | 88.4% | 89.9% | -1.5 pts |
| Operating cost ratio | 12.8% | 13.5% | -0.7 pts |
| Earnings from operations | $6,563m | $4,315m | +52% |
| Net margin | 3.6% | 2.1% | +1.5 pts |
| Diluted EPS | $4.56 | $2.59 | +76% |
| Adjusted EPS | $4.69 | $2.92 | +61% |
| Medical members (30 Sep) | 48.3m | 50.1m | -3.6% |
| Days claims payable | 47.0 | 46.2 | +0.8 days |
UnitedHealth Q3 2026 earnings: what happened
UnitedHealth Group reported its third-quarter 2026 results on 13 October 2026. Revenue was $112.7bn, against $113.2bn a year earlier and $112.0bn in the second quarter. Premiums, the money employers, individuals and governments pay UnitedHealthcare to insure people, were $87,078m, 2.1% lower than a year earlier because the insurer covers fewer people. Products revenue, mostly drugs dispensed by Optum Rx, was $14,293m; services revenue was $10,246m; and investment and other income was $1,077m.
The change was in profit. Earnings from operations were $6,563m, up from $4,315m, giving an operating margin of 5.8%, against 3.8% a year earlier. Net earnings attributable to common shareholders were $4,110m, or $4.56 a diluted share, against $2,348m, or $2.59. Adjusted EPS, which adds back $373m of intangible amortisation and removes some portfolio and restructuring items, was $4.69, against $2.92.
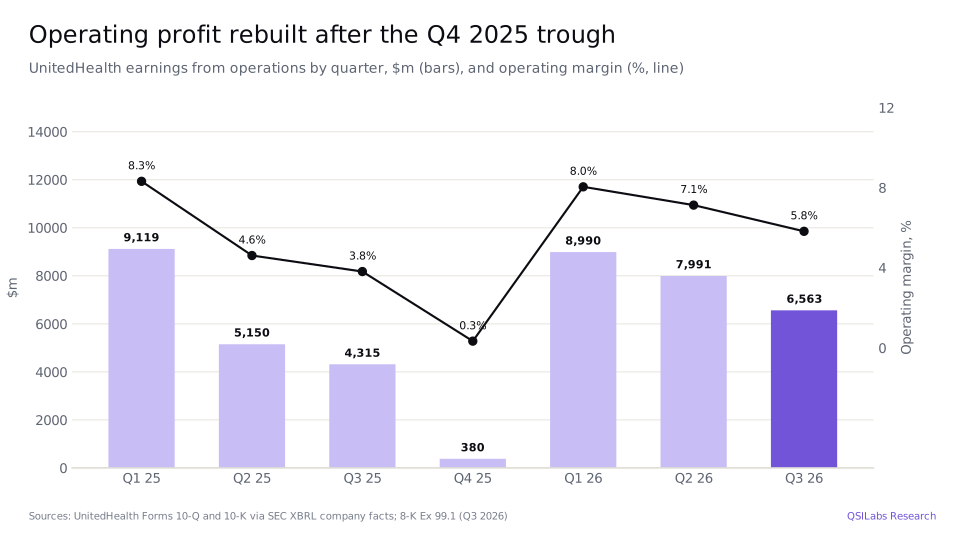
Chief executive Stephen Hemsley said the results "reflect the discipline and execution our teams are bringing to every part of our business". The release attributes the improvement to medical cost management, benefit design changes and pricing discipline, together with lower operating costs. The operating cost ratio, which measures administrative costs as a share of revenue, fell to 12.8% from 13.5%.
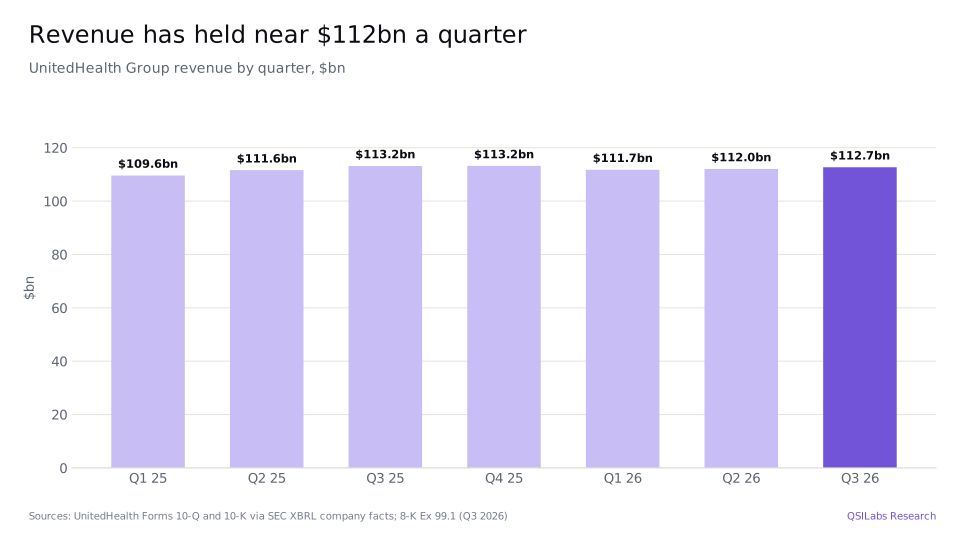
For the first nine months of 2026, revenue was $336,447m, up 0.6% from $334,352m, and earnings from operations were $23,544m, up 27% from $18,584m. Diluted EPS for the nine months was $17.50, against $13.21, and adjusted EPS was $18.30, against $14.22.
- 30 Jun 2026Q2 2026 ends: medical care ratio 86.7%, earnings from operations $7,991m; $1.1bn of cash available for general corporate useForm 10-Q
- 21 Jul 2026UNH closes at $436.35, its highest close of the past yearYahoo Finance
- 30 Sep 2026Q3 2026 ends: 48.3m medical members, debt-to-capital 41.7%8-K Ex 99.1
- 13 Oct 2026Q3 results: MCR 88.4%, adjusted EPS $4.69; 2026 adjusted EPS outlook raised to at least $20.50. UNH closes at $377.768-K Ex 99.1; Yahoo Finance
- 14 Oct 2026UNH closes at $395.62, up 4.7% on the day after the resultsYahoo Finance
- 30 Oct 2026UNH closes at $406.97 on the NYSE, the price used in our valuationYahoo Finance
- 2 Nov 2026UNH closes at $400.44; the Q3 2026 Form 10-Q is not yet on EDGARYahoo Finance; SEC EDGAR
Why did UnitedHealth's medical care ratio fall?
The medical care ratio (MCR) is the share of premium revenue that UnitedHealthcare pays out in medical claims. It is the single number that drives a health insurer's profit: on $87bn of quarterly premiums, each percentage point is worth about $870m of operating profit.
UnitedHealth's MCR was 88.4% in Q3 2026, down from 89.9% in Q3 2025. Medical costs fell 3.7% to $76,982m while premiums fell 2.1%. The company gave four reasons: medical cost management, benefit design changes, pricing discipline and care delivery changes focused on affordability and value-based care. In plain terms, UnitedHealth raised prices and trimmed benefits for 2026 after the losses of 2025, and dropped some members who were not covered profitably.
One part of the improvement will not repeat. The quarter included $610m of net favourable reserve development: claims for earlier 2026 dates of service came in lower than UnitedHealth had reserved for. Adding the $610m back to medical costs gives an MCR of about 89.1%, still 0.8 points below a year earlier.
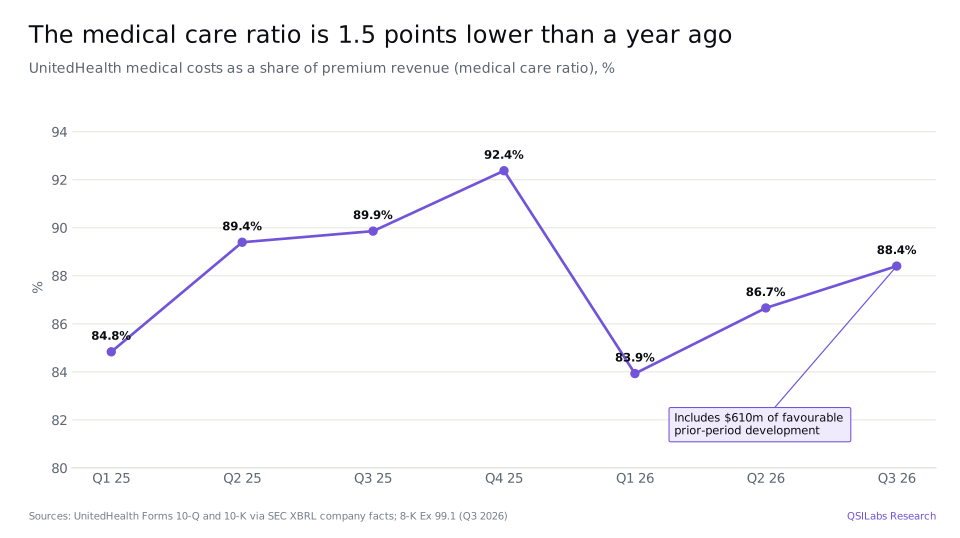
The ratio rises through the year in every year. Members use more care once they have met their deductibles, so the first quarter is the most profitable and the fourth the least. In 2024, before the cost shock, UnitedHealth's MCR was 84.3% in Q1, 85.1% in Q2 and 85.2% in Q3. Q3 2026 at 88.4% is better than 2025 but still about 3 points above 2024. That gap is the margin recovery still to be won, and it is why the 2027 price and benefit filings matter so much.
Reserves look steady. Days claims payable, a measure of how many days of medical costs UnitedHealth holds as a liability, were 47.0, unchanged from Q2 2026 and up from 46.2 a year earlier. Medical costs payable were $39,352m at 30 September.
How did UnitedHealthcare and Optum perform in Q3 2026?
UnitedHealth runs two businesses. UnitedHealthcare is the insurer. Optum provides care through Optum Health, data and software through Optum Insight, and pharmacy benefits through Optum Rx. Much of Optum's revenue comes from UnitedHealthcare and is eliminated on consolidation: corporate eliminations were $40.5bn in the quarter.
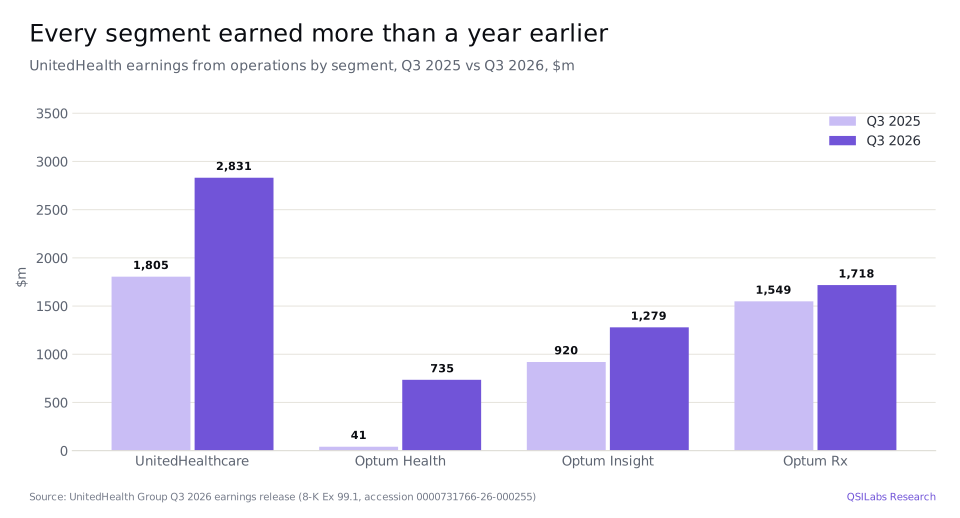
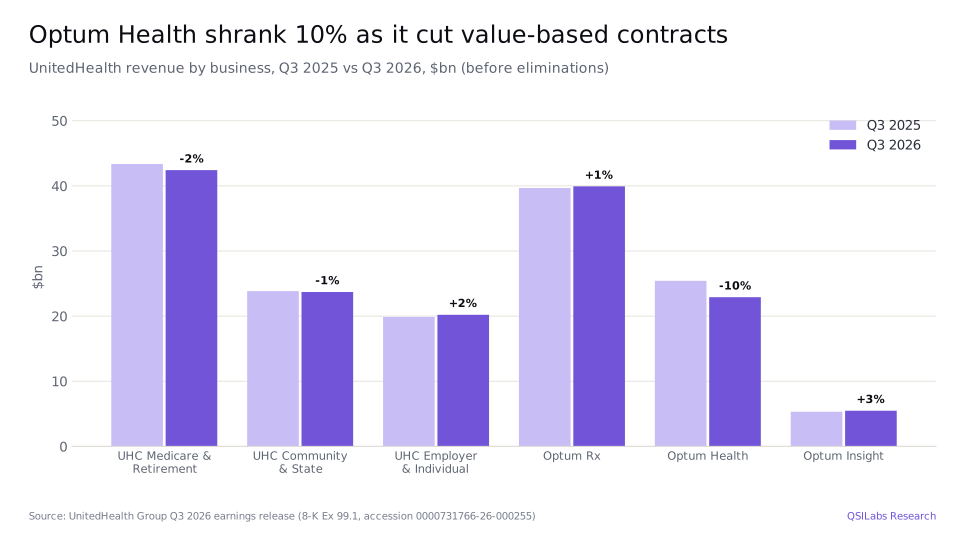
UnitedHealthcare revenue fell to $86,330m from $87,070m. Earnings from operations rose 57% to $2,831m, and its operating margin rose to 3.3% from 2.1%, though it was below the 4.6% of Q2 2026. Employer & Individual revenue rose to $20.2bn from $19.9bn. Medicare & Retirement fell to $42.4bn from $43.4bn because of fewer members and a changed product mix. Community & State, mainly Medicaid, was $23.7bn against $23.8bn.
Optum revenue fell to $66,883m from $69,177m, but earnings from operations rose 49% to $3,732m, for a margin of 5.6%, against 3.6%.
- Optum Health revenue fell 10% to $22,910m because it served fewer value-based care patients. It withdrew from markets where, in the company's words, it "lacked sufficient value-based care presence to sustain its clinicians". Earnings from operations were $735m, a 3.2% margin, against $41m and 0.2%.
- Optum Insight revenue rose 3% to $5,474m and earnings from operations rose to $1,279m from $920m, a 23.4% margin, helped by new products and lower costs.
- Optum Rx revenue was $39,927m, against $39,679m, and earnings from operations rose to $1,718m from $1,549m, helped by biosimilar adoption. Adjusted scripts fell to 393m from 414m as UnitedHealthcare and other clients covered fewer people.
Why is UnitedHealth losing members?
UnitedHealthcare served 48.3m people with medical coverage at 30 September 2026, down from 49.8m at the end of 2025 and 50.1m a year earlier. Most of the decline was deliberate. After 2025's losses, UnitedHealth repriced its plans and cut benefits for 2026, accepting fewer members in exchange for a better margin on those who stayed.
- Medicare Advantage: 7.605m, down from 8.435m a year earlier. Counting programmes for complex populations reported within Medicaid, seniors served through Medicare Advantage fell by 935,000 since the end of 2025.
- Medicaid: 6.695m, down from 7.46m, because of ongoing eligibility changes. Community & State lost 85,000 people in Q3 alone.
- Commercial risk-based: 7.575m, down from 8.44m. Employer & Individual lost 165,000 people in Q3 to employer attrition.
- Commercial fee-based: 22.18m, up from 21.49m. In these plans employers bear the medical cost and pay UnitedHealthcare to administer them.
Quality ratings matter as much as headcount in Medicare Advantage, because star ratings set bonus payments. UnitedHealth said at least 69% of its Medicare Advantage members are in plans rated four stars or more for 2027, in line with its expectations. It also reported improvement in 11 of 12 HEDIS quality measures. Optum Health served 92m consumers at 30 September, against 93m a year earlier.
UnitedHealth listed policy commitments alongside its results:
- committing $1bn to the United Health Foundation;
- eliminating and rebating 2026 profits on individual Affordable Care Act plans to about 1m members;
- removing 30% of prior approval volume by the end of 2026;
- passing through 100% of manufacturer drug rebates to clients by 1 January 2028.
The last of these changes how Optum Rx earns money.
How much cash does UnitedHealth generate?
Cash flow from operations was $5.1bn in Q3 2026, 1.2 times net income, and $25,087m in the first nine months, up 35% from $18,589m. Capital spending on property, equipment and software was $2,421m, against $2,674m. That left about $22.7bn of free cash flow in nine months.
UnitedHealth paid $6,170m of dividends and bought back $5,031m of stock in the nine months. It cut net borrowings by $3,075m. The quarterly dividend has been $2.32 a share since June 2026, $9.28 a year, a 2.3% yield at the 30 October price. Debt was $74.3bn at 30 September ($5.6bn short-term and $68.7bn long-term), and the debt-to-capital ratio was 41.7%, up from 41.2% at 30 June. UnitedHealth still targets about 40% by the end of 2026.
Most of UnitedHealth's cash cannot be paid out freely. At 30 September it held $28.5bn of cash and short-term investments and $58.1bn of long-term investments, but most of this sits in regulated insurance subsidiaries and backs medical liabilities and statutory capital. At 30 June, its latest disclosure, only $1.1bn was available for general corporate use. That is the only cash we add to our valuation.
UnitedHealth's 2026 guidance: what the raised outlook implies
UnitedHealth raised its 2026 outlook on 13 October. It now expects GAAP EPS of at least $19.50 and adjusted EPS of at least $20.50, against $13.23 of GAAP EPS in 2025. Projected net earnings attributable to shareholders are more than $17,650m, with about $1,405m of intangible amortisation.
The guidance implies a modest fourth quarter. After $17.50 of GAAP EPS and $18.30 of adjusted EPS in the first nine months, the floors imply at least $2.00 of GAAP EPS and $2.20 of adjusted EPS in Q4 2026. That is about half the Q3 figure, because the medical care ratio rises late in the year. It still compares with a fourth quarter of 2025 in which earnings from operations were just $380m.
Analysts polled by S&P Global, as reported by StockAnalysis on 27 October, expect 2026 adjusted EPS of $20.59 on revenue of $449.1bn. They expect $23.29 of adjusted EPS on revenue of $463.1bn in 2027. At $406.97, UnitedHealth trades at 19.9 times its 2026 adjusted EPS floor and 17.5 times consensus 2027 EPS.
UnitedHealth stock Q3 2026: is UNH overvalued?
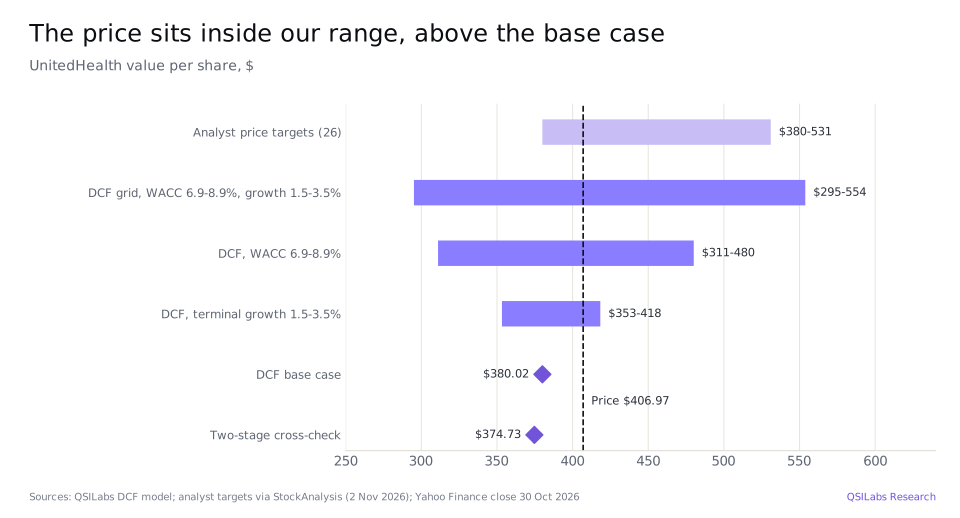
Modestly, on our numbers. Our discounted cash flow model values UnitedHealth at $380.02 a share, 6.6% below the $406.97 close on 30 October 2026. A two-stage cross-check gives $374.73. At $406.97 the shares were up 21.9% from $333.79 a year earlier (3 November 2025) and 23.3% since the end of 2025. That is below the 21 July 2026 high close of $436.35 and well above the 27 March low of $259.02.
The gap between our value and the price is about margin. We discount forecast cash flows to 2035 at a weighted average cost of capital of 7.92%, with 2.5% growth after 2035. That gives an enterprise value of $423.3bn. From it we deduct $74.3bn of debt and $7.5bn of minority interests and add the $1.1bn of general-corporate cash, which leaves $342.6bn of equity, or $380.02 for each of 901.6m diluted shares. UnitedHealth's market value at $406.97 is $366.9bn.
Method
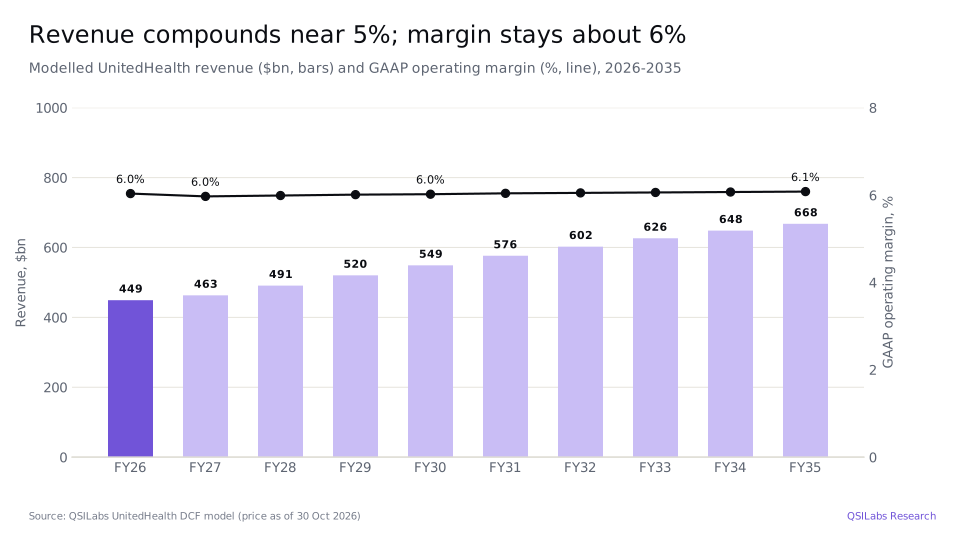
We forecast revenue of $449.1bn in 2026, in line with consensus. Growth is 3.1% in 2027, to $463.1bn, again in line with consensus, then 6% a year in 2028 and 2029, slowing to 3% by 2035, when revenue reaches $667.8bn. GAAP operating income is $27.1bn in 2026, the level implied by the guidance floor. The 2026 operating margin is 6.0%, or 6.3% adding back intangible amortisation, and we hold it close to that level, at 6.0-6.1%, through 2035.
That margin assumption drives the valuation. Between 2016 and 2024 UnitedHealth's operating margin, adding back intangible amortisation, ran between 7.5% and 9.2%; in 2025 it fell to 4.6%. Peers have not recovered either: the median comparable margin among mature, profitable managed care companies (Elevance, Cigna, CVS Health and Molina) was 2.7% in the year to 30 June 2026. We assume UnitedHealth keeps its 2026 recovery but does not return to its pre-2025 margins.
Other inputs: a 22% tax rate; capital spending and depreciation in line with recent levels; and working capital of minus 11.7% of revenue, because premiums arrive before claims are paid. Unlevered free cash flow is $23.9bn in 2027, rising to about $27.7bn by 2031. Terminal value is 58.6% of enterprise value.
How the number moves if you argue with us
| WACC \ terminal growth | 1.5% | 2.0% | 2.5% | 3.0% | 3.5% |
|---|---|---|---|---|---|
| 6.92% | $433.09 | $454.27 | $480.09 | $512.33 | $553.82 |
| 7.42% | $389.80 | $405.82 | $424.98 | $448.33 | $477.49 |
| 7.92% | $353.29 | $365.57 | $380.02 | $397.28 | $418.32 |
| 8.42% | $322.08 | $331.60 | $342.63 | $355.60 | $371.08 |
| 8.92% | $295.11 | $302.54 | $311.05 | $320.90 | $332.48 |
The 30 October price falls between our values at a 7.42% WACC ($424.98) and at 7.92% ($380.02). On our cash flows, the market is using a discount rate of about 7.6%. A bottom-up cost of capital built from market inputs is higher, at 9.29%, which would put the value below $311. The bull case is simpler than any discount rate. If UnitedHealth closes even part of the gap between its 2026 margin of about 6.3% (adding back amortisation) and its 7.5-9.2% range of 2016-2024, our cash flows rise substantially. The recovery in 2026 so far, from a 92.4% MCR in Q4 2025 to 88.4% in Q3 2026, shows that is possible. Our base case does not assume it.
The analyst consensus is more bullish than we are. The 26 analysts polled by S&P Global rate UnitedHealth a Buy, with an average 12-month price target of $476.64, a low of $380 and a high of $531.
Risks to the UnitedHealth investment case
- Medical cost trend. Q3 2026 included $610m of favourable reserve development. If medical cost trend runs above what UnitedHealth priced for 2027, the margin recovery stalls, as it did in 2025.
- Medicare Advantage funding and audits. UnitedHealth lists changes in Medicare, the CMS star ratings programme and risk adjustment data validation audits among its risks.
- Government investigations. The release lists "the DOJ's legal actions concerning our participation in the Medicare program" as a risk to its forecasts. UnitedHealth has published an independent review of its HouseCalls programme. It says the review found sampled diagnoses "overwhelmingly supported by medical records".
- Pharmacy benefit reform. Optum Rx's commitment to pass through 100% of manufacturer rebates to clients by 2028, and its fee-based pricing model, change how it earns money. Adjusted scripts also fell 5% in Q3, which the company attributes to lower membership.
- Shrinking membership. Fewer members mean less premium revenue and fewer Optum Rx scripts. If 2027 repricing loses more members than expected, revenue growth could fall below our 3.1% for 2027.
- Leverage. Debt-to-capital of 41.7% is above the 40% target, which limits buybacks until it comes down.
- Upside risk. A return to the 7.5-9.2% margins of 2016-2024 would lift our value well above the current price.
FAQ
What value does QSILabs put on UnitedHealth stock after Q3 2026?
Our discounted cash flow model values UnitedHealth Group at $380.02 a share, 6.6% below the $406.97 close on 30 October 2026, using a 7.92% cost of capital and 2.5% terminal growth. A two-stage cross-check gives $374.73. Varying the cost of capital from 6.92% to 8.92% and terminal growth from 1.5% to 3.5% gives $295-554.
Is UnitedHealth stock a buy after Q3 2026 earnings?
That depends on how far you think margins will recover. UnitedHealth's medical care ratio improved to 88.4% in Q3 2026 and it raised 2026 guidance, but our model, which holds operating margin near 6%, puts the value slightly below the price. Analysts are more positive: 26 rate it a Buy, with an average target of $476.64. This is not investment advice.
What were UnitedHealth's Q3 2026 earnings?
UnitedHealth reported Q3 2026 revenue of $112.7bn, down 0.4%. Earnings from operations were $6.6bn, up from $4.3bn. Diluted EPS was $4.56, up from $2.59, and adjusted EPS was $4.69, up from $2.92. Cash flow from operations was $5.1bn. The results were released on 13 October 2026.
What is UnitedHealth's medical care ratio?
UnitedHealth's medical care ratio, medical costs as a share of premiums, was 88.4% in Q3 2026, against 89.9% in Q3 2025. It includes $610m of favourable development on earlier 2026 claims. For the full year 2025, the quarterly ratio peaked at 92.4% in the fourth quarter.
What is UnitedHealth's 2026 guidance?
UnitedHealth expects 2026 GAAP EPS of at least $19.50 and adjusted EPS of at least $20.50, raised on 13 October 2026. It projects net earnings of more than $17.65bn. After nine months, the guidance implies at least $2.20 of adjusted EPS in the fourth quarter.
How did Optum perform in Q3 2026?
Optum's revenue fell 3% to $66.9bn, but earnings from operations rose 49% to $3.7bn, a 5.6% margin. Optum Health earned $735m, up from $41m, on 10% lower revenue. Optum Insight earned $1.3bn and Optum Rx $1.7bn.
Why is UnitedHealth losing Medicare Advantage members?
UnitedHealth repriced its plans and cut benefits for 2026 to restore margins after medical costs surged in 2025. Its Medicare Advantage membership fell to 7.6m at 30 September 2026 from 8.4m a year earlier. Including complex-care programmes, seniors served in Medicare Advantage fell by 935,000 since the end of 2025.
Does UnitedHealth pay a dividend?
Yes. UnitedHealth pays $2.32 a share each quarter, $9.28 a year, a yield of about 2.3% at the 30 October 2026 price. It paid $6.2bn of dividends and bought back $5.0bn of shares in the first nine months of 2026.
Sources
- UnitedHealth Group, third quarter 2026 earnings release (Form 8-K, Exhibit 99.1, 13 Oct 2026; accession 0000731766-26-000255) www.sec.gov
- UnitedHealth Group, third quarter 2026 earnings presentation (Form 8-K, Exhibit 99.2, 13 Oct 2026; accession 0000731766-26-000255) www.sec.gov
- UnitedHealth Group, Form 8-K dated 13 Oct 2026 (accession 0000731766-26-000255) www.sec.gov
- UnitedHealth Group, Form 10-Q for the quarter ended 30 Jun 2026 (accession 0000731766-26-000197) www.sec.gov
- SEC XBRL company facts for UnitedHealth Group (CIK 731766): quarterly revenue, premiums, medical costs and earnings from operations from Forms 10-Q and 10-K data.sec.gov
- StockAnalysis: UnitedHealth Group forecast and analyst ratings, S&P Global data (page updated 27 Oct 2026, accessed 2 Nov 2026) stockanalysis.com
- Yahoo Finance chart data: UNH closing prices and dividends (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry (US), January 2026 pages.stern.nyu.edu
- QSILabs UnitedHealth discounted cash flow model (internal; price as of 30 Oct 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Eli Lilly stock Q3 2026: Mounjaro and Zepbound, Johnson & Johnson stock Q3 2026, AbbVie stock Q3 2026: Skyrizi and Rinvoq and JPMorgan stock Q3 2026.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.