Research / Earnings and valuation
Verizon Stock Q3 2026:Phone Growth Returns as Free Cash Flow Rises 12%
As of: Figures are as of Verizon Communications Inc.'s third-quarter 2026 results (the quarter ended 30 September 2026, reported 26 October 2026 in a Form 8-K) and its Form 10-Q for that quarter, dated 29 October 2026. Verizon's fiscal year is the calendar year, so its Q3 2026 covers July to September 2026. The share price used in our valuation is the NYSE close of VZ on 2 November 2026, $45.05; analyst data were accessed on 2 November 2026. Published 2 November 2026.
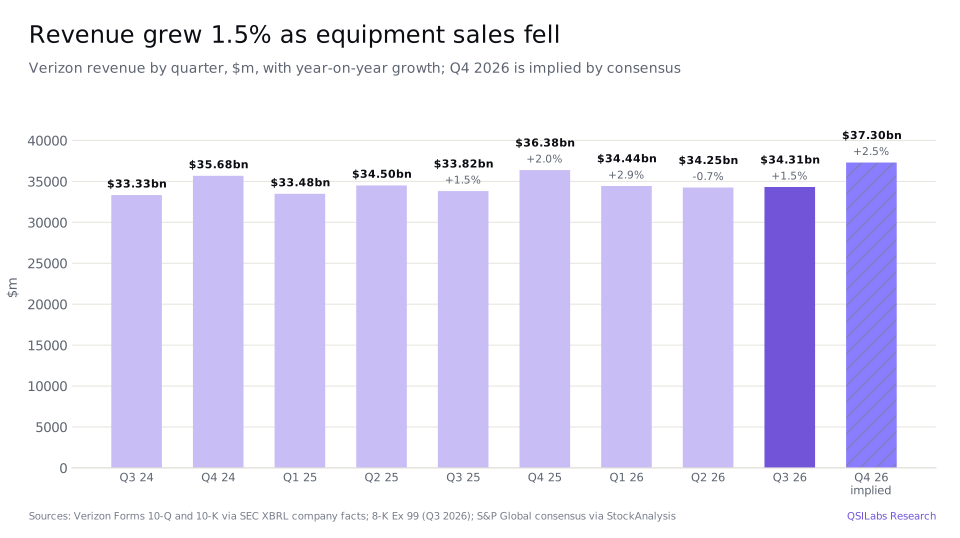
The short answer. Verizon stock Q3 2026 comes down to a quarter in which the phone business started growing again. Verizon added 406,000 postpaid phone customers in the three months to 30 September 2026, against 44,000 a year earlier, while churn fell and promotional spending dropped. Revenue rose 1.5% to $34.31bn, held back by a 9.0% fall in equipment sales, but service revenue grew faster, adjusted EBITDA rose 8.0% to $13.80bn and free cash flow rose 12.1% to $7.80bn. Verizon called it "another record-breaking quarter" and raised its 2026 guidance for the third time. Our discounted cash flow model values the shares at $104.96, against a $45.05 close on 2 November 2026; that gap rests mostly on a low cost of capital and a long-lived telecom network, so we show below how far it moves when you change those inputs.
Key takeaways
- Phone customers are growing again. Postpaid phone net additions were 406,000, against 44,000 a year earlier, and 645,000 in the first nine months, against a loss of 254,000 in 2025. Verizon added 137,000 postpaid accounts, which it said was its best result in over a decade.
- Fewer customers left, at lower cost. Postpaid phone churn fell to 0.94% from 0.98%. Promotional cost of acquisition fell 41% and retention spending fell 30%, and chief executive Dan Schulman said "there were no free lines".
- Revenue grew 1.5%, service revenue 2.9%. Total revenue was $34,313m. Mobility and broadband service revenue grew 2.9% to about $23.5bn, while wireless equipment revenue fell 9.0% as fewer customers upgraded their phones.
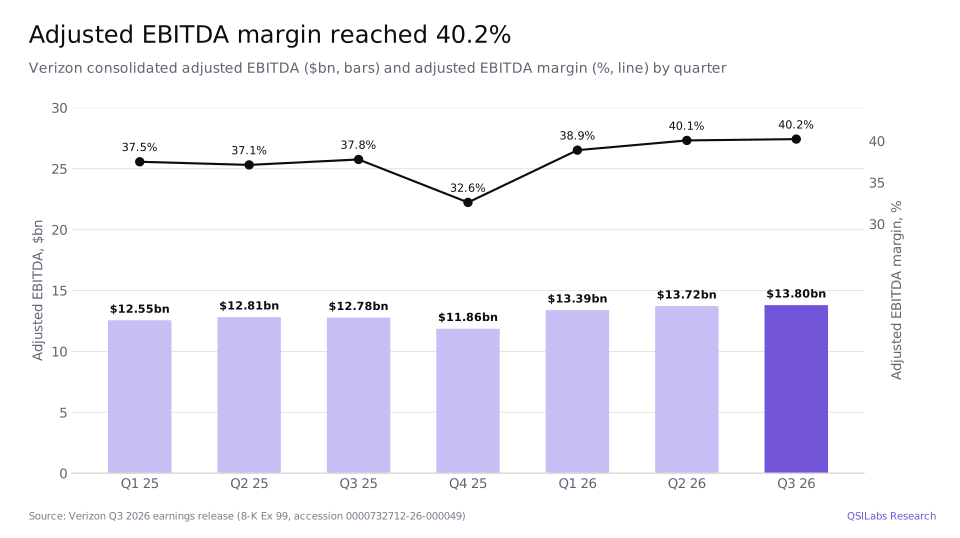
- Margins reached a high. Adjusted EBITDA rose 8.0% to $13,802m, a 40.2% margin, up from 37.8%; Verizon said this was the highest margin it has reported. GAAP operating income rose 6.7% to $8,650m.
- Free cash flow rose 12.1%. Free cash flow was $7,801m in the quarter and $18,010m in nine months, up 14.3%. Verizon now expects $22.44bn to $22.54bn for 2026.
- Guidance raised again. Verizon now expects 1.1m to 1.2m postpaid phone net additions in 2026 and adjusted earnings per share of $5.04 to $5.06, up 7.0% to 7.5%.
- Our value: $104.96 a share, against a $45.05 close on 2 November 2026. A two-stage cross-check gives $94.79 and a low-growth scenario $99.94; analysts' average target is $50.65.
- What to watch. Whether wireless service revenue grows in the fourth quarter as management expects, the pace of fiber and fixed wireless additions after the Frontier deal, debt reduction toward Verizon's target leverage range in 2027, and the 2027 outlook due with the next results.
Key numbers from Verizon's Q3 2026 earnings
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total operating revenue | $34,313m | $33,821m | +1.5% |
| Service and other revenue | $29,197m | $28,202m | +3.5% |
| Wireless equipment revenue | $5,116m | $5,619m | -9.0% |
| Operating income | $8,650m | $8,105m | +6.7% |
| Net income attributable to Verizon | $5,198m | $4,950m | +5.0% |
| Diluted earnings per share | $1.25 | $1.17 | +6.8% |
| Adjusted earnings per share | $1.31 | $1.21 | +8.3% |
| Adjusted EBITDA | $13,802m | $12,775m | +8.0% |
| Postpaid phone net additions | 406,000 | 44,000 | +362,000 |
| Broadband net additions | 314,000 | 322,000 | -8,000 |
| Free cash flow | $7,801m | $6,956m | +12.1% |
Source: Verizon Q3 2026 earnings release (Form 8-K, Exhibit 99).
Verizon Q3 2026 earnings: what happened
Verizon reported third-quarter results on 26 October 2026. Revenue rose 1.5% to $34,313m from $33,821m. Service and other revenue, the recurring part of the business, rose 3.5% to $29,197m, while wireless equipment revenue, mostly phones sold to customers, fell 9.0% to $5,116m. For the first nine months, revenue was $103,006m, up 1.2%.
Operating income rose 6.7% to $8,650m, a margin of 25.2% against 24.0% a year earlier. Costs of services rose to $7,265m from $6,863m, but the cost of equipment fell to $5,823m from $6,483m and selling, general and administrative expense fell to $7,480m from $7,752m. Depreciation and amortisation rose 10.3% to $5,095m, and interest expense rose 17.2% to $1,950m as debt rose to $166.2bn.
Net income was $5,320m, up 5.2%, and $5,198m was attributable to Verizon. Diluted earnings per share rose 6.8% to $1.25, helped by a 1.7% fall in the diluted share count to 4,161m after this year's buybacks. Adjusted earnings per share, which exclude special items, rose 8.3% to $1.31. There were no special items in the third quarter; the second quarter included $397m of severance and a $746m loss on the business being moved into the BT joint venture.
Adjusted EBITDA, Verizon's measure of operating profit before depreciation and amortisation and special items, rose 8.0% to $13,802m. The margin was 40.2%, up from 37.8% and 40.1% in the second quarter. Chief financial officer Tony Skiadas said it was "our highest reported" and credited Verizon's $5bn operating cost efficiency programme. Schulman said Verizon's "$9 billion cost reduction plan across our OpEx and CapEx remains fully on track".
Verizon also signed a dark fiber agreement with Amazon Web Services that Schulman valued at over $2bn, building on a Google agreement announced the previous quarter, and said Verizon had signed contracts for about $4bn as it sells fiber and edge computing to builders of AI infrastructure, a business it calls AI Connect. Schulman said Verizon had not yet begun to recognise significant revenue from AI Connect.
- 16 Jan 2026VZ closes at $38.91, its 52-week closing lowYahoo Finance
- 20 Jan 2026Acquisition of Frontier completed, extending Verizon's fiber footprint to 31 states and Washington D.C.Form 10-Q
- Feb-Mar 2026$2.5bn accelerated share repurchase; further repurchases follow in April and JulyForm 10-Q
- 1 Jun 2026Purchase of spectrum licences from UScellular completed for $1.0bnForm 10-Q
- June 2026FCC Auction 113 ends; Verizon wins 82 AWS-3 licences and pays $3.2bn in the nine monthsForm 10-Q
- Mid-June 2026Simplicity plans, Verizon One and a loyalty programme launchedQ3 2026 earnings call
- 28 Jun 2026Agreement to put the international wireline business into a 50:50 joint venture with BT GroupForm 10-Q
- 15 Sep 2026VZ closes at $51.45, its 52-week closing highYahoo Finance
- 26 Oct 2026Q3 results: 406,000 postpaid phone net adds, guidance raised a third time, AWS deal; VZ closes at $43.108-K; call; Yahoo
- 29 Oct 2026Form 10-Q for the quarter datedForm 10-Q
- 2 Nov 2026VZ closes at $45.05, the price used in our valuationYahoo Finance
- 2027Verizon expects to reach its target leverage range and to give 2027 growth detail on its next callQ3 2026 earnings call
How did Verizon add 406,000 phone customers?
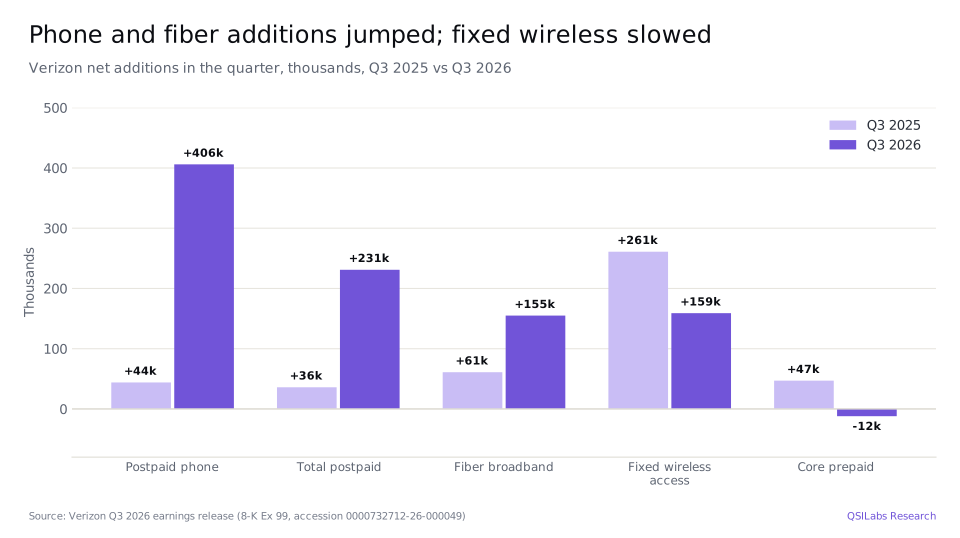
Verizon spent 2025 losing phone customers. In the first nine months of 2025 it lost 254,000 postpaid phones; in the same period of 2026 it added 645,000. The third quarter brought 406,000, of which 266,000 came from consumers and 140,000 from business customers, against 44,000 in total a year earlier. Postpaid accounts, the households and businesses that pay a monthly bill, rose by 137,000, which Verizon said was its best result in over a decade.
The improvement came from both sides. Gross additions rose 11%, according to Skiadas, and fewer customers left: postpaid phone churn fell to 0.94% from 0.98%, and to 0.87% for consumers. Verizon launched new Simplicity plans, its Verizon One app and a loyalty programme in mid-June, and Schulman said the quarter showed "growth that pays. Every new line we added delivered revenue. There were no free lines." He also said: "I don't consider free lines to even be net adds. I think they're churn waiting to happen."
The additions were also cheaper. Promotional cost of acquisition fell 41% and promotional spending on retention fell 30%. The upgrade rate fell to 2.6% from 3.3%, and Skiadas said upgrade volumes were down over 20%. That cut equipment revenue, but it also cut the cost of equipment and the subsidies that come with each new phone.
There is a cost on the other side. Average revenue per postpaid account fell 1.9% to $168.08, as new customers joined on cheaper plans and promotions rolled off. Core prepaid lost 12,000 customers, against 47,000 additions a year earlier. Schulman said there is "potentially room for us to adjust that price-to-value equation by increasing pricing as well", but Verizon has not announced a price rise. Verizon now expects 1.1m to 1.2m postpaid phone net additions in 2026, up from the upper half of 750,000 to 1.0m.
Why did revenue grow only 1.5%?
Because Verizon sold fewer phones. Equipment revenue does little for profit, as phones are sold close to cost, but it is a large part of revenue: $5,116m in the third quarter, down from $5,619m. Consumer wireless equipment revenue fell 10.3% to $4,277m and business equipment revenue fell 1.6% to $839m.
The recurring lines grew. Consumer mobility and broadband service revenue rose 3.6% to $19,777m, and total mobility and broadband service revenue rose 2.9% to about $23.5bn, after 1.6% in the first quarter and 2.8% in the second. Wireless service revenue was just over $20.9bn, Skiadas said, and Verizon expects it to grow in the fourth quarter, with mobility and broadband service revenue growth of about 4%. Other revenue grew 6.0% in Consumer and 10.0% in Business.
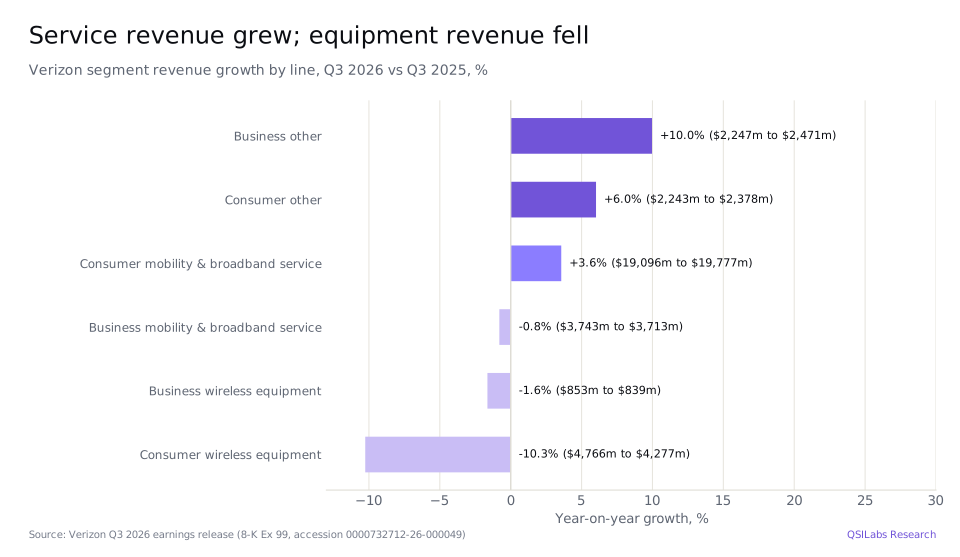
By segment, Consumer revenue rose 1.3% to $26,432m and its segment EBITDA rose 6.5% to $11,965m, a 45.3% margin against 43.0%. Business revenue rose 2.6% to $7,023m, and segment EBITDA rose 13.0% to $1,941m, a 27.6% margin against 25.1%. Business mobility and broadband service revenue slipped 0.8% to $3,713m, so the growth in Business came from other revenue, up 10.0% to $2,471m.
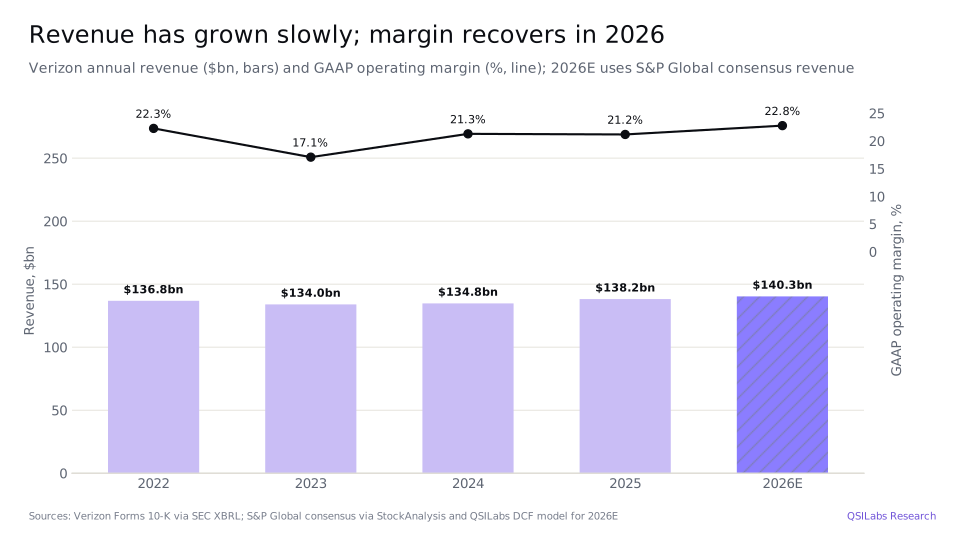
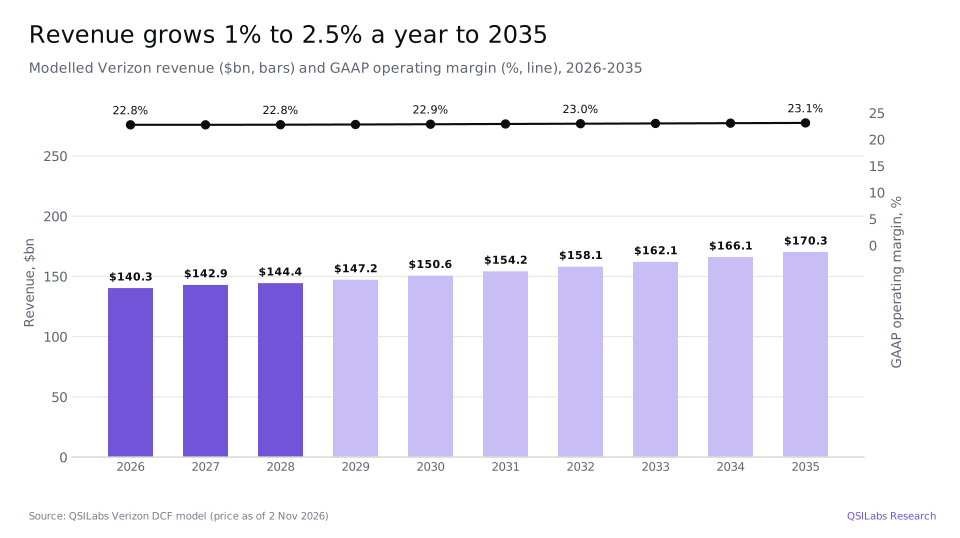
Over a longer period, revenue has grown slowly. Annual revenue was $136.8bn in 2022, $134.0bn in 2023, $134.8bn in 2024 and $138.2bn in 2025, and S&P Global consensus expects $140.3bn in 2026, up 1.5%, including Frontier from late January. The GAAP operating margin dropped to 17.1% in 2023 and recovers to about 22.8% in our 2026 estimate.
How is the broadband business changing after Frontier?
Verizon completed its acquisition of Frontier Communications on 20 January 2026, extending its fiber network to 31 states and Washington D.C. It assumed $12.9bn of Frontier debt, at fair value, and repaid $12.4bn of it in the first nine months. It also bought Starry on 30 January.
At 30 September Verizon had 17.4m broadband connections, up 33.5% in a year: 11.1m on fiber, up 44.2% including Frontier, and 6.4m on fixed wireless access, which delivers home internet over the mobile network, up 18.1%. In the quarter it added 155,000 fiber customers, against 61,000 a year earlier, and 159,000 fixed wireless customers, against 261,000. Total broadband net additions were 314,000, slightly below the 322,000 of a year earlier.
Verizon expects to pass more than 32m homes and businesses with fiber by the end of 2026 and has a medium-term target of 40m to 50m. Schulman said over 55% of new fiber customers take speeds of 1 gigabit or more, and that Verizon plans 1 gigabit fixed wireless using millimetre-wave spectrum to reach another 10m to 15m premises. Skiadas said Verizon expects over $1bn of run-rate operating cost savings from Frontier by 2028.
The deal also changed the balance sheet. Total debt rose to $166.2bn at 30 September from $158.2bn at the end of 2025, and cash fell to $4.5bn from $19.0bn, as Verizon paid for Frontier, repaid most of Frontier's debt and spent $4.4bn on wireless licences, including $1.0bn for UScellular spectrum and AWS-3 licences won in an FCC auction. Net unsecured debt was 2.3 times adjusted EBITDA, against 2.2 times at the end of 2025. Skiadas said: "We remain on track to reach our target leverage range during the 2027 timeframe."
How much free cash flow does Verizon generate?
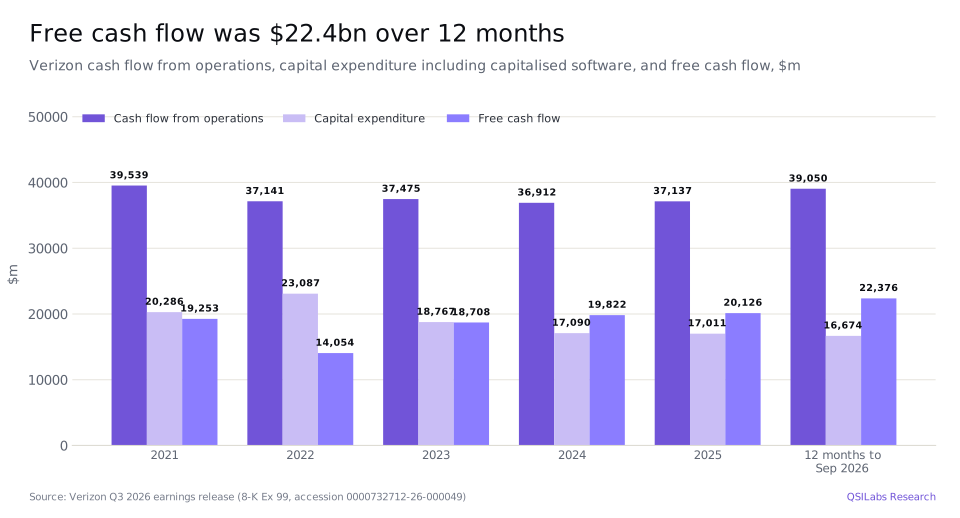
A lot, relative to its share price. Free cash flow, cash flow from operations less capital expenditure, was $7,801m in the third quarter, up 12.1% from $6,956m; Schulman said it was the highest quarterly figure since 2020. Cash flow from operations was $11,517m and capital expenditure $3,716m, down from $4,310m. For the first nine months, free cash flow was $18,010m, up 14.3%.
Over the 12 months to September 2026, cash flow from operations was $39,050m and capital expenditure $16,674m, giving free cash flow of $22,376m, against $20,126m for 2025 and $14,054m in 2022, when capital expenditure peaked at $23,087m. Verizon now expects 2026 free cash flow of $22.44bn to $22.54bn, up from $21.94bn to $22.14bn, and growth approaching 12%, with capital expenditure of $16.0bn to $16.5bn, including AI Connect.
The headline measure leaves out spectrum. Verizon spent $4,384m on wireless licences in the first nine months and $9,480m on acquisitions, mainly Frontier. It paid $8,804m of dividends and spent $4,000m on buybacks, and expects buybacks of up to $4.5bn for the year. Including dividends and buybacks it returned $12.8bn to shareholders in nine months, up 49%.
At the guidance midpoint, 2026 free cash flow of $22.49bn is about 12.0% of Verizon's $186.7bn market value at the 2 November close. The quarterly dividend is $0.7075 a share, up from $0.69, or about $11.7bn a year on 4,145m shares, a little over half of that free cash flow.
How has VZ stock performed in 2026?
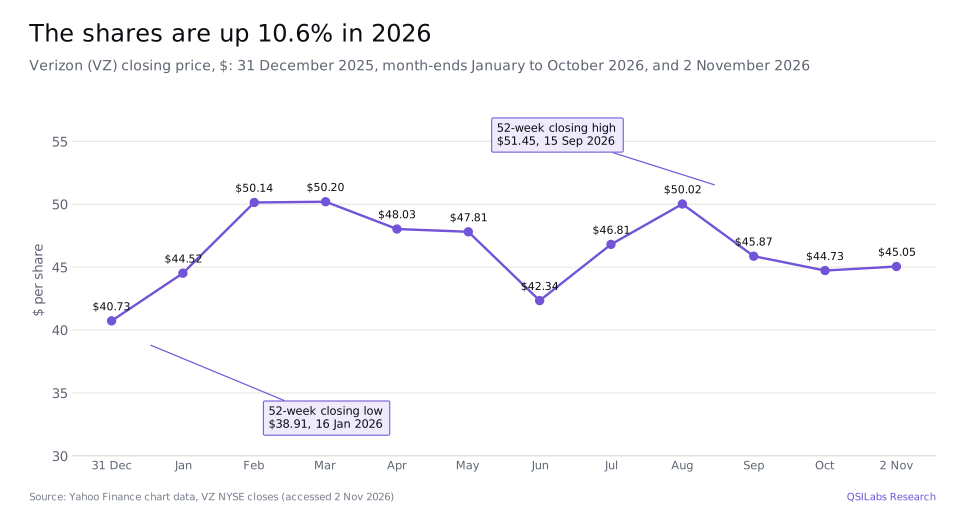
Verizon shares closed at $45.05 on 2 November 2026, up 10.6% from $40.73 at the end of 2025. They hit a 52-week closing low of $38.91 on 16 January, rose to $50.20 by the end of March, fell to $42.34 in June and reached a closing high of $51.45 on 15 September before falling back to $44.73 at the end of October.
On results day, 26 October, the shares closed at $43.10, down from $44.66 on 23 October, before recovering to $45.05 by 2 November. The shares yield about 6.3% on the $2.83 annual dividend.
Verizon stock Q3 2026: is VZ undervalued?
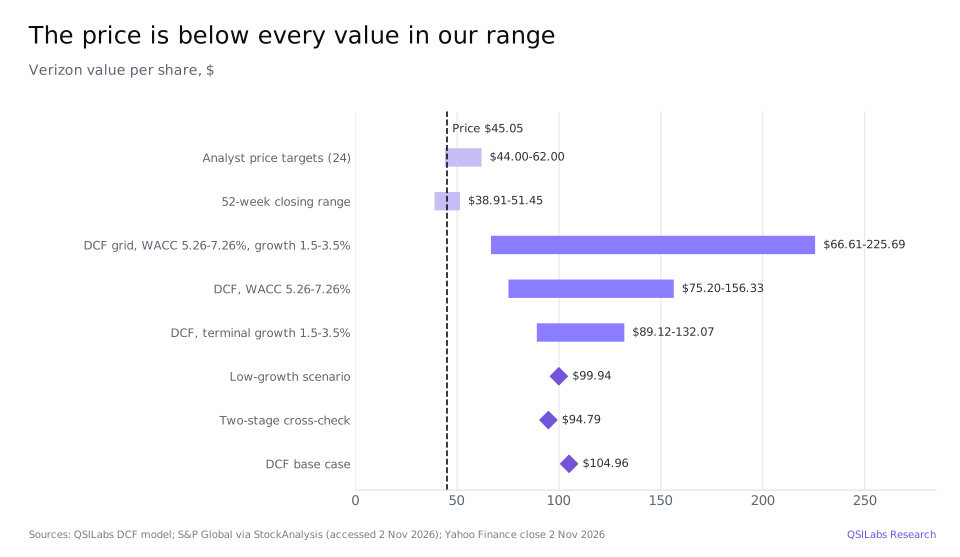
On our numbers, yes. Our discounted cash flow model values Verizon at $104.96 a share, about 2.3 times the $45.05 close on 2 November 2026. At that price the equity was worth about $186.7bn, on 4,145m shares, and the enterprise value, adding debt of $166.2bn and deducting $4.5bn of cash, about $348.5bn. That is 6.6 times the $52.78bn of adjusted EBITDA Verizon reported for the past four quarters, and 15.0 times our estimate of 2026 unlevered free cash flow, $23.17bn. The price is 8.9 times consensus 2026 earnings per share of $5.06.
The gap comes from the cost of capital and how long the market thinks Verizon's cash flow will last. Our enterprise value of $606.5bn is 11.5 times trailing adjusted EBITDA. Because debt is close to the market value of the equity, changes in enterprise value move the value per share a lot: a 10% change in our enterprise value changes our value per share by about 14%, and a 10% change in the market's enterprise value would move the share price by about 19%.
Analysts are much closer to the market. The 24 analysts tracked by S&P Global rate Verizon a Buy on average, with an average price target of $50.65, a median of $50 and a range from $44 to $62. In October 9 rated it a Strong Buy, 3 a Buy and 12 a Hold. After the results Freedom Capital Markets upgraded the shares to Buy with a $55 target; Citi has a $53 target, Goldman Sachs $47, Scotiabank $50 and TD Cowen $55, all with Buy ratings.
Method
We forecast revenue and GAAP operating margin year by year to 2035, apply a 23.6% tax rate, Verizon's effective rate for the first nine months of 2026, and deduct capital spending, including spectrum and finance leases, and working capital to reach unlevered free cash flow. We discount those cash flows at a 6.26% weighted average cost of capital, built from Damodaran's January 2026 data for US telecom services companies: equity is 51% of capital at a cost of 7.92%, from a 5.12% risk-free rate, a beta of 0.63 and an equity risk premium of 4.46% for the US, where Verizon earns almost all its revenue; debt is 49% at a pre-tax cost of 6.03%, the yield on Verizon's own bonds blended with its lease rate, taxed at 25%. After 2035 we assume growth of 2.5% a year; that terminal value is 69.7% of our enterprise value of $606.5bn. Deducting debt of $166.23bn, which includes finance leases and $30.14bn of secured debt, and $1.31bn of minority interests, adding cash of $4.50bn, investments of $0.80bn and about $2.14bn of cash generated between 30 September and 2 November, and deducting $7.99bn of pension and retiree health obligations after tax and the $2.93bn fourth-quarter dividend, gives equity value of $435.5bn, or $104.96 a share on 4,149m diluted shares.
For 2026 we use the S&P Global consensus revenue of $140.31bn, up 1.5%, which implies fourth-quarter revenue of about $37.30bn, and GAAP operating income of $31.94bn, a 22.77% margin; that is nine-month operating income of $24.07bn and fourth-quarter operating income of about $7.87bn, in line with Verizon's adjusted earnings per share guidance. For 2027 we use consensus revenue of $142.91bn, up 1.85%. For 2028 growth of 1.06% takes revenue to about $144.4bn, in line with S&P Global's three-year forecast of 1.48% annual growth from 2025. Growth then rises to 1.95% in 2029 and 2.3% in 2030, PwC's forecast of annual growth in global internet access spending from 2025 to 2030, and to 2.5% from 2032. Verizon gives no long-term revenue target.
The operating margin is 22.77% in 2026 and 2027 and edges up to 23.13% by 2035. We hold the margin before amortisation of acquired intangible assets at its 2026 level and keep that amortisation at a fixed dollar amount, so it shrinks as a share of revenue. Capital spending is $21.68bn in 2026: the $16.25bn midpoint of guidance, $4.38bn of spectrum and $1.04bn of finance-lease additions. In 2027 it is $19.50bn, including an average year of spectrum spending, and it rises to $26.21bn by 2035, about 15.4% of revenue. Depreciation and amortisation is 14.6% of revenue in 2026 and 14% from 2031.
We forecast unlevered free cash flow of $23.2bn in 2026 and $25.4bn in 2027, rising to $25.9bn in 2030 and $27.7bn in 2035; only the part of 2026 after 2 November is discounted. Our 2026 figure is above Verizon's own free cash flow guidance because it is measured before interest, which cost $1.95bn in the third quarter alone, although we also charge spectrum and finance leases as capital spending and tax at the full effective rate. Our previous model, dated 26 October and priced at $43.10, gave $99.44; it assumed revenue growth of about 2% a year from 2027, a 22.0% operating margin in 2027 and a 24% tax rate, which we have replaced with the consensus path, the 2026 margin and the nine-month tax rate above, and it had 2027 capital spending of $18.64bn.
How the number moves if you argue with us
The table shows our value per share at different costs of capital and terminal growth rates. Even at a 7.26% cost of capital and 1.5% terminal growth, the model gives $66.61, about 1.5 times the share price.
| Cost of capital | Growth 1.5% | Growth 2.0% | Growth 2.5% | Growth 3.0% | Growth 3.5% |
|---|---|---|---|---|---|
| 5.26% | $123.73 | $137.55 | $156.33 | $183.36 | $225.69 |
| 5.76% | $104.38 | $114.07 | $126.70 | $143.84 | $168.52 |
| 6.26% | $89.12 | $96.13 | $104.96 | $116.45 | $132.07 |
| 6.76% | $76.79 | $81.97 | $88.33 | $96.35 | $106.79 |
| 7.26% | $66.61 | $70.51 | $75.20 | $80.96 | $88.22 |
A lower-growth scenario, in which revenue grows 1.48% every year from 2027 to 2035, S&P Global's three-year rate, and the operating margin stays at 22.77%, gives $99.94 a share. A two-stage version of the model, which extends the fade over more years, gives $94.79. Using a cost of debt for the industry rather than Verizon's own bonds raises the cost of capital to 6.42% and gives $99.17.
Two checks point lower. Debt is 49% of capital in our cost of capital, which is high; Verizon's own debt is about 47% of its market value, so the weight is close to reality, but a lower debt weight would raise the rate. A single global telecom beta relevered at Verizon's own ratio of debt to equity gives a cost of capital of 6.69%, close to the 6.76% row, where the value is $88.33. A bottom-up cost of capital of 7.74%, our cross-check, is above every row in the table and would lower the value to below the $75.20 of the 7.26% row.
Our numbers and the market's can both be right only if Verizon's cash flow stops growing or shrinks for a long time, or if investors demand a much higher return than the cost of capital for telecom companies implies. The pressures are real: price competition among wireless carriers, the cost of building fiber, high debt and rising interest costs. We think the price already allows for most of that.
Risks to the Verizon investment case
- Wireless competition. Verizon's phone growth came with lower revenue per account, down 1.9%, and a sharp fall in promotional spending. If rivals respond with richer offers, Verizon may have to spend more to keep growing, or accept slower growth.
- Revenue growth is slow. Total revenue grew 1.5% and consensus expects 1.85% in 2027. Equipment revenue fell 9.0% and Business mobility service revenue fell 0.8%, so service growth has to carry the whole company.
- Debt and interest. Total debt is $166.2bn and interest expense rose 17.2% in the quarter. Verizon expects to reach its target leverage range in 2027; until then buybacks and spectrum spending compete with debt repayment.
- Fiber building and integration. Verizon plans to pass 40m to 50m premises with fiber and expects over $1bn of Frontier cost savings by 2028. Building costs, integration problems or slower take-up would reduce the return on that investment.
- AI Connect is early. About $4bn of signed contracts and the AWS and Google deals are promising, but Verizon has not yet begun to recognise significant revenue from AI Connect, and it depends on demand from builders of AI infrastructure.
- Valuation risk. Our value depends heavily on the terminal value, 69.7% of enterprise value, and on a 6.26% cost of capital with 49% debt. A higher rate or slower long-term growth would bring it much closer to the share price.
FAQ
What value does QSILabs put on Verizon stock?
Our discounted cash flow model gives $104.96 a share, against a $45.05 close on 2 November 2026. Across costs of capital from 5.26% to 7.26% and terminal growth from 1.5% to 3.5% the value ranges from $66.61 to $225.69. A two-stage cross-check gives $94.79 and a low-growth scenario $99.94.
Should I buy Verizon stock after the Q3 2026 results?
We do not give personal advice. On our numbers the shares trade well below the value of their cash flows, and the third quarter showed phone growth, lower churn and higher free cash flow. The case depends on a low cost of capital and steady long-term growth, and on Verizon reducing debt as planned, so read the risks above before deciding.
How much revenue did Verizon make in its latest quarter?
Verizon reported revenue of $34,313m for the third quarter of 2026, the three months to 30 September, up 1.5% from $33,821m. Service and other revenue was $29,197m and wireless equipment revenue $5,116m. Net income attributable to Verizon was $5,198m, or $1.25 a diluted share.
What dividend does Verizon pay?
Verizon pays a quarterly dividend of $0.7075 a share, up from $0.69 a year earlier, or $2.83 a year. At the $45.05 close on 2 November 2026 that is a yield of about 6.3%. Verizon paid $8,804m of dividends in the first nine months of 2026, about half of its $18,010m of free cash flow.
What price target do analysts have for VZ?
The 24 analysts tracked by S&P Global have an average target of $50.65, about 12% above the $45.05 close on 2 November 2026, with a median of $50, a low of $44 and a high of $62. Their consensus rating is Buy. After the results Freedom Capital Markets upgraded the shares to Buy with a $55 target.
How much does Verizon owe?
Total debt was $166,233m at 30 September 2026, up from $158,150m at the end of 2025, against cash of $4,495m. Unsecured debt was $136,095m, and net unsecured debt was 2.3 times adjusted EBITDA. Verizon expects to reach its target leverage range in 2027.
What is Verizon AI Connect?
AI Connect is Verizon's business selling fiber and edge computing to companies building AI infrastructure. Schulman said Verizon had signed contracts for about $4bn, including a dark fiber agreement with Amazon Web Services valued at over $2bn, and that significant revenue had not yet begun.
What guidance did Verizon raise in October 2026?
Verizon now expects 1.1m to 1.2m postpaid phone net additions in 2026, adjusted earnings per share of $5.04 to $5.06 and free cash flow of $22.44bn to $22.54bn. It expects mobility and broadband service revenue growth in the upper half of its 2.5% to 3.0% range and capital spending of $16.0bn to $16.5bn.
Who runs Verizon?
Dan Schulman is chief executive of Verizon, and Tony Skiadas is chief financial officer. Schulman described the third quarter as coming "one year into our transformation".
Sources
- Verizon Communications Inc., third-quarter 2026 results (Form 8-K, Exhibit 99, 26 Oct 2026; accession 0000732712-26-000049) www.sec.gov
- Verizon Communications Inc., Form 10-Q for the quarter ended 30 Sep 2026 (dated 29 Oct 2026; accession 0000732712-26-000052) www.sec.gov
- Verizon Communications Inc., Form 10-Q for the quarter ended 30 Jun 2026 (accession 0000732712-26-000046) www.sec.gov
- SEC XBRL company facts for Verizon Communications Inc. (CIK 732712): quarterly and annual revenue and operating income from Forms 10-Q and 10-K data.sec.gov
- Verizon Q3 2026 earnings call transcript, 26 Oct 2026 (LSEG StreetEvents edited transcript, published by Verizon; accessed 2 Nov 2026) www.verizon.com
- StockAnalysis: Verizon forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: Verizon statistics (accessed 2 Nov 2026) stockanalysis.com
- PwC, Global Entertainment & Media Outlook 2026-30 press release, 22 Jun 2026 www.pwc.com
- Yahoo Finance chart data: VZ closing prices and dividends (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry (US), January 2026 pages.stern.nyu.edu
- QSILabs Verizon discounted cash flow model (internal; price as of 2 Nov 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Comcast stock Q3 2026: broadband and Peacock, Cisco stock Q3 2026: AI networking orders, Amazon stock Q3 2026: AWS and retail and Alphabet stock Q3 2026.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.