Research / Earnings and valuation
Southern Copper Stock Q3 2026:Sales Up 39% on $6.41 Copper
As of: Figures are as of Southern Copper Corporation's results for the quarter ended 30 September 2026, published 21 October 2026 in a Form 8-K (release dated 20 October), the Form 10-Q filed on 30 October 2026 and the 22 October 2026 earnings call. Balance-sheet figures are from 30 September 2026. The share price used in our valuation is the NYSE close of SCCO on 2 November 2026, $179.36; analyst data were accessed on 2 November 2026. Published 2 November 2026.
The short answer. Southern Copper stock Q3 2026 is a story of metal prices. Sales for the three months to 30 September 2026 rose 39.1% to $4,696.6m, which the company called "a new quarterly record", because London Metal Exchange copper averaged $6.41 a pound, 44.4% more than a year earlier, and silver, molybdenum and zinc also rose by a third or more. Mined copper output actually fell 1.1%. Operating income rose 59.2% to $2,815.1m and net income rose 62.7% to $1,801.8m, or $2.15 a share. By-product credits pushed the cash cost of copper down to just $0.09 a pound. Chief financial officer Raul Jacob said the company "hit record highs for net sales, adjusted EBITDA and net income for the second consecutive quarter". Our discounted cash flow model values Southern Copper at $49.81 a share, far below the $179.36 close on 2 November 2026. We assume copper, silver and molybdenum prices fall back from their 2026 peaks, margins return to the company's own mid-cycle level, and Peru and Mexico carry a higher cost of capital.
Key takeaways
- Sales up 39.1%. Third-quarter sales were $4,696.6m, against $3,377.3m a year earlier. LME copper averaged $6.41 a pound (+44.4%), silver $62.80 an ounce (+58.7%), molybdenum $32.93 a pound (+35.5%) and zinc $1.74 a pound (+35.9%).
- Volumes slipped. Mined copper was 232,396 tonnes, down 1.1%, and nine-month output fell 2.9%, mainly because Toquepala produced 10.0% less.
- Margins widened. The operating margin rose to 59.9% from 52.4%, and the adjusted EBITDA margin rose to 64.7% from 58.5%.
- Copper almost free to produce after credits. Cash cost net of by-product credits was $0.09 a pound, against $0.42. Before credits it rose 10% to $2.46.
- Cash keeps coming. Operating cash flow was $2,224.3m in the quarter and $5,907.3m in nine months, against capital spending of $1,380.5m. The next dividend is $1.30 a share in cash plus 0.0106 shares.
- Growth is a 2028 story. Tia Maria in Peru, with $884.3m invested by 30 September, is due to start in the first half of 2028. Tia Maria and El Pilar in Mexico should add 156,000 tonnes of copper a year.
- Our value: $49.81 a share, against a $179.36 close on 2 November 2026. Our sensitivity grid runs from $45.39 to $55.99. Holding the operating margin at 59.2% gives $61.92. Analysts' average target is $178.19, and their consensus rating is "Sell".
- What to watch. The copper and silver prices; 2027 production, capital and cost guidance, due on the January call; Tia Maria lawsuits and permits for Los Chancas and Michiquillay in Peru; and talks with Mexico's government over $10.2bn of investment there.
Key numbers from Southern Copper's Q3 2026 earnings
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Net sales | $4,696.6m | $3,377.3m | +39.1% |
| Cost of sales | $1,599.1m | $1,356.8m | +17.9% |
| Operating income | $2,815.1m | $1,768.8m | +59.2% |
| Operating margin | 59.9% | 52.4% | +7.5pt |
| Net income attributable to Southern Copper | $1,801.8m | $1,107.6m | +62.7% |
| Net margin | 38.4% | 32.8% | +5.6pt |
| Earnings per share | $2.15 | $1.32 | +62.9% |
| Adjusted EBITDA | $3,040.2m | $1,975.4m | +53.9% |
| Adjusted EBITDA margin | 64.7% | 58.5% | +6.2pt |
| Operating cash flow | $2,224.3m | $1,559.6m | +42.6% |
| Capital expenditure | $515.8m | $349.2m | +47.7% |
| Cash cost per pound of copper, net of by-product credits | $0.09 | $0.42 | -$0.33 |
| Mined copper | 232,396 t | 234,892 t | -1.1% |
Adjusted EBITDA and operating cash cost are Southern Copper's non-GAAP measures. The cash cost figure deducts revenue from by-products such as molybdenum, silver and zinc from the cost of producing copper.
Southern Copper Q3 2026 earnings: what happened
Southern Copper mines copper in Peru and Mexico and also sells molybdenum, silver and zinc. It is 88.9% owned by Grupo Mexico. The quarter was driven almost entirely by price. Copper made up 74% of third-quarter sales and silver 7%, according to the earnings call.
Sales of $4,696.6m were 39.1% higher than a year earlier and 9.5% higher than in the second quarter. Sales have risen in every quarter since the second quarter of 2025.
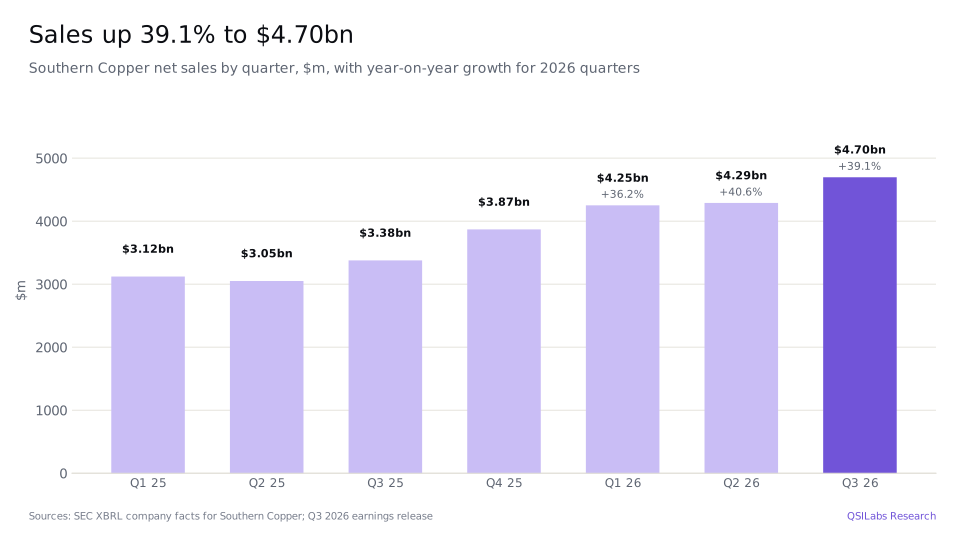
Volumes did not help. Mined copper fell 1.1% to 232,396 tonnes, molybdenum fell 2.2% to 7,702 tonnes, silver fell 1.9% to 6,093,000 ounces and zinc fell 7.9% to 41,880 tonnes. For 2026 the company expects to produce 918,000 tonnes of copper and 29,000 tonnes of molybdenum, 12% more molybdenum than it planned.
Management said on the call: "we estimate now a slight copper market surplus for 2026". Copper stocks in LME, COMEX, Shanghai and bonded warehouses were 1,105,000 tonnes on 9 October, about 14 days of global demand.
- 31 Dec 20252025 ends with sales of $13.42bn, up 17.4%, and net income of $4.33bn; LME copper averaged $4.51 a pound in 2025Form 10-K; 8-K Ex 99.1
- Q1 2026LME copper averages $5.83 a pound and silver $83.33 an ounce8-K Ex 99.1
- 25 Aug 2026SCCO closes at $219.70, its 52-week closing highYahoo Finance
- 30 Sep 2026Q3 2026 ends: sales $4,696.6m; Tia Maria 49.6% complete with $884.3m invested8-K Ex 99.1; earnings call
- 21 Oct 2026Results published; SCCO falls 2.1% to $198.078-K; Yahoo Finance
- 22 Oct 2026Earnings call; SCCO falls 7.3% to $183.59Earnings call; Yahoo Finance
- 30 Oct 2026Form 10-Q filed for the quarterForm 10-Q
- 2 Nov 2026SCCO closes at $179.36, the price used in our valuationYahoo Finance
- 19 Nov 2026Dividend of $1.30 in cash plus 0.0106 shares, to holders of record on 3 NovemberForm 10-Q
- January 20272027 production, capital spending and cost guidance on the fourth-quarter callEarnings call
- 1H 2028Tia Maria due to start operating; El Pilar follows in the second half of 2029Earnings call
Which metals drove Southern Copper sales?
Every metal Southern Copper sells was priced well above its year-earlier level. Copper on the LME averaged $6.41 a pound, against $4.44, and COMEX copper averaged $6.48, against $4.83. Molybdenum rose 35.5% to $32.93 a pound and zinc 35.9% to $1.74 a pound. Silver gained most: up 58.7% to $62.80 an ounce.
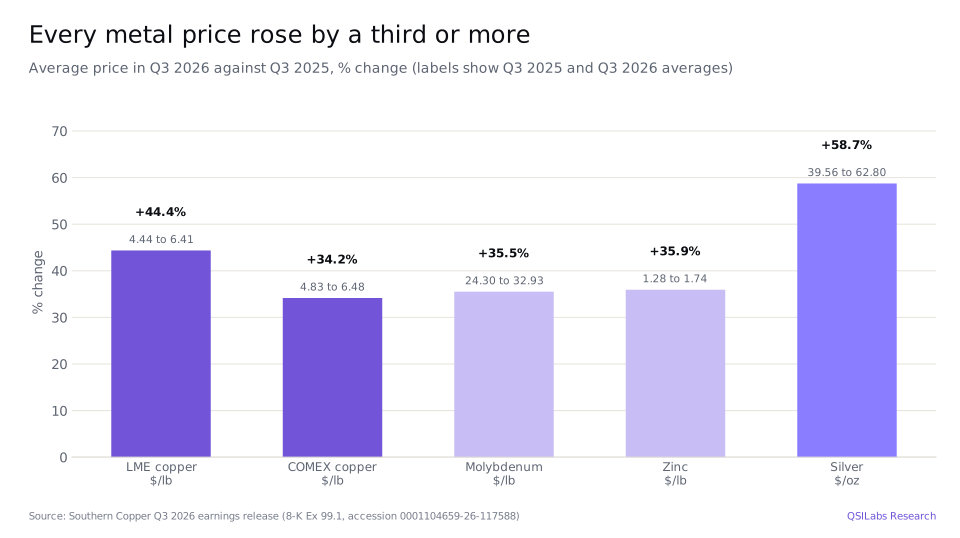
Prices have not all moved the same way during 2026. LME copper rose each quarter, from $5.83 a pound in the first quarter to $6.04 and then $6.41. Silver fell from $83.33 an ounce in the first quarter to $73.49 and then $62.80. Molybdenum rose from $25.37 to $29.44 and then $32.93.
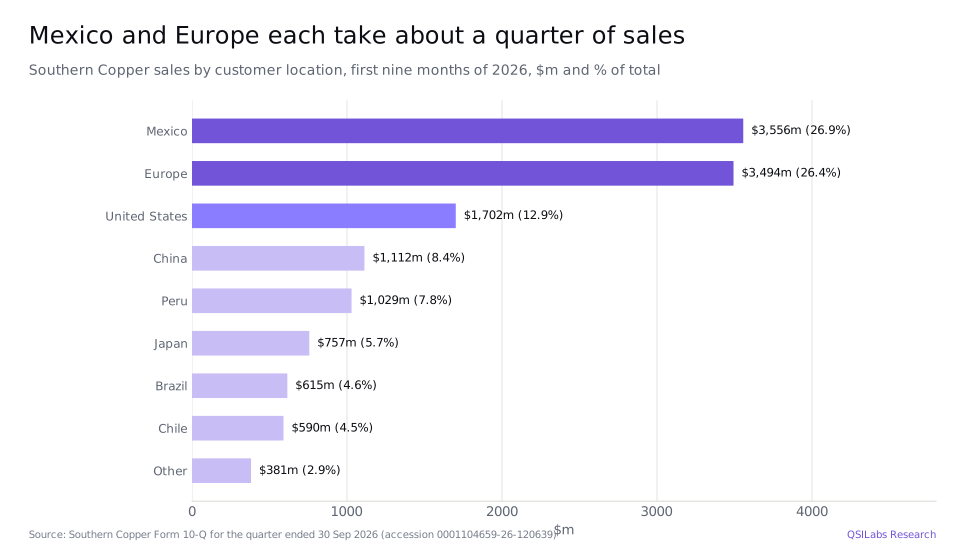
Southern Copper sells worldwide. In the first nine months of 2026, customers in Mexico took 26.9% of sales and customers in Europe 26.4%. The United States took 12.9%, China 8.4% and Peru 7.8%.
How profitable is Southern Copper?
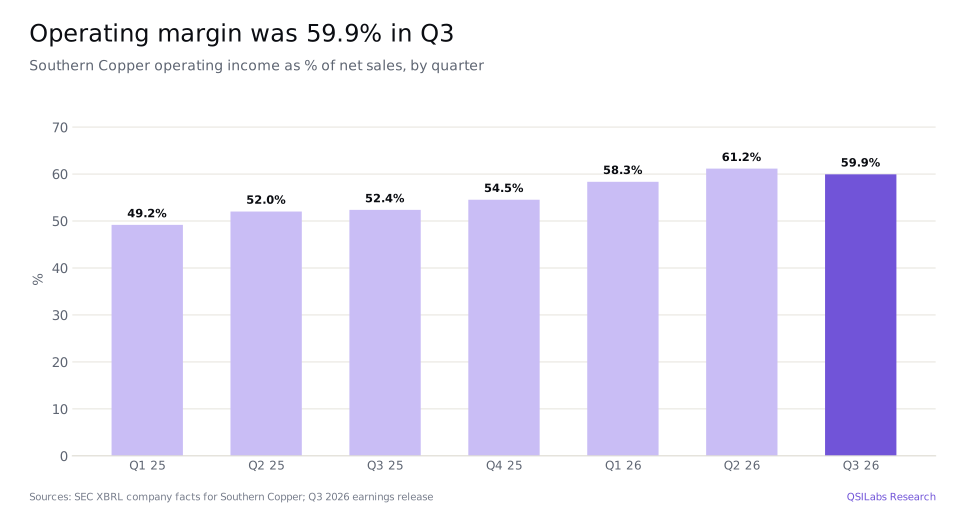
Higher prices fell straight through to profit, because many of a mine's costs do not rise with the metal price. Cost of sales rose 17.9% while sales rose 39.1%. The operating margin was 59.9%, against 52.4% a year earlier. That was a little below the 61.2% of the second quarter, but above any 2025 quarter.
The unit cost before by-product credits rose 10%, or $0.23, to $2.46 a pound. Once revenue from molybdenum, silver and zinc is deducted, the net cash cost fell to $0.09 a pound, against $0.42 a year earlier.
Taxes take a large share. In the first nine months the effective tax rate was 36.1%, including Peru's royalty and special mining tax and Mexico's mining royalty. Net income was 38.4% of sales in the quarter.
What are Southern Copper's growth projects?
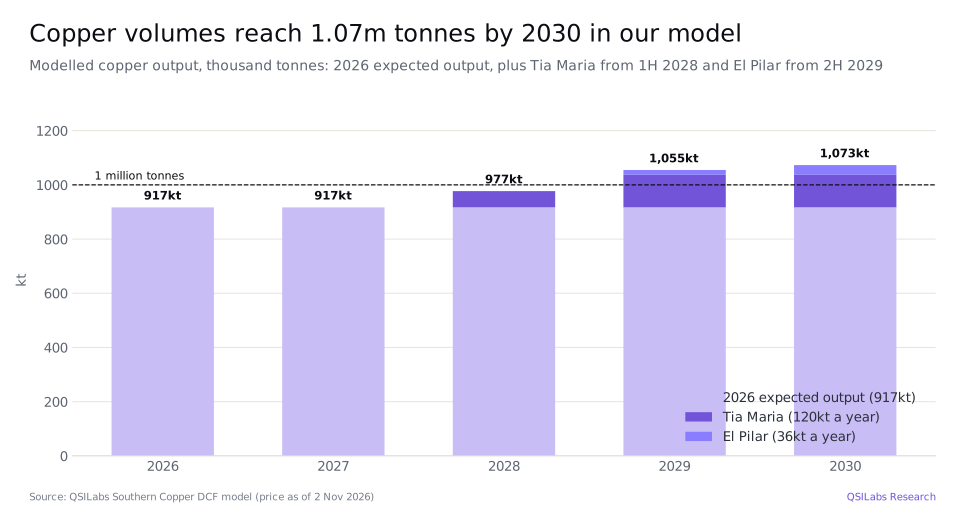
Southern Copper's growth over the next five years depends on two projects. Tia Maria, in Peru, was 49.6% complete at the end of September, with $884.3m invested, and is due to start operating in the first half of 2028. The company expects its construction to create about 7,000 jobs. El Pilar, in Sonora, Mexico, is a $551m project due to produce 36,000 tonnes of copper a year from the second half of 2029. It has proven and probable reserves of 317 million tonnes of ore and an 18-year life of mine. The company expects the two projects to add 156,000 tonnes of refined copper a year. Jacob said "we will widely surpass the annual production mark of 1 million tons".
There are more projects behind these, but none has been approved. Los Chancas in Peru could produce 130,000 tonnes of copper and 7,500 tonnes of molybdenum a year for about $2.6bn from 2031. Jacob said "a little bit north of 200 illegal miners" are on the site. Michiquillay, also in Peru, could produce 225,000 tonnes a year over a 25-year life.
The earnings release says the capital investment programme for this decade "exceeds $15 billion". Peruvian projects could take more than $10.3bn in the next decade. In Mexico, the company is in talks with the government to continue $10.2bn of investment.
The projects carry risk. The 10-Q lists seven lawsuits against Tia Maria, including claims to cancel its environmental approval. We model only Tia Maria and El Pilar. Los Chancas, Michiquillay and the Cuajone expansion would add roughly 410,000 tonnes a year if built, and are not in our numbers.
How does Southern Copper use its cash?
Southern Copper produced $5,907.3m of operating cash flow in the first nine months of 2026, against $3,257.8m a year earlier. Capital spending was $1,380.5m, leaving about $4.5bn. The company also borrowed $1,247.5m in the period, mainly through notes whose proceeds are earmarked for Tia Maria and the Peruvian capital programme.
At 30 September it held $8,062.9m of cash and short-term investments against $7,995.9m of long-term debt and $601.6m of lease liabilities. Net debt, including leases, was about $0.5bn.
Most of the cash goes to shareholders, and so mostly to Grupo Mexico. Cash dividends paid in the third quarter were $1.10 a share. The board has declared $1.30 a share in cash plus 0.0106 shares of common stock for each share held, payable on 19 November 2026 to holders on 3 November. Stock dividends are paid out of treasury shares, which fell from 65.5 million at the end of 2025 to 40.3 million at 30 September 2026. Four quarterly dividends at $1.30 would give a cash yield of 2.9% at $179.36.
How has SCCO stock performed?
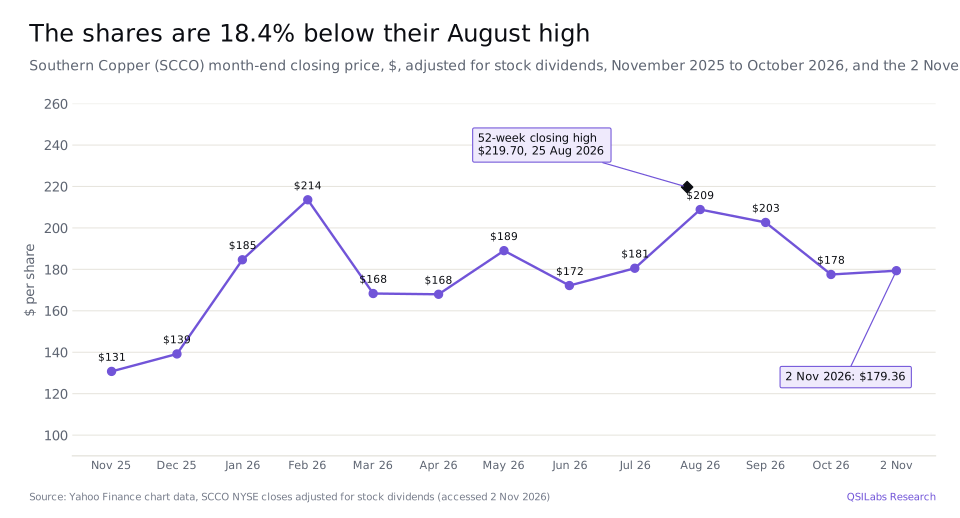
SCCO closed at $179.36 on 2 November 2026. On a basis adjusted for stock dividends, the shares are up 28.9% this year and 34.8% over twelve months. They peaked at a closing high of $219.70 on 25 August 2026 and are now 18.4% below it.
The results did not help the shares. SCCO fell 2.1% to $198.07 on 21 October, when the results were published, and 7.3% to $183.59 on 22 October, the day of the earnings call. At $179.36 it is 11.4% below the $202.34 close of 20 October.
At $179.36 the shares trade at 22.4 times the analysts' average 2026 earnings forecast of $8.01 a share and 23.5 times their 2027 forecast of $7.63. Those analysts expect 2027 sales to fall 3.6% to $16.80bn, after $17.42bn in 2026. Of the 18 analysts S&P Global polls, one rates the stock a strong buy, six a hold, six a sell and five a strong sell. Their average target is $178.19, with a range from $139.43 to $275.
Southern Copper stock Q3 2026: is SCCO overvalued?
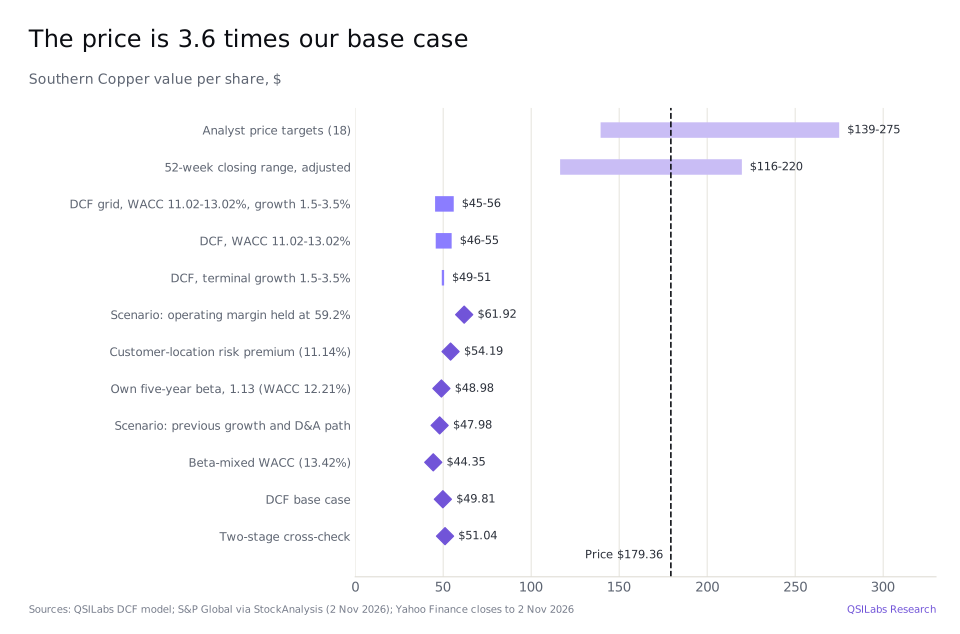
On our assumptions, yes. Our model values Southern Copper at $49.81 a share, 72% below the $179.36 close on 2 November 2026. Our previous value, as of 21 October, was $47.52, when the shares closed at $198.07.
The market capitalisation is about $151bn. Adding debt, leases and minority interests and taking off cash gives an enterprise value of about $152bn, roughly 28 times the unlevered free cash flow of $5.42bn we expect in 2026. Our enterprise value is $42.1bn.
Method
We forecast revenue, operating margin, tax, capital spending, depreciation and working capital year by year from 2026 to 2035, discount the cash flows at the weighted average cost of capital (WACC) and add a terminal value for the years after 2035.
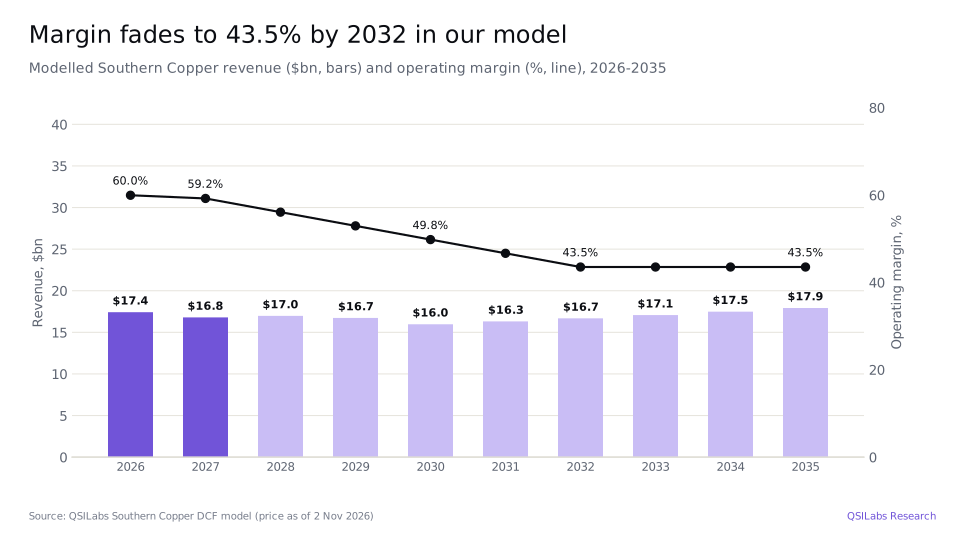
- Revenue. 2026 is $17.42bn and 2027 $16.80bn (-3.6%), the S&P Global consensus. 2028 is $16.98bn (+1.1%), using the 8.16% a year three-year consensus growth rate from 2025. In 2029 and 2030 revenue falls 1.5% and 4.5% as copper eases from $6.00 a pound in 2026-27 to $5.25 by 2030, silver to $27.10 an ounce and molybdenum to $18.06 a pound. Tia Maria and El Pilar volumes partly offset this. Growth is 2.2% in 2031, Wood Mackenzie's forecast for copper demand growth to 2035, fading to 2.5% by 2035.
- Operating margin. 59.2% in 2027, implied by the consensus 2027 earnings forecast. It then fades over five years to 43.5% by 2032, Southern Copper's own average from 2016 to 2025, excluding 2020 and 2021.
- Tax. 36.1%, the effective rate of the first nine months, including mining royalties.
- Capital spending. $1.93bn in 2026, the board's plan, then about 11.1% of revenue, in line with 2026. That is about $16.9bn from 2027 to 2035.
- Depreciation. 5.2% of revenue in 2026, rising with output as the new mines start, to 6.7% from 2030.
- Cost of capital. WACC is 12.02%. The cost of equity is 12.40%: a 5.12% risk-free rate plus a beta of 1.10 times a 6.62% equity risk premium. The beta is the global metals and mining industry beta of 1.055, relevered at Southern Copper's 5.7% debt-to-equity ratio. The risk premium is that of emerging markets, because the mines are in Peru and Mexico. Debt is 5.4% of capital, at an after-tax cost of 5.39%. Southern Copper's own five-year beta is 1.13.
- Bridge to equity. To the enterprise value of $42,076.5m we add cash of $8,062.9m, our $661.6m value of the equity affiliate and the $490.2m of cash generated between 30 September and 2 November. We deduct debt and leases of $8,597.5m, asset retirement obligations of $495.8m, minority interests of $139.4m and $8.0m of interest. That leaves $42,050.5m, or $49.81 for each of 844.3 million shares.
The terminal value is 37.5% of enterprise value and equals 5.0 times 2035 EBITDA. The shares trade at 13.9 times trailing EBITDA.
Four things explain the gap to the share price. First, prices: copper at $5.25 by 2030 is 18% below the third-quarter average of $6.41, and silver at $27.10 is less than half of $62.80. Second, the margin returns from almost 60% to its 43.5% average. Third, the 12.02% cost of capital reflects Peru and Mexico. Fourth, we include only the two sanctioned projects. To reach the share price, copper would have to stay near today's level, margins would have to hold near 60% and much of the pipeline would have to be built. Even holding the margin at 59.2% only lifts our value to $61.92.
How the number moves if you argue with us
Value per share at different WACCs (rows) and terminal growth rates (columns):
| WACC | 1.5% | 2.0% | 2.5% | 3.0% | 3.5% |
|---|---|---|---|---|---|
| 11.02% | $53.82 | $54.29 | $54.80 | $55.36 | $55.99 |
| 11.52% | $51.40 | $51.76 | $52.16 | $52.60 | $53.08 |
| 12.02% | $49.20 | $49.49 | $49.81 | $50.14 | $50.52 |
| 12.52% | $47.21 | $47.44 | $47.68 | $47.94 | $48.22 |
| 13.02% | $45.39 | $45.57 | $45.75 | $45.95 | $46.17 |
Terminal growth matters little because the forecast cash flows to 2035 carry most of the value.
| Scenario | Value per share | vs base |
|---|---|---|
| Operating margin held at 59.2% | $61.92 | +$12.11 |
| Equity risk premium weighted by customer location (WACC 11.14%) | $54.19 | +$4.38 |
| Two-stage cross-check | $51.04 | +$1.23 |
| Base case | $49.81 | - |
| Southern Copper's own five-year beta of 1.13 (WACC 12.21%) | $48.98 | -$0.83 |
| Previous growth and depreciation path (no growth after 2030; depreciation rising to 8.5% of revenue) | $47.98 | -$1.83 |
| Beta-mixed regional cost of capital (13.42%) | $44.35 | -$5.46 |
Weighting the risk premium by where customers are, rather than where the mines are, cuts WACC to 11.14% because more than a quarter of sales go to Europe and an eighth to the United States. Even so, the value rises only to $54.19.
Risks to the Southern Copper investment case
- Metal prices. Copper is three-quarters of sales. A lasting move in copper, silver or molybdenum moves profit far more than any cost saving can. The company itself expects a small copper surplus in 2026.
- Peru. Tia Maria faces seven lawsuits, and Los Chancas has illegal miners on site. Delays would push out the volume growth the shares are pricing.
- Mexico. The company is still in talks with the government over $10.2bn of planned investment.
- Control. Grupo Mexico owns 88.9%, so it decides dividends, capital spending and governance. Other investors hold only 11.1%.
- Output. Nine-month copper output fell 2.9%, and Toquepala produced 10.0% less. 2027 guidance is not due until January.
- Upside risk. If copper stays above $6 a pound and the pipeline is built, our value is too low. Wood Mackenzie expects copper demand to grow 24% by 2035.
FAQ
What value does QSILabs put on Southern Copper stock?
QSILabs values Southern Copper (NYSE: SCCO) at $49.81 a share, from a discounted cash flow model using a 12.02% WACC and 2.5% terminal growth. That compares with a share price of $179.36 on 2 November 2026. Our sensitivity grid runs from $45.39 to $55.99.
Is Southern Copper a buy after its third-quarter results?
This article is not investment advice. On our assumptions, which bring metal prices and margins back towards mid-cycle levels, the shares look expensive. Analysts are also cautious: 11 of the 18 polled by S&P Global rate the stock a sell or strong sell, and their average target of $178.19 is close to the price.
How much did Southern Copper earn in the September 2026 quarter?
Net income attributable to Southern Copper was $1,801.8m, or $2.15 a share, up 62.7% from $1,107.6m. Sales were $4,696.6m and operating income $2,815.1m.
What did it cost Southern Copper to produce a pound of copper?
Cash cost net of by-product credits was $0.09 a pound in Q3 2026, down from $0.42. Before by-product credits it was $2.46 a pound, up 10%.
When will Tia Maria start producing copper?
Southern Copper expects Tia Maria to start operating in the first half of 2028. It had invested $884.3m in the project by 30 September 2026, when it was 49.6% complete. With El Pilar in Mexico, it should add 156,000 tonnes of copper a year.
What dividend does SCCO pay?
The next dividend is $1.30 a share in cash plus 0.0106 shares of stock for each share held, payable on 19 November 2026 to holders of record on 3 November. Four payments at $1.30 would give a 2.9% cash yield at $179.36.
What price target do analysts give Southern Copper?
The average target of the 18 analysts polled by S&P Global is $178.19, with a median of $174, a low of $139.43 and a high of $275. The consensus rating is "Sell".
Why is the QSILabs value so far below the SCCO share price?
We assume copper eases to $5.25 a pound by 2030, silver falls to $27.10 an ounce and the operating margin returns from 59% to 43.5%. We also discount at 12.02% for Peru and Mexico risk and count only Tia Maria and El Pilar. The share price assumes high prices, high margins and more growth for longer.
Who controls Southern Copper?
Grupo Mexico owns 88.9% of Southern Copper through its subsidiary Americas Mining Corporation.
How sensitive is Southern Copper to the copper price?
Very. Copper was 74% of Q3 2026 sales. LME copper averaged 44.4% more than a year earlier, and sales rose 39.1% even though mined copper fell 1.1%.
Sources
- Southern Copper Corporation, third quarter 2026 earnings release (Form 8-K, Exhibit 99.1, filed 21 Oct 2026; accession 0001104659-26-117588) www.sec.gov
- Southern Copper Corporation, Form 10-Q for the quarter ended 30 Sep 2026 (filed 30 Oct 2026; accession 0001104659-26-120639) www.sec.gov
- Southern Copper Corporation, Form 10-Q for the quarter ended 30 Jun 2026 (accession 0001104659-26-089169): sales by metal and 2026 production plan www.sec.gov
- Southern Copper Corporation, Form 10-K for 2025 (accession 0001104659-26-021492) www.sec.gov
- SEC XBRL company facts for Southern Copper (CIK 1001838): quarterly sales and operating income, 2025-2026 data.sec.gov
- Southern Copper Q3 2026 earnings call transcript, 22 Oct 2026, via The Motley Fool (accessed 2 Nov 2026) www.fool.com
- StockAnalysis: Southern Copper forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: Southern Copper statistics (accessed 2 Nov 2026) stockanalysis.com
- Wood Mackenzie, "Copper demand set to surge 24% by 2035", press release, 15 Oct 2025 www.woodmac.com
- Yahoo Finance chart data: SCCO closing prices, dividends and stock-dividend adjustments (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: global industry betas, costs of capital and country equity risk premiums, January 2026 pages.stern.nyu.edu
- QSILabs Southern Copper discounted cash flow model (internal; price as of 2 Nov 2026)
Disclaimer
This article is for information only and is not investment advice or a recommendation to buy or sell any security. QSILabs values are model estimates that depend on assumptions which may prove wrong. Figures are from the sources listed, which we believe to be reliable but have not audited. Do your own research before investing.
More from QSI Labs
Related analysis: Caterpillar stock Q3 2026: power generation and backlog, Linde stock Q3 2026: electronics and Lincare, GE Vernova stock Q3 2026: backlog and gas power and ExxonMobil stock Q3 2026: refining and buybacks.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.