Research / Earnings and valuation
Costco Stock Q3 2026:A $303bn Year, 9.4% Comps and 84 Million Members
As of: Figures are as of Costco Wholesale's fiscal fourth-quarter 2026 results (16 weeks ended 30 August 2026, reported 24 September 2026 in a Form 8-K) and its fiscal 2026 Form 10-K (filed 7 October 2026). Costco's fiscal fourth quarter is the company's report for the summer of 2026, so we file it with our Q3 2026 earnings coverage. The share price is the Nasdaq close of COST on 30 October 2026, $1,012.28. Published 2 November 2026.
The short answer. Costco stock Q3 2026 coverage means Costco's fiscal fourth quarter, the 16 weeks to 30 August 2026, which closed a record year. Quarterly revenue rose 11.1% to $95.7bn, comparable sales rose 9.4% (6.7% excluding gasoline prices and currency) and diluted EPS rose 15% to $6.75. For the full year, revenue passed $303bn, membership fees rose 11% to $5.91bn and paid members reached 84.1 million. Our discounted cash flow model, updated for the results, puts Costco at $398.40 a share, against a $1,012.28 close on 30 October 2026. The business is one of the steadiest in retail; the share price assumes it compounds for far longer, and at far better economics, than we do.
Key takeaways
- Revenue up 11.1%. Fiscal Q4 2026 total revenue was $95,723m, up from $86,156m. Net sales rose 11.2% to $93,873m and membership fees rose 7.3% to $1,850m.
- Comparable sales accelerated. Total comparable sales rose 9.4%, or 6.7% excluding gasoline prices and foreign exchange. US comparable sales rose 10.7% (7.2% adjusted) and digitally-enabled sales rose 19.5%.
- Earnings up 15%. Net income was $2,998m and diluted EPS $6.75, up from $2,610m and $5.87. Excluding a $0.15 a share benefit from tariff refunds, EPS was $6.60, up 12.4%.
- A record year. Fiscal 2026 revenue was $303,154m (+10.1%), operating income $11,685m (+12.5%), net income $9,226m (+13.9%) and diluted EPS $20.76 (+14.0%).
- Members keep renewing. Paid members rose 3.8% to 84.1 million, executive members rose to 42.3 million and the renewal rate was 92.3% in the US and Canada and 89.8% worldwide.
- More warehouses, more capex. Costco ended the year with 939 warehouses and plans up to 33 openings in fiscal 2027, including five relocations. Capital spending is planned at about $7.5bn, up from $6.4bn.
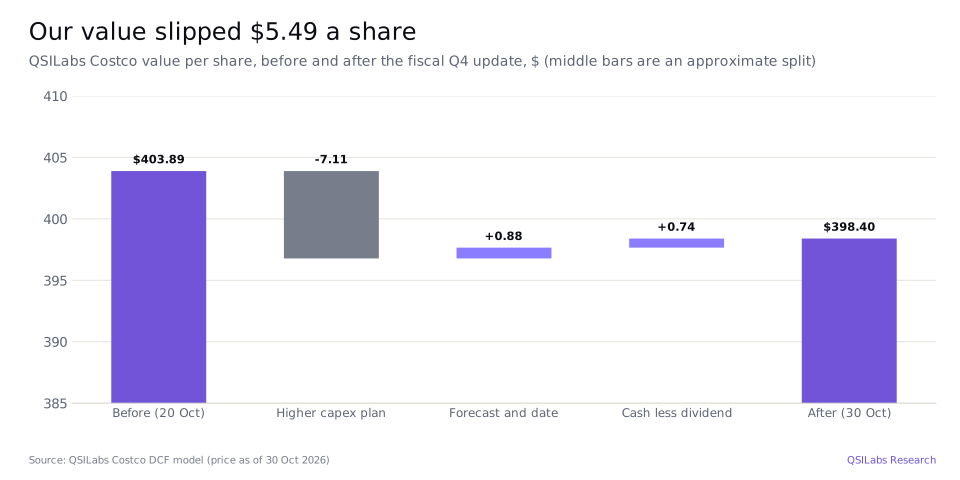
- Our value: $398.40 a share, down $5.49 from $403.89, and about 61% below the $1,012.28 close on 30 October. A two-stage cross-check gives $397.55; analysts' average target is $1,068.
Key numbers from Costco's Q3 2026 earnings
| Metric | Fiscal Q4 2026 (16 weeks) | Fiscal Q4 2025 | Change |
|---|---|---|---|
| Net sales | $93,873m | $84,432m | +11.2% |
| Membership fees | $1,850m | $1,724m | +7.3% |
| Total revenue | $95,723m | $86,156m | +11.1% |
| Operating income | $3,801m | $3,341m | +13.8% |
| Operating margin | 3.97% | 3.88% | +9bp |
| Net income | $2,998m | $2,610m | +14.9% |
| Diluted EPS | $6.75 | $5.87 | +15.0% |
| Total comparable sales | +9.4% | ||
| Comparable sales ex gas and FX | +6.7% | ||
| Gross margin (% of net sales) | 11.02% | 11.13% | -11bp |
| SG&A (% of net sales) | 8.94% | 8.67% | +27bp |
| Paid members (year-end) | 84.1m | 81.0m | +3.8% |
| Warehouses (year-end) | 939 | 914 | +25 |
Costco Q3 2026 earnings: what happened in fiscal Q4
Costco reported its fiscal fourth quarter and full year on 24 September 2026. Its fiscal year ends on the Sunday nearest the end of August, and the fourth quarter is 16 weeks long rather than 12, so the quarter ran from 11 May to 30 August 2026. That makes it the company's report for the summer of 2026 and the closest match to a calendar third quarter, which is why we cover it as Costco's Q3 2026 earnings.
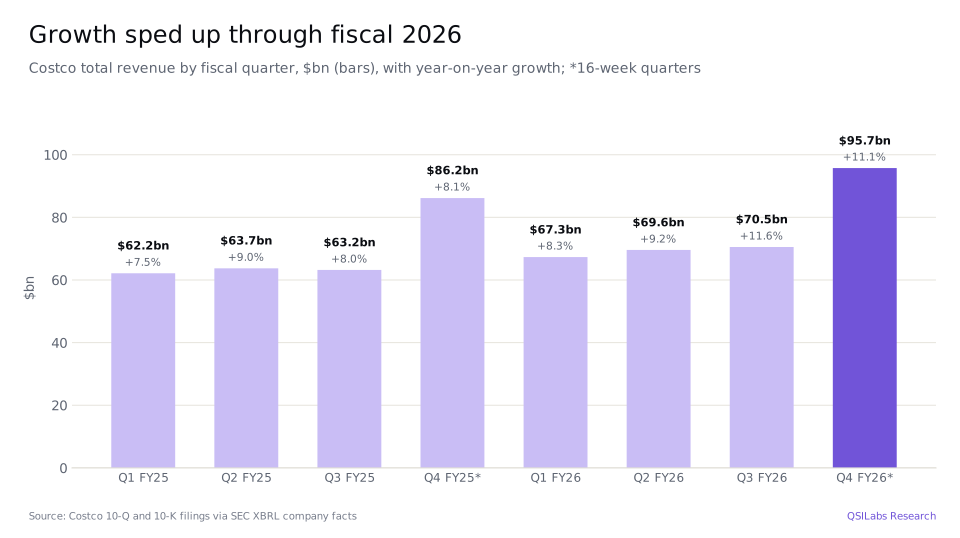
The quarter was the strongest of the year. Total revenue rose 11.1%, the second quarter in a row of double-digit growth, after 8.3% in fiscal Q1 and 9.2% in fiscal Q2. Part of the lift came from gasoline: higher pump prices raised reported sales, which is why Costco also gives comparable sales excluding gas and currency. On that basis comparable sales rose 6.7%, still a healthy number for a retailer with more than $300bn of sales.
- 11 May 2026Fiscal fourth quarter begins (16 weeks)Form 10-K
- 30 Aug 2026Fiscal 2026 ends: revenue $303.2bn, 939 warehouses, 84.1 million paid membersForm 10-K
- 24 Sep 2026Fiscal Q4 results: revenue $95.7bn (+11.1%), net income $2.998bn, diluted EPS $6.758-K Ex 99.1
- 7 Oct 2026Form 10-K filed; plans up to 33 openings and about $7.5bn of capital spending in fiscal 2027Form 10-K
- 14 Oct 2026Quarterly dividend of $1.47 declared, payable 13 November to holders of record on 30 October8-K Ex 99.1 (14 Oct)
- 30 Oct 2026COST closes at $1,012.28 on Nasdaq, the price used in our valuationYahoo Finance
- 2 Nov 2026COST closes at $1,040.55Yahoo Finance
Net income rose 14.9% to $2,998m. That figure includes a one-off benefit. Costco paid about $500m of tariffs imposed under the International Emergency Economic Powers Act before the Supreme Court ruled them unlawful in February 2026. It received $184m of refunds during fiscal 2026 (most of it credited to merchandise costs) and a further $155m after the year ended, and says it is reinvesting most of the money in lower prices. Costco puts the benefit at $0.15 a share in the quarter; excluding it, net income rose 12.3% and EPS 12.4%.
How fast are Costco's comparable sales growing?
Fast, and broadly. Total comparable sales rose 9.4% in the fiscal fourth quarter, or 6.7% excluding the effects of gasoline prices and foreign exchange. Costco reports these numbers because gas is a large and volatile part of its sales: its 774 gas stations generated about 11% of fiscal 2026 net sales, and higher fuel prices added $3.5bn, or 130 basis points, to the year's sales growth.
The United States led. US comparable sales rose 10.7%, or 7.2% adjusted. Canada rose 5.0% (4.6% adjusted) and Other International 7.0% (6.2% adjusted). Shopper traffic rose 3.3% worldwide and the average ticket 5.9%, or 3.3% after gas and currency, so growth came from both more visits and bigger baskets.
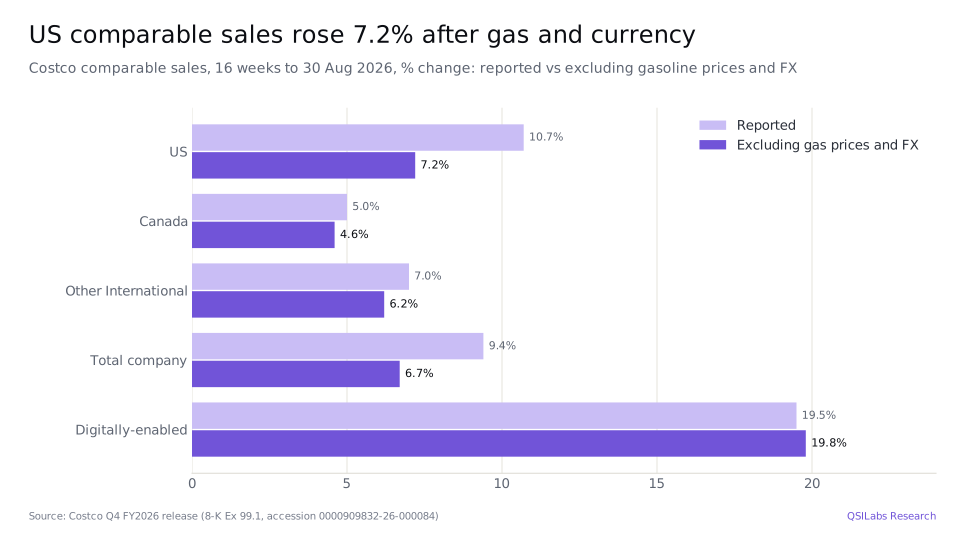
Digital keeps gaining share. Digitally-enabled comparable sales rose 19.5% in the quarter (19.8% adjusted) and made up about 11% of fiscal 2026 net sales. Over the full year, comparable sales rose $22.5bn, or 8%, with the average ticket up about 5% and shopping frequency up about 3%. Warehouse ancillary businesses (gasoline, pharmacy, food court, optical, hearing aids and tire installation) grew 20% to $61.4bn of sales.
How much does Costco make from membership fees?
Costco earned $5,907m in membership fees in fiscal 2026, up 11% from $5,323m. That is about half of its $11,685m of operating income, and it is the core of the business model: Costco prices goods close to cost and makes much of its profit from the annual fee.
Two things drove fee growth. First, the increase in annual fees in the US and Canada that took effect on 1 September 2024, which lifted the basic US fee to $65, is still flowing through because fees are recognised over each one-year membership; Costco says it accounted for about 30% of the growth in fiscal 2026 membership income, down from about 40% in fiscal 2025. Second, the membership base keeps growing and trading up.
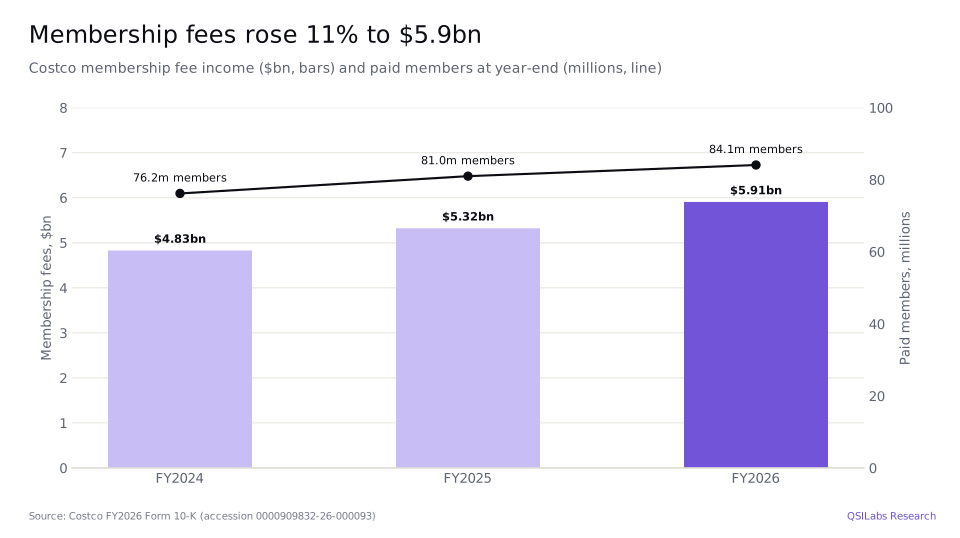
At year-end Costco had 84.1 million paid members, up 3.8%, and 150.4 million cardholders. Executive members, who pay the higher fee and earn a reward on purchases, rose 9.3% to 42.3 million, half of all paid members, and account for about three-quarters of worldwide sales. The renewal rate was 92.3% in the US and Canada and 89.8% worldwide. Fourth-quarter fee growth of 7.3% was slower than the full year's 11% because the September 2024 increase is now almost fully in the base; future fee growth will lean more on new members and upgrades until the next price rise.
Is Costco's operating margin improving?
Yes, slowly. Operating income rose 12.5% to $11,685m in fiscal 2026, faster than revenue, and operating margin rose to 3.85% of total revenue from 3.77% in fiscal 2025 and 3.35% in fiscal 2023. In the fourth quarter it was 3.97%, against 3.88% a year earlier.
The margin is thin by design. Gross margin was 11.09% of net sales in fiscal 2026, almost flat on 11.12%, and 11.22% excluding gasoline. In the fourth quarter, reported gross margin fell 11 basis points to 11.02% but rose 20 basis points excluding gas, helped by the tariff refunds. SG&A rose 27 basis points to 8.94% of sales, or just 2 basis points excluding gas, as wage increases and new warehouses offset scale benefits.
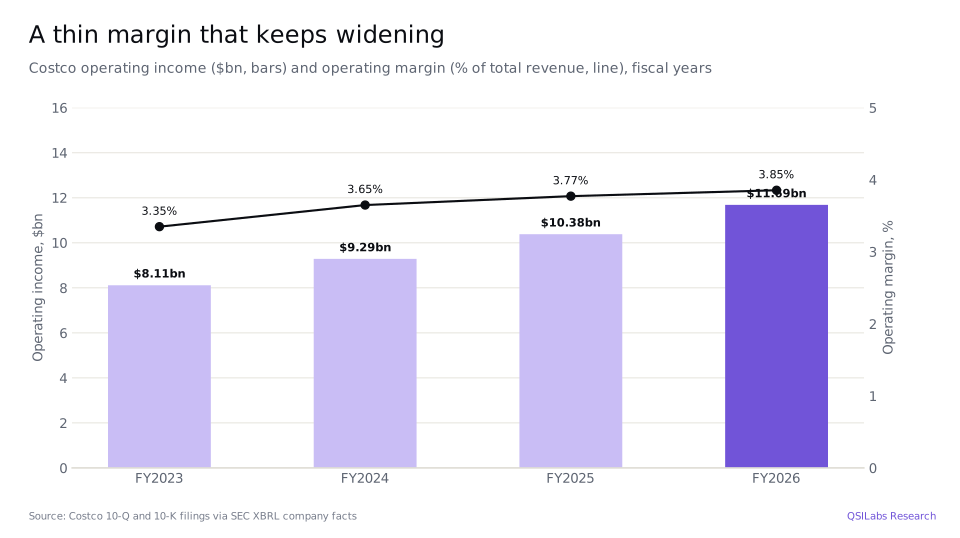
Because the margin is so thin, small moves matter. A 10 basis point change in operating margin on $303bn of revenue is about $300m of operating income, roughly 2.6% of the total. That is why we treat the fiscal 2027 margin, and the extent to which tariff refunds are passed back to members, as one of the key judgement calls in our model.
Where does Costco make its money?
Mostly in the United States, though the best margins are abroad. The US segment produced $219.8bn of total revenue in fiscal 2026, 72.5% of the company, and $7.65bn of operating income, a 3.5% margin. Canada produced $40.6bn of revenue and $2.11bn of operating income, a 5.2% margin, and Other International, which includes Mexico, Japan, the UK, Korea, Taiwan, Australia, Spain, France, Iceland, New Zealand, Sweden and China, produced $42.8bn and $1.93bn, a 4.5% margin.
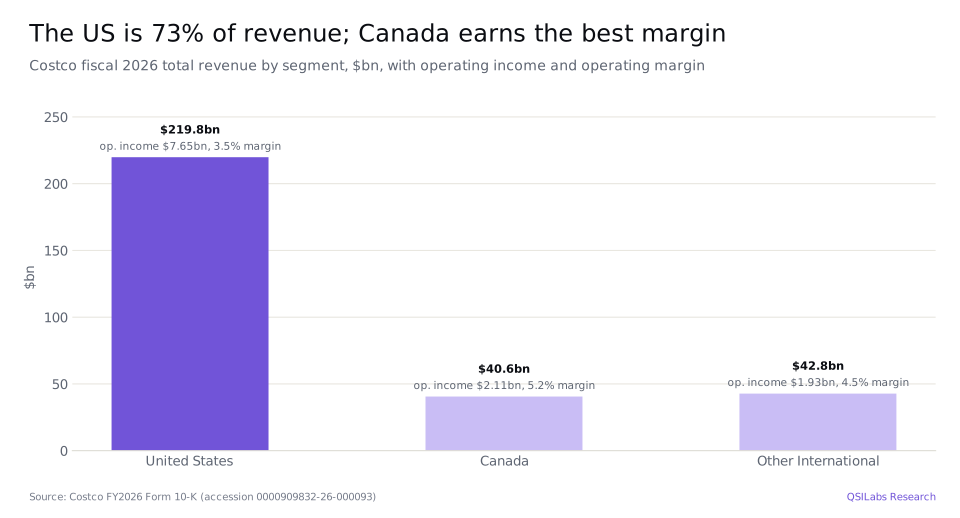
All three segments grew operating income faster than revenue. US operating income rose 11.2% on revenue growth of 9.9%; Canada rose 14.0% on 9.9%; and Other International rose 16.6% on 11.8%. Adjusted for gas and currency, comparable sales rose about 7% in the US and Canada and about 6% in Other International.
How much is Costco spending on new warehouses?
More than ever. Capital spending rose to $6,435m in fiscal 2026 from $5,498m, and Costco expects about $7.5bn in fiscal 2027, mainly for land, buildings and equipment for new and remodeled warehouses, information systems, and manufacturing and distribution facilities. At consensus revenue that is about 2.3% of sales, against 1.8% in fiscal 2023.
Costco opened 28 warehouses in fiscal 2026, including three relocations, and ended the year with 939: 647 in the US and Puerto Rico, 115 in Canada and 177 elsewhere, with 138.7 million square feet of floor space and about 355,000 employees. It plans up to 33 openings in fiscal 2027, including five relocations, which would take it to about 967.
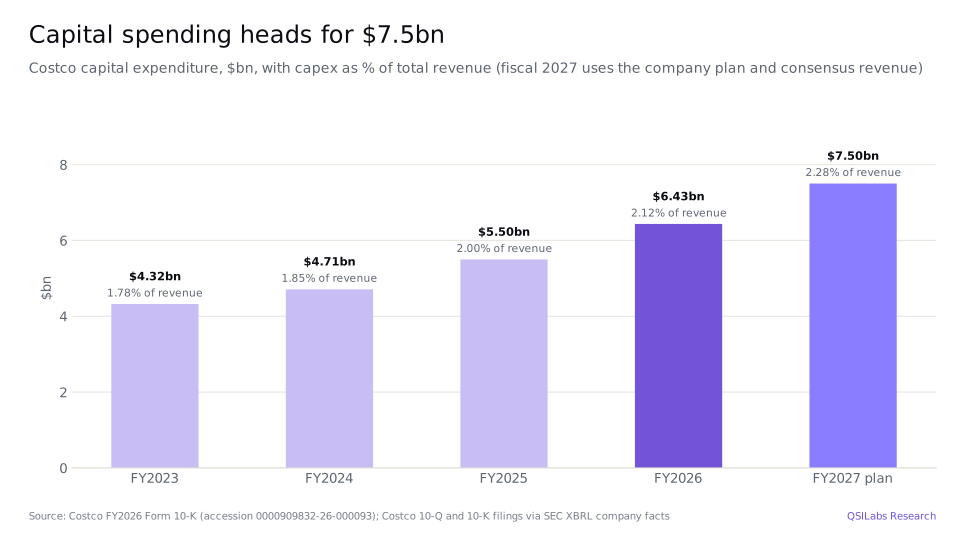
The business pays for this comfortably. Operating cash flow was $15,825m in fiscal 2026, so free cash flow after capital spending was about $9.4bn, up from $7.8bn. Costco returned $2,458m in dividends and bought back $848m of stock, and still ended the year with $21.3bn of cash and short-term investments against $6.2bn of debt. The quarterly dividend is $1.47 a share, raised 13% in April; at the 30 October price that is a yield of about 0.6%.
Costco stock Q3 2026: is COST overvalued?
On our numbers, yes, by a wide margin. Our discounted cash flow model values Costco at $398.40 a share, against a $1,012.28 close on 30 October 2026. At that price Costco's equity was worth about $449bn and its enterprise value, after about $13.7bn of net cash, about $435bn. That is about 49 times fiscal 2026 diluted EPS of $20.76, 44 times the analyst consensus of $22.82 for fiscal 2027 and about 30 times fiscal 2026 operating income plus depreciation.
The shares closed at $1,040.55 on 2 November, within a 52-week range of $844.06 to $1,096.50.
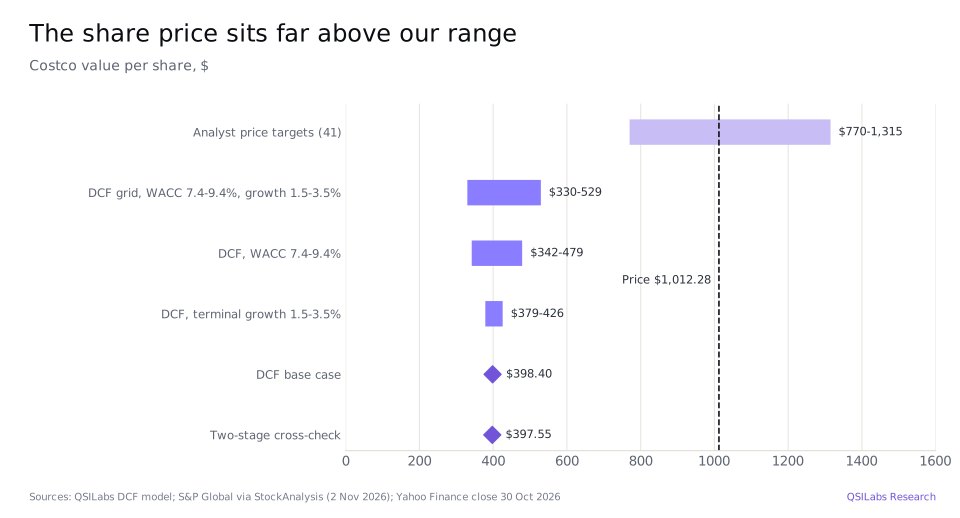
We are not saying the business is weak. Costco is growing revenue at about 10% with renewal rates above 90%, rising margins and a fortress balance sheet. We are saying a price near 50 times earnings already assumes that growth stays high for many more years than a retailer of this size can usually sustain, and that its economics on new investment stay exceptional for decades. Our enterprise value of $163.0bn is a little over a third of the market's.
Analysts are more optimistic. Of the 41 covering the stock tracked by StockAnalysis, the consensus rating is Buy, with an average price target of $1,068, a median of $1,065 and a range from $770 to $1,315. Recent targets include Morgan Stanley at $1,130 and RBC Capital at $1,000, with a Hold rating.
Method
We forecast total revenue and operating margin year by year, apply a 25% tax rate, capital spending and working capital, and discount the cash flows at an 8.4% weighted average cost of capital. The cost of capital comes from Damodaran's January 2026 data for US general retailers: a beta of 0.81 and a cost of equity of 8.7%. After fiscal 2036 we assume growth of 2.5% a year and a 15% return on new investment; that terminal value is 63% of our enterprise value.
For fiscal 2027 we use the analyst consensus: revenue of $329.5bn (+8.7%) and operating income of $12.97bn, a 3.94% margin. For fiscal 2028 we assume growth of 7.4%, in line with consensus, and a 4.1% margin, which we hold flat. Growth then slows by about half a point a year, to 6% in fiscal 2030 and 3% in fiscal 2036, when revenue reaches $513bn. Capital spending follows the company's $7.5bn plan in fiscal 2027 and then eases as a share of revenue, from about 2.3% to 1.4%.
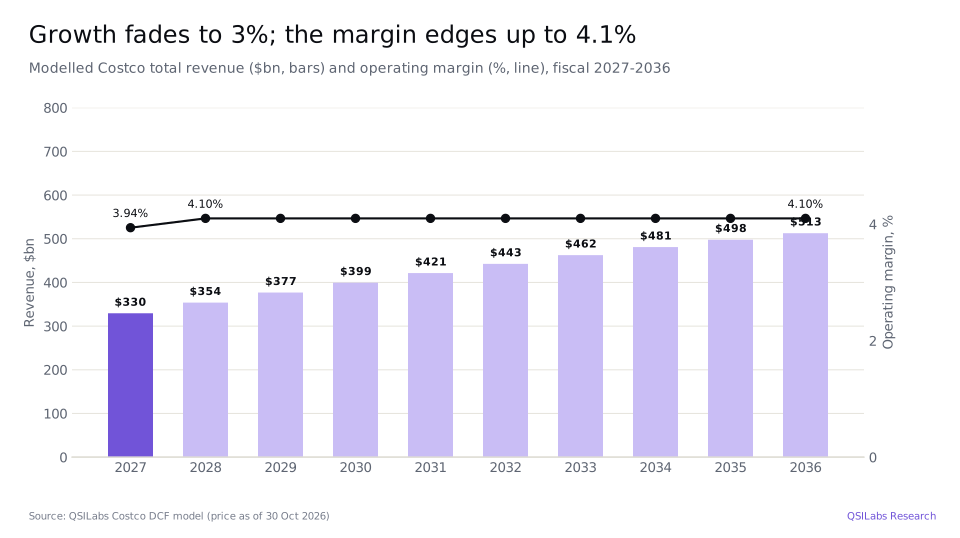
Our value fell $5.49 a share in this update. Putting fiscal 2027 capital spending on the company's $7.5bn plan, and lifting the path that follows, took away about $7.11. Rolling the valuation date forward and refreshing the consensus forecast added about $0.88. Cash generated between the 30 August balance sheet and the 30 October valuation date, net of the $1.47 dividend that went ex on 30 October, added about $0.74.
How the number moves if you argue with us
The table shows our value per share at different costs of capital and terminal growth rates. Even at a 7.4% cost of capital and 3.5% terminal growth, the model reaches $529.28, about half the share price.
| Cost of capital | Growth 1.5% | Growth 2.0% | Growth 2.5% | Growth 3.0% | Growth 3.5% |
|---|---|---|---|---|---|
| 7.4% | $444.59 | $460.06 | $478.56 | $501.11 | $529.28 |
| 7.9% | $408.99 | $420.81 | $434.71 | $451.33 | $471.59 |
| 8.4% | $378.68 | $387.81 | $398.40 | $410.84 | $425.70 |
| 8.9% | $352.59 | $359.70 | $367.83 | $377.26 | $388.33 |
| 9.4% | $329.90 | $335.47 | $341.78 | $348.99 | $357.33 |
The bigger levers are margin and the length of the growth runway. Our terminal value implies about 8.9 times terminal-year operating income plus depreciation, against roughly 30 times today. To reach the share price, Costco would need to keep growing revenue near 8% for well over a decade, earn an operating margin well above 4.1%, or keep earning very high returns on each new warehouse long after it matures, or some combination of the three.
What are the biggest risks for Costco stock?
- Valuation risk. At about 49 times trailing earnings, the shares price in years of steady growth with no stumbles. A slowdown in comparable sales or a weaker renewal rate could lead to a sharp fall in the multiple, even if earnings keep rising.
- Slower fee growth. The September 2024 fee increase is almost fully in the base. Until the next increase, membership income growth depends on adding members and moving them to Executive, and fourth-quarter fee growth has already slowed to 7.3%.
- Thin margins. Operating margin is under 4%. Wage increases, higher freight costs, tariffs or a decision to reinvest more in prices can move earnings quickly. Costco is passing most tariff refunds back to members, so the recent benefit should not recur.
- Gas and currency. Gasoline is about 11% of net sales and makes reported growth swing with oil prices. A stronger dollar would also cut reported international sales and profit.
- Execution on expansion. Capital spending of about $7.5bn and up to 33 openings in fiscal 2027 raise the stakes on new markets such as China, Sweden and new US regions, where returns may take longer to build.
- Upside risk. If digital and ancillary sales keep growing near 20%, the Executive mix keeps rising and margins climb towards 4.5%, earnings would grow faster than our forecast and our value would rise.
FAQ
What is Costco stock worth after its Q3 2026 earnings?
QSILabs values Costco at $398.40 a share, based on a discounted cash flow model updated for the fiscal fourth-quarter 2026 results. That is about 61% below the $1,012.28 close on 30 October 2026. A two-stage cross-check gives $397.55; analysts' average price target is $1,068.
Is Costco stock a buy after Q3 2026?
Our model says COST trades well above what its cash flows justify, because the price assumes high growth and exceptional returns for many more years. The business is strong: revenue up 10% in fiscal 2026, renewal rates above 90% and $21.3bn of cash and investments. This is not investment advice.
Why does Q3 2026 for Costco mean its fiscal fourth quarter?
Costco's fiscal year ends on the Sunday nearest the end of August. Its fiscal fourth quarter of 2026 covered the 16 weeks from 11 May to 30 August 2026, the summer quarter, and was reported on 24 September 2026. It is the closest match to a calendar third quarter.
How much revenue did Costco make in its latest quarter?
Costco's fiscal Q4 2026 total revenue was $95,723m, up 11.1% from $86,156m. Net sales were $93,873m and membership fees $1,850m. For the full fiscal year, revenue was $303,154m, up 10.1%.
How much does Costco earn from membership fees?
Costco earned $5,907m in membership fees in fiscal 2026, up 11% from $5,323m, about half of its operating income. It had 84.1 million paid members at 30 August 2026, including 42.3 million executive members, and a 92.3% renewal rate in the US and Canada.
What were Costco's comparable sales in fiscal Q4 2026?
Total comparable sales rose 9.4% in the 16 weeks to 30 August 2026, or 6.7% excluding gasoline prices and foreign exchange. US comparable sales rose 10.7% (7.2% adjusted), Canada 5.0% and Other International 7.0%. Digitally-enabled sales rose 19.5%.
How many warehouses does Costco have?
Costco had 939 warehouses at 30 August 2026: 647 in the US and Puerto Rico, 115 in Canada and 177 in other countries. It plans up to 33 openings in fiscal 2027, including five relocations, which would take it to about 967.
Does Costco pay a dividend?
Yes. Costco pays a quarterly dividend of $1.47 a share, raised 13% in April 2026, a yield of about 0.6% at the 30 October price. The latest dividend is payable on 13 November 2026 to holders of record on 30 October. Costco paid $2,458m of dividends in fiscal 2026.
Sources
- Costco Wholesale Corporation, fiscal Q4 and fiscal 2026 earnings release (Form 8-K, Exhibit 99.1, 24 Sep 2026; accession 0000909832-26-000084) www.sec.gov
- Costco Wholesale Corporation, fiscal Q4 2026 supplemental information (Form 8-K, Exhibit 99.2, 24 Sep 2026) www.sec.gov
- Costco Wholesale Corporation, Form 10-K for the fiscal year ended 30 Aug 2026 (filed 7 Oct 2026; accession 0000909832-26-000093) www.sec.gov
- Costco Wholesale Corporation, quarterly dividend announcement (Form 8-K, Exhibit 99.1, 14 Oct 2026; accession 0000909832-26-000096) www.sec.gov
- SEC XBRL company facts for Costco (CIK 909832): quarterly revenue, operating income and net income from 10-Q and 10-K filings data.sec.gov
- StockAnalysis: Costco forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- Yahoo Finance chart data: COST closing prices (one year to 2 Nov 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry (US), January 2026 pages.stern.nyu.edu
- QSILabs Costco discounted cash flow model (internal; price as of 30 Oct 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Amazon stock Q3 2026, Apple Q3 2026 earnings, Visa stock Q3 2026 and Mastercard stock Q3 2026: services and stablecoins.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.