Research / Earnings and valuation
AT&T Stock Q3 2026:Fiber Net Adds, Wireless Margins and Cash Flow
As of: Figures are as of AT&T Inc.'s third-quarter 2026 results (the quarter ended 30 September 2026, reported 21 October 2026 in a Form 8-K) and its Form 10-Q for that quarter, filed 21 October 2026. AT&T's fiscal year is the calendar year, so its Q3 2026 covers July to September 2026. The share price used in our valuation is the NYSE close of T on 2 November 2026, $21.44; analyst data were accessed on 2 November 2026. Published 2 November 2026.
The short answer. AT&T stock Q3 2026 comes down to a quarter in which home internet grew fast, wireless held up and cash flow stayed on plan. In the three months to 30 September 2026 revenue rose 5.3% to $32.32bn and service revenue 3.8% to $26.30bn. AT&T added 769,000 internet customers, 442,000 of them on fiber and 327,000 on fixed wireless, and 379,000 postpaid phone customers, with postpaid phone churn steady at 0.92%. Adjusted EBITDA rose 5.4% to $12.51bn, a 38.7% margin, and free cash flow was $4.95bn. Operating income fell 33.1% to $4.10bn because of a $2.6bn impairment on the sale of AT&T Mexico and an employee separation charge of about $800m. AT&T raised its 2026 adjusted earnings per share outlook to about $2.40 and lowered its capital spending plan for 2027 and 2028. Our discounted cash flow model values the shares at $52.54, against a $21.44 close on 2 November 2026; that gap rests mostly on a cost of capital pulled down by AT&T's heavy use of debt, so we show below how far it moves when you change it.
Key takeaways
- Home internet is the growth engine. Advanced home internet revenue rose 23.4% to $2,975m. AT&T added 442,000 fiber and 327,000 fixed wireless customers, a quarter AT&T called "a record quarter" for internet net adds.
- Wireless is steady, not booming. AT&T added 379,000 postpaid phone customers, against 405,000 a year earlier, with churn unchanged at 0.92%. Wireless service revenue in the main segment rose 5.0% to $17,764m.
- Profit grew faster than revenue before one-off charges. Adjusted EBITDA rose 5.4% to $12,505m and adjusted earnings per share 20.4% to $0.65. Reported operating income fell to $4,095m after $3,372m of impairment and restructuring charges.
- Cash flow is on plan. Free cash flow was $4,953m, up 1.8%, and $12,129m over nine months. AT&T expects about $6bn in the fourth quarter and still expects $18bn or more for 2026.
- Debt rose with the EchoStar spectrum deal. Net debt reached $149.8bn, 3.13 times adjusted EBITDA, after AT&T paid $22.65bn for EchoStar spectrum licences. AT&T expects to return to about 2.5 times during 2029.
- The portfolio is being reshaped. AT&T agreed to sell AT&T Mexico and to put its Lumen fiber assets and Gigapower into a 50:50 joint venture with Global Infrastructure Partners and CPP Investments.
- QSILabs value: $52.54 a share, against a $21.44 close on 2 November 2026. A two-stage cross-check gives $48.13; analysts' average target is $27.59 and their highest $34.
- What to watch. Fiber and Internet Air additions in the fourth quarter, when AT&T expects higher marketing costs, the pace of copper retirement, the closing of the Mexico sale and the fiber joint venture, and how fast leverage comes down.
Key numbers from AT&T's Q3 2026 earnings
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total revenues | $32,322m | $30,709m | +5.3% |
| Service revenues | $26,301m | $25,336m | +3.8% |
| Equipment revenues | $6,021m | $5,373m | +12.1% |
| Operating income | $4,095m | $6,119m | -33.1% |
| Adjusted operating income | $7,607m | $6,554m | +16.1% |
| Adjusted EBITDA | $12,505m | $11,861m | +5.4% |
| Diluted earnings per share | $0.12 | $1.29 | -90.7% |
| Adjusted earnings per share | $0.65 | $0.54 | +20.4% |
| Internet net additions | 769,000 | 613,000 | +25.4% |
| Postpaid phone net additions | 379,000 | 405,000 | -6.4% |
| Postpaid phone churn | 0.92% | 0.92% | unchanged |
| Net cash from operating activities | $10,519m | $10,152m | +3.6% |
| Free cash flow | $4,953m | $4,865m | +1.8% |
Source: AT&T Q3 2026 earnings release, financial and operational results and investor briefing (Form 8-K, Exhibits 99.1, 99.2 and 99.3).
AT&T Q3 2026 earnings: what happened
AT&T reported third-quarter results on 21 October 2026. Revenue rose 5.3% to $32,322m from $30,709m. Service revenue, the monthly bills for wireless, internet and business connectivity, rose 3.8% to $26,301m, and equipment revenue, mostly phones, rose 12.1% to $6,021m. For the first nine months revenue was $95,386m, up 3.5%.
Reported profit fell sharply. Operating income was $4,095m, down 33.1%, because AT&T booked $3,372m of asset impairment and restructuring charges: a $2.6bn non-cash impairment on the agreed sale of AT&T Mexico and an employee separation charge of about $800m, most of which AT&T expects to pay in cash in 2027. Interest expense rose 16.4% to $1,979m. Net income attributable to common stock was $855m, or $0.12 a diluted share, against $9,278m a year earlier, when AT&T booked a gain on the sale of its DIRECTV stake.
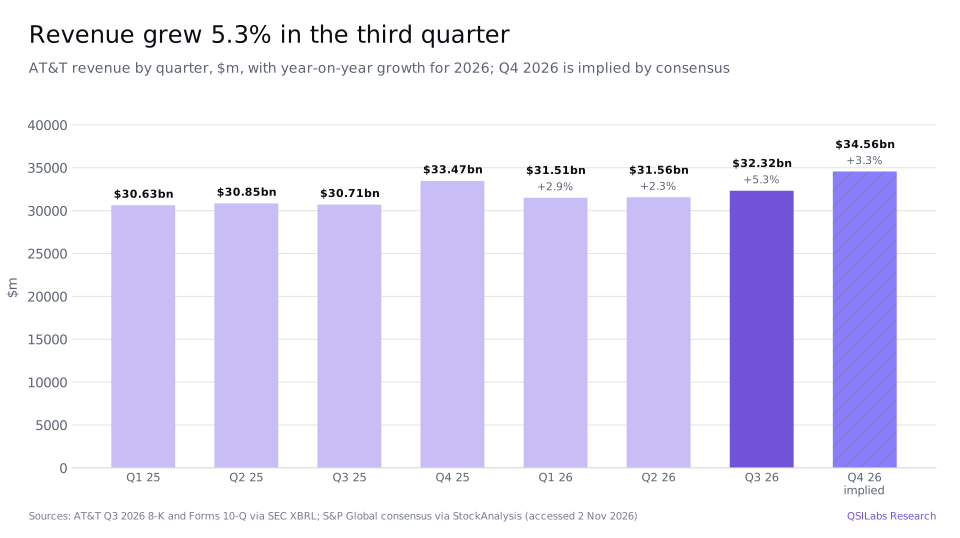
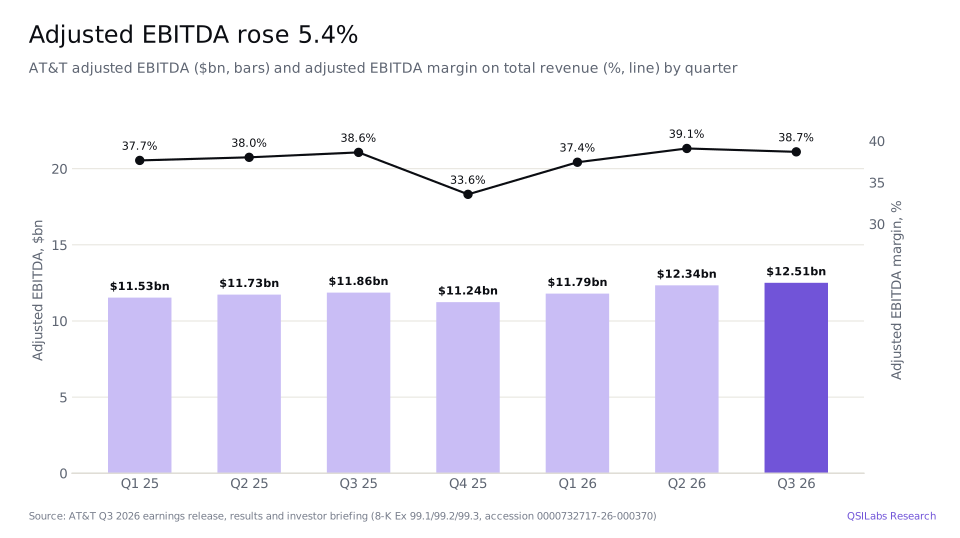
Excluding those items, the quarter was AT&T's strongest of the year. Adjusted EBITDA, operating profit before depreciation, amortisation and special items, rose 5.4% to $12,505m, a margin of 38.7% against 38.6% a year earlier. Chief financial officer Pascal Desroches said it was AT&T's "highest third quarter consolidated adjusted EBITDA margin since we refocused our business on advanced connectivity at the beginning of this decade", and that "we achieved this record despite 12% growth in equipment revenue". Adjusted earnings per share rose 20.4% to $0.65.
Chief executive John Stankey said: "We are growing valuable customer relationships as more homes and businesses choose AT&T for all their advanced connectivity needs across both internet and on-the-go wireless." It was Desroches's final quarterly report as chief financial officer; Stankey said "this will be Pascal's final quarterly report".
- 2 Jul 2025Sale of AT&T's interest in DIRECTV to TPG completedForm 10-Q
- 27 Jan 2026Board approves a further $10bn share buyback authorisationForm 10-Q
- 2 Feb 2026Lumen's mass markets fiber business acquired for $5,756mForm 10-Q
- 27 Mar 2026T closes at $29.10, its 52-week closing highYahoo Finance
- 1 Jul 2026T closes at $20.48, its 52-week closing lowYahoo Finance
- 28 Jul 2026EchoStar 600 MHz and 3.45 GHz spectrum licences acquired for $22,650m, funded partly by $14.5bn of term loansForm 10-Q
- 14 Sep 2026Satellite joint venture agreed with Verizon and T-Mobile to cover wireless dead zonesForm 10-Q
- 6 Oct 2026Agreement to sell 50% of the joint venture holding Forged Fiber and Gigapower to GIP and CPP InvestmentsForm 10-Q
- 13 Oct 2026Agreement to sell the Mexico wireless business for about $2bn in cash at closingForm 10-Q
- 21 Oct 2026Q3 results: 769,000 internet net additions, 2026 adjusted EPS outlook raised to about $2.40; T falls 6.4% to $21.918-K; call; Yahoo
- 2 Nov 2026T closes at $21.44, the price used in our valuationYahoo Finance
- Q1 2027Mexico sale expected to close; the fiber joint venture is expected in the first half of 2027Form 10-Q
- 2029Copper services to end in substantially all wire centres; net debt expected back at about 2.5 times adjusted EBITDA8-K Ex 99.1; Q3 2026 earnings call
How fast is AT&T adding fiber and Internet Air customers?
AT&T sells home and business internet two ways: AT&T Fiber, over its own fiber network, and AT&T Internet Air, fixed wireless broadband delivered over its 5G network. It added 769,000 internet customers in the third quarter, up 25.4% from 613,000: 442,000 on fiber, against 309,000, and 327,000 on fixed wireless, against 304,000. In consumer home internet alone it added 416,000 fiber and 280,000 Internet Air customers. Desroches said "this was a record quarter for combined net adds across these services", helped by wider fiber reach, more mid-band spectrum and "strong uptake of our introductory pricing".
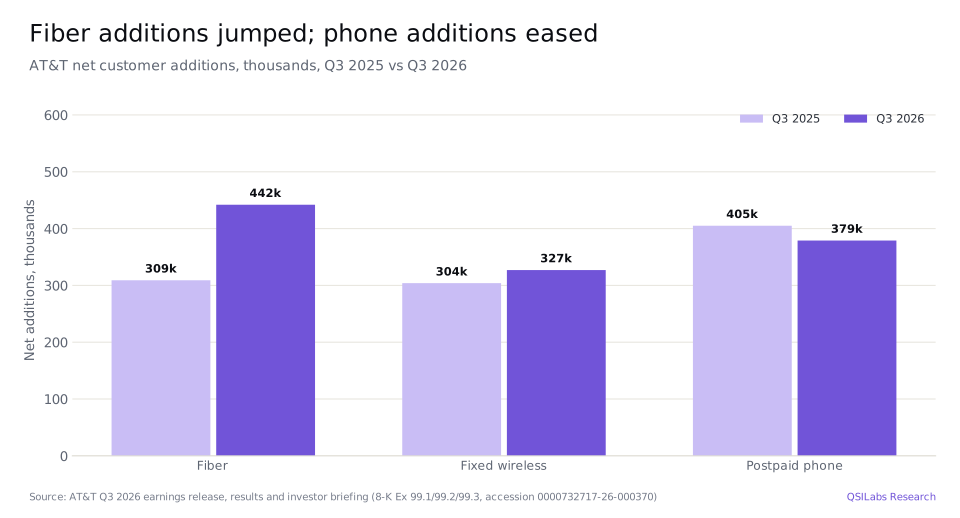
AT&T ended September with 16.25m internet connections, up 29.3% in a year: 13.31m on fiber and 2.94m on fixed wireless. Its fiber network reached more than 39m consumer and business locations, and AT&T expects more than 40m by the end of 2026 and more than 60m by the end of 2030. Advanced home internet revenue rose 23.4% to $2,975m.
The strategy is to sell wireless and internet together. AT&T calls customers who buy both "converged". Nearly 43% of its advanced home internet customers also had a postpaid wireless account, and AT&T added about 350,000 converged relationships in the quarter. Stankey said converged penetration in the former Lumen territories had risen by 250 basis points since the deal closed.
Wireless held steady. AT&T added 379,000 postpaid phone customers, against 405,000 a year earlier, and postpaid phone churn, the share leaving each month, was unchanged at 0.92%. Desroches called it "a competitive third quarter". AT&T ended September with 75.28m postpaid phone subscribers, up 2.0%.
Which AT&T revenue lines grew and which shrank?
The Advanced Connectivity segment, which holds the 5G and fiber businesses and is about 91% of revenue, grew revenue 7.2% to $29,481m. Its service revenue rose 6.1% to $23,902m and its operating income 18.9% to $7,628m, a 25.9% margin. Wireless service revenue rose 5.0% to $17,764m, business fiber and advanced connectivity 8.7% to $1,992m and equipment 12.2% to $5,579m. Business transitional services, older business products, fell 14.6% to $1,023m.
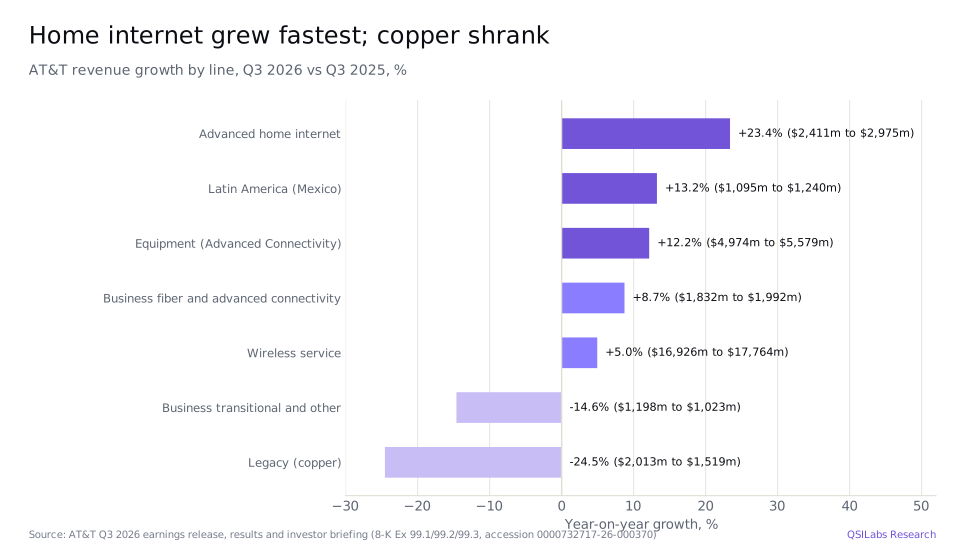
The Legacy segment, voice and data over the old copper network, shrank 24.5% to $1,519m as AT&T moves customers off copper. AT&T said it now has more than 100 wire centres with no legacy customers and is on track to stop copper-based services in 50% of its wire centres outside California by the end of 2027 and substantially all by the end of 2029. Latin America, AT&T's Mexico wireless business, grew revenue 13.2% to $1,240m; AT&T agreed on 13 October to sell it and expects about $2bn in cash at closing in the first quarter of 2027.
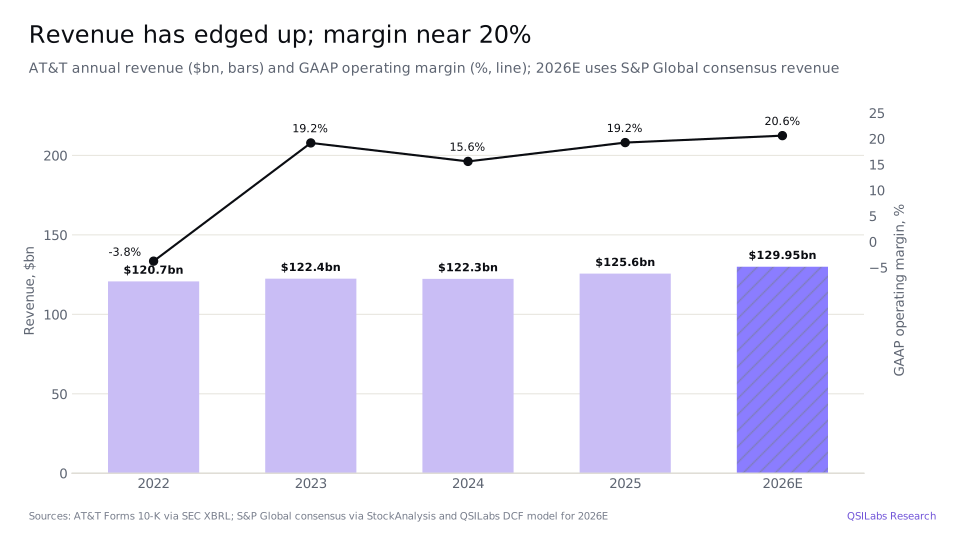
Over a longer period AT&T's revenue has barely moved, because it has been selling businesses and shrinking copper. Annual revenue was $120.7bn in 2022, $122.4bn in 2023, $122.3bn in 2024 and $125.6bn in 2025, and S&P Global consensus expects $129.95bn in 2026, up 3.4%. The GAAP operating margin was -3.8% in 2022, after large impairments, 19.2% in 2023, 15.6% in 2024 and 19.2% in 2025, and is 20.6% in our 2026 estimate.
How much cash does AT&T generate?
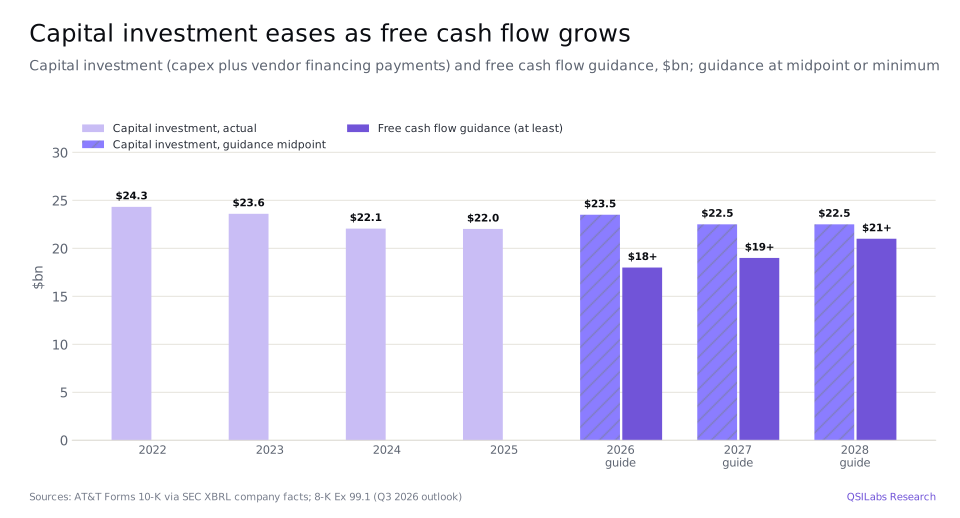
AT&T defines free cash flow as cash from operations less capital expenditure and cash paid for vendor financing. It was $4,953m in the third quarter, up 1.8% from $4,865m, and $12,129m in the first nine months, down 2.2% from $12,405m. Operating cash flow was $10,519m in the quarter, capital expenditure $5,061m and vendor financing payments $505m, so capital investment, AT&T's measure that adds the two, was $5.57bn.
AT&T expects about $6bn of free cash flow in the fourth quarter, against $4.2bn a year earlier, and still expects $18bn or more for 2026, with capital investment of $23bn to $24bn. It now expects cash taxes of about $750m for the year, down from $1bn to $1.5bn, which Desroches put down to "provisions in last year's One Big Beautiful Bill Act". For 2027 and 2028 AT&T lowered its capital investment plan to $22bn to $23bn a year and expects free cash flow of $19bn or more in 2027 and $21bn or more in 2028.
Most of that cash goes to shareholders. AT&T returned about $4.8bn in the quarter, including $2.8bn of share buybacks, and bought back 291m shares for $7.24bn in the first nine months. It plans to return more than $45bn in 2026 to 2028, including more than $24bn of buybacks, and pays a dividend of $1.11 a year, a yield of 5.2% at the 2 November close. At $18bn, 2026 free cash flow would be about 12.5% of AT&T's $144.4bn market value.
The spending is not only on networks. AT&T paid $22,650m in July for EchoStar's 600 MHz and 3.45 GHz spectrum licences, funded partly by $14.5bn of term loans, and $5,756m in February for Lumen's mass markets fiber business. Net debt rose to $149.8bn, 3.13 times adjusted EBITDA, from 2.68 times at the end of June.
How has T stock performed in 2026?
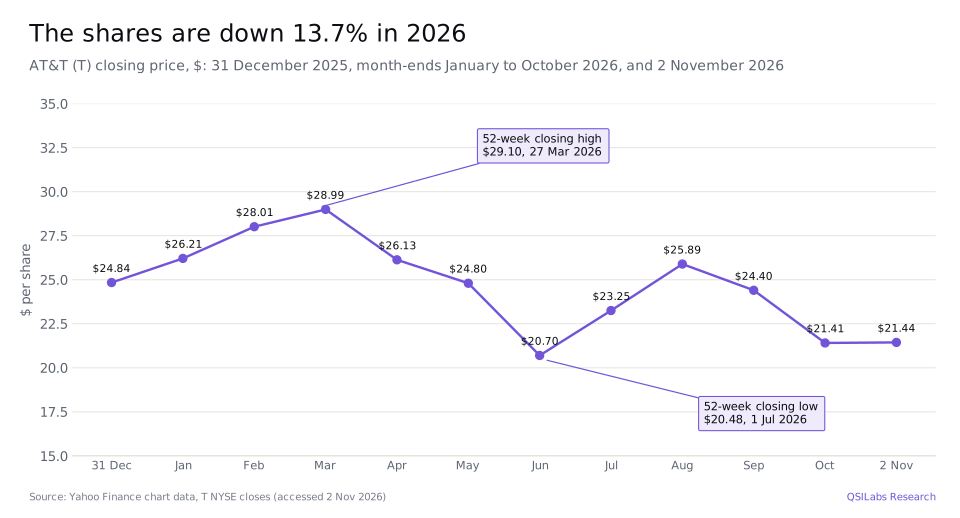
AT&T shares closed at $21.44 on 2 November 2026, down 13.7% from $24.84 at the end of 2025. They rose to a 52-week closing high of $29.10 on 27 March, fell to a closing low of $20.48 on 1 July, recovered to $25.89 at the end of August and slipped to $24.40 at the end of September.
On results day, 21 October, the shares fell 6.4% to $21.91 from $23.42. They closed at $20.70 on 28 October and recovered to $21.44 on 2 November.
AT&T stock Q3 2026: is AT&T undervalued?
On our numbers, yes. Our discounted cash flow model values AT&T at $52.54 a share, about 2.45 times the $21.44 close on 2 November 2026. At that price the equity was worth about $144.4bn, on 6,736m shares, and the enterprise value, adding debt of $160.8bn, noncontrolling interests of $18.0bn and $2.95bn of AT&T preferred stock and deducting $10.8bn of cash, about $315bn. That is 6.6 times the $47.87bn of adjusted EBITDA AT&T reported for the past four quarters, and 16.4 times our estimate of 2027 unlevered free cash flow, $19.20bn. The price is 8.9 times consensus 2026 adjusted earnings per share of $2.40.
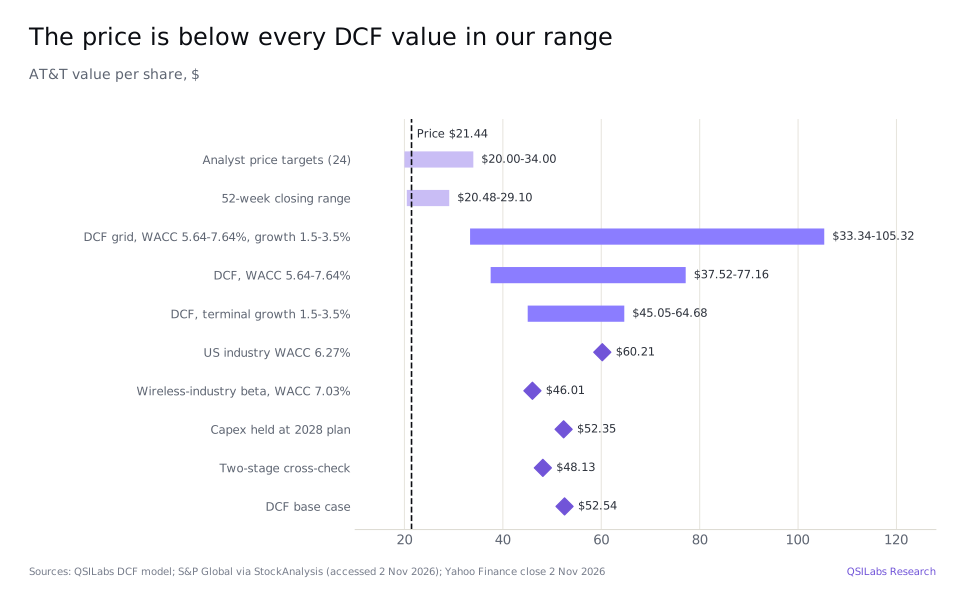
Because the value is well over twice the price, we checked what drives it. The main reason is the cost of capital. Debt is 52.6% of AT&T's capital at market value, above the 40% we treat as high, and it costs 4.55% after tax, so the blended rate is 6.64% even though the cost of equity is 8.97%. The second reason is that AT&T's cash flow is large and guided to grow: our unlevered free cash flow rises from $16.9bn in 2026 to $21.3bn in 2028. Our enterprise value of $523.3bn is 10.9 times trailing adjusted EBITDA, against 6.6 times at the market price.
Analysts are much closer to the price. The 24 analysts tracked by S&P Global rate AT&T a Buy on average, with an average price target of $27.59, a median of $27 and a range from $20 to $34. In November 10 rated it a Strong Buy, 4 a Buy, 9 a Hold and 1 a Strong Sell.
Method
We forecast revenue and GAAP operating margin year by year to 2035, apply a 24.1% tax rate, AT&T's effective rate for the first nine months of 2026, and deduct capital investment, including vendor financing, and working capital to reach unlevered free cash flow. We discount those cash flows at a 6.64% weighted average cost of capital. Equity is 47.4% of capital at a cost of 8.97%, from a 5.12% risk-free rate, a beta of 0.863 and an equity risk premium of 4.46% for the US; we exclude Mexico because AT&T is selling it. The beta is Damodaran's January 2026 global unlevered beta for telecom services companies, 0.471, relevered at AT&T's ratio of debt to equity, 1.11. Debt is 52.6% of capital at a pre-tax cost of 6.06%, taxed at 25%. After 2035 we assume growth of 2.5% a year; that terminal value is 70.0% of our enterprise value of $523.3bn. Deducting debt of $160.8bn, which includes $1.21bn of Mexico finance leases, and $18.0bn of noncontrolling interests, mostly preferred interests in AT&T subsidiaries, at book value, and adding cash of $10.8bn, gives equity value of $355.7bn, or $52.54 a share on 6,770m diluted shares at 30 September.
Smaller items net to about $0.4bn. We deduct $2.95bn of AT&T preferred stock, a $5.86bn after-tax pension and retiree benefit deficit and the $1.91bn dividend payable on 1 November. We add the roughly $2bn AT&T expects for Mexico, undiscounted, and the $1.21bn of Mexico finance leases the buyer takes over. We carry the Forged Fiber assets held for sale, $4.06bn net, and AT&T's $1.17bn of equity affiliates at book value rather than valuing them, and add about $2.69bn of cash generated between 30 September and 2 November.
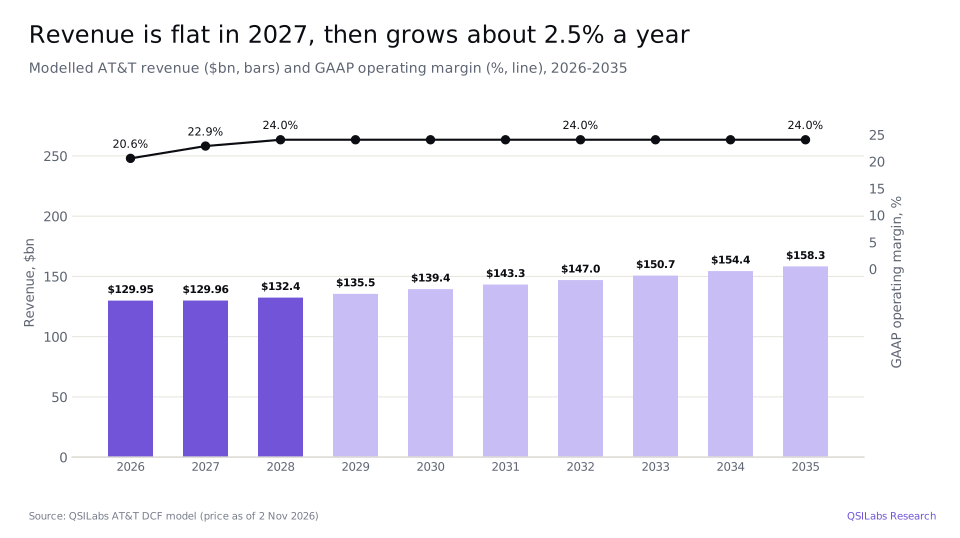
For 2026 we use the S&P Global consensus revenue of $129.95bn, up 3.4%, which implies fourth-quarter revenue of about $34.56bn, and GAAP operating income of $26.74bn, a 20.58% margin. That is nine-month operating income of $17.79bn, plus the $2.56bn non-cash Mexico impairment added back because we value Mexico through its sale price, plus about $6.39bn in the fourth quarter: the adjusted EBITDA implied by AT&T's guidance of growth in the upper portion of 3% to 4%, less depreciation and other adjusting items. For 2027 we use consensus revenue of $129.96bn, flat because Mexico leaves the numbers. For 2028 growth of 1.88% takes revenue to $132.4bn, in line with S&P Global's three-year forecast of 1.76% a year from 2025. Growth then rises to 2.37% in 2029 and 2.87% in 2030, MarketLine's forecast for US wireless telecom services from $230.6bn in 2025 to $265.6bn in 2030, and settles at 2.5% from 2033. Revenue reaches $158.3bn in 2035.
The operating margin is 22.87% in 2027 and 24.04% in 2028. Both come from AT&T's adjusted EBITDA outlook, growth in the upper portion of 3% to 4% in 2026 rising to 5% or more in 2028, with 2027 halfway between, less depreciation and amortisation at the third-quarter rate excluding Mexico and the run-rate of other adjusting items. We hold the margin at 24.04% after 2028. Depreciation and amortisation is 15.3% of revenue in 2026 and 14.7% from 2027. Capital investment is $23.5bn in 2026 and $22.5bn in 2027 and 2028, the guidance midpoints, and then follows our long-run rule, rising to $26.4bn by 2035, 16.7% of revenue.
We forecast unlevered free cash flow of $16.9bn in 2026, $19.2bn in 2027, $21.3bn in 2028, $22.6bn in 2030 and $26.0bn in 2035; only the part of 2026 after 2 November is discounted. Our figures are close to AT&T's free cash flow guidance, and below it in 2026, although they are measured before interest, because we tax operating profit at 24.1% while AT&T expects to pay only about $750m of cash tax this year. Our previous model, dated 21 October and priced at $21.91, gave $50.96 at a 6.27% cost of capital from Damodaran's US industry data. It assumed revenue growth of 2% a year, operating margins of 21.0% and 21.5%, depreciation of 15.5% of revenue, a 21% tax rate and a fourth quarter based on pre-results consensus, none of them tied to a source; we have replaced them with the consensus, company guidance and industry forecast above. With those old assumptions at today's date, price and 6.64% cost of capital, the model gives $45.23.
How the number moves if you argue with us
The table shows our value per share at different costs of capital and terminal growth rates. Even at a 7.64% cost of capital and 1.5% terminal growth, the model gives $33.34, about 1.6 times the share price.
| Cost of capital | Growth 1.5% | Growth 2.0% | Growth 2.5% | Growth 3.0% | Growth 3.5% |
|---|---|---|---|---|---|
| 5.64% | $62.50 | $68.83 | $77.16 | $88.60 | $105.32 |
| 6.14% | $52.82 | $57.37 | $63.15 | $70.74 | $81.16 |
| 6.64% | $45.05 | $48.40 | $52.54 | $57.79 | $64.68 |
| 7.14% | $38.67 | $41.18 | $44.22 | $47.97 | $52.72 |
| 7.64% | $33.34 | $35.25 | $37.52 | $40.27 | $43.65 |
The industry we map AT&T to matters. AT&T earns most of its revenue from wireless, so we also ran the model with Damodaran's global wireless telecom beta, 0.570 unlevered. That raises the cost of capital to 7.03% and gives $46.01. Damodaran's US industry cost of capital, 6.27%, which our previous model used, gives $60.21.
Capital spending makes little difference. Our long-run rule takes capital investment to 16.7% of revenue by 2035, close to the 17.0% implied by AT&T's 2028 plan; holding it at 17.0% from 2028 gives $52.35. A two-stage version of the model, which extends the fade over more years, gives $48.13.
Two checks point in different directions. AT&T's own five-year beta is 0.44, about half the 0.863 we use, which would lower the cost of capital and raise the value. But debt is 52.6% of capital, so the result depends on a large share of cheap debt, and AT&T's leverage is above its own 2.5 times target until 2029.
Our numbers and the market's can both be right only if AT&T's cash flow stops growing soon after 2028, or if investors demand a much higher return than the cost of capital for telecom companies implies. The pressures are real: competition for wireless customers, the cost of building fiber and retiring copper, high debt and the risk that the cash freed by lower capital spending goes to spectrum. We think the price already allows for most of that.
Risks to the AT&T investment case
- Wireless competition. Postpaid phone additions fell to 379,000 from 405,000, and AT&T expects higher marketing and customer acquisition costs in the fourth quarter. A price war with Verizon and T-Mobile would hit the biggest part of the business.
- Debt. Net debt is $149.8bn, 3.13 times adjusted EBITDA, and interest expense rose 16.4% in the quarter. AT&T does not expect to be back at about 2.5 times until 2029.
- Fiber build and copper exit. Reaching 60m fiber locations by 2030 and retiring copper by 2029 takes years of spending, and the Legacy segment is shrinking by about a quarter a year.
- Deals still to close. The Mexico sale is expected in the first quarter of 2027 and the fiber joint venture in the first half of 2027, both subject to approvals; we include about $2bn for Mexico and carry the fiber assets at book value.
- Leadership change. Pascal Desroches presented his final quarterly results as chief financial officer after nearly six years; a new finance chief may change priorities for spending and shareholder returns.
- Valuation risk. Our value depends heavily on the terminal value, 70.0% of enterprise value, and on a 6.64% cost of capital that leans on cheap debt; a higher rate or slower long-term growth would bring it closer to the share price.
FAQ
What value does QSILabs put on AT&T stock?
Our discounted cash flow model gives $52.54 a share, against a $21.44 close on 2 November 2026. Across costs of capital from 5.64% to 7.64% and terminal growth from 1.5% to 3.5% the value ranges from $33.34 to $105.32. A two-stage cross-check gives $48.13, and using a wireless-industry beta gives $46.01.
Should I buy AT&T stock after the Q3 2026 results?
We do not give personal advice. On our numbers the shares trade well below the value of their cash flows, and the third quarter showed record internet additions and steady cash flow. But the value depends on a low cost of capital driven by heavy borrowing, and debt is above AT&T's own target, so read the risks above before deciding.
How much revenue did AT&T make last quarter?
AT&T reported revenue of $32,322m for the third quarter of 2026, the three months to 30 September, up 5.3% from $30,709m. Service revenue was $26,301m and equipment revenue $6,021m. Adjusted earnings per share were $0.65 and reported diluted earnings per share $0.12.
What dividend does AT&T pay?
AT&T pays $0.2775 a share each quarter, $1.11 a year, a yield of about 5.2% at the $21.44 close on 2 November 2026. It paid $5,923m of dividends in the first nine months of 2026 and plans to keep the dividend at $1.11 while buying back more than $24bn of shares in 2026 to 2028.
What price target do analysts have for T?
The 24 analysts tracked by S&P Global have an average target of $27.59, about 29% above the $21.44 close on 2 November 2026, with a median of $27, a low of $20 and a high of $34. Their consensus rating is Buy.
How much debt does AT&T have?
AT&T reported net debt of $149.8bn at 30 September 2026, 3.13 times adjusted EBITDA, up from 2.68 times at the end of June after the EchoStar spectrum purchase. The debt we deduct in our valuation is $160.8bn, including $1.21bn of Mexico finance leases, against cash of $10.8bn.
What did AT&T change in its outlook?
AT&T raised its 2026 adjusted earnings per share outlook to about $2.40 from $2.25 to $2.35 and now expects adjusted EBITDA growth in the upper portion of 3% to 4%. It lowered its capital investment plan for 2027 and 2028 to $22bn to $23bn a year and kept its free cash flow targets of $18bn or more in 2026, $19bn or more in 2027 and $21bn or more in 2028.
Why is AT&T selling its Mexico business?
AT&T said the Mexico sale, together with the EchoStar spectrum and Lumen fiber purchases, will "sharpen our US investment focus". It expects about $2bn in cash at closing in the first quarter of 2027 and booked a $2.6bn impairment on the business in the third quarter.
Who runs AT&T?
John Stankey is chairman and chief executive of AT&T. Pascal Desroches presented his final quarterly results as chief financial officer on 21 October 2026.
Sources
- AT&T Inc., third-quarter 2026 earnings release (Form 8-K, Exhibit 99.1, 21 Oct 2026; accession 0000732717-26-000370) www.sec.gov
- AT&T Inc., third-quarter 2026 financial and operational results (Form 8-K, Exhibit 99.2, 21 Oct 2026; accession 0000732717-26-000370) www.sec.gov
- AT&T Inc., third-quarter 2026 investor briefing and non-GAAP reconciliations (Form 8-K, Exhibit 99.3, 21 Oct 2026; accession 0000732717-26-000370) www.sec.gov
- AT&T Inc., Form 10-Q for the quarter ended 30 Sep 2026 (filed 21 Oct 2026; accession 0000732717-26-000372) www.sec.gov
- SEC XBRL company facts for AT&T Inc. (CIK 732717): annual and quarterly revenue, operating income, operating cash flow, capital expenditure and vendor financing from Forms 10-K and 10-Q data.sec.gov
- AT&T Q3 2026 earnings call transcript, 21 Oct 2026 (LSEG StreetEvents, published by AT&T Investor Relations; accessed 2 Nov 2026) investors.att.com
- StockAnalysis: AT&T forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: AT&T statistics (accessed 2 Nov 2026) stockanalysis.com
- MarketLine, Wireless Telecommunication Services North America (NAFTA) Industry Guide 2021-2030, July 2026 (MarketPublishers summary) pdf.marketpublishers.com
- Yahoo Finance chart data: T closing prices and dividends (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: industry betas (global) and equity risk premiums, January 2026 pages.stern.nyu.edu
- QSILabs AT&T discounted cash flow model (internal; price as of 2 Nov 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Verizon stock Q3 2026: phones and fiber, T-Mobile stock Q3 2026: ARPA and cash flow, Comcast stock Q3 2026: broadband and Peacock and Cisco stock Q3 2026: AI networking orders.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.