Research / Earnings and valuation
Prologis Stock Q3 2026:Core FFO Up 7% as Leasing Holds and SEGRO Nears
As of: Figures are as of Prologis, Inc.'s third-quarter 2026 results and supplemental information (the quarter ended 30 September 2026, reported 15 October 2026 in a Form 8-K) and its Form 10-Q for that quarter, filed on 28 October 2026. Prologis's fiscal year is the calendar year, so its Q3 2026 covers July to September 2026. The share price used in our valuation is the NYSE close of PLD on 2 November 2026, $129.65; analyst data were accessed on 2 November 2026. Published 2 November 2026.
The short answer. Prologis stock Q3 2026 is a story of steady warehouse demand, a bigger development programme tilted towards data centers and a pending takeover of SEGRO. In the three months to 30 September 2026, total revenues rose 7.8% to $2,387.5m and Core funds from operations (Core FFO), the cash earnings measure Prologis guides on, rose 7.4% to $1.60 a diluted share. Average occupancy was 95.1%, cash same-store net operating income (NOI) rose 5.9%, and new leases were signed at net effective rents 38.0% above the leases they replaced. Prologis narrowed its 2026 Core FFO guidance to $6.25-6.29 a share and raised its targets for development starts and acquisitions. Our discounted cash flow model gives $124.51 a share, against a $129.65 close on 2 November 2026; below we show which assumptions drive that number and how far it moves when you change them.
Key takeaways
- Revenue rose 7.8%, Core FFO per share 7.4%. Total revenues were $2,387.5m, up from $2,213.9m, and Core FFO was $1,545m, or $1.60 a diluted share, up from $1.49. Adjusted funds from operations (AFFO) rose 13.4% to $1,207m.
- Leasing held up. Average occupancy was 95.1%, Prologis commenced 55.9m square feet of leases with 75.9% retention, and rents on renewed and re-let space were 38.0% higher on a net effective basis and 23.4% higher in cash.
- Guidance narrowed. The 2026 Core FFO range moved to $6.25-6.29 a share from $6.22-6.30, and cash same-store NOI growth to 7.00-7.50% from 6.75-7.25%. The midpoint implies fourth-quarter Core FFO of about $1.54 a share.
- More building, much of it data centers. Development starts were $4,089m in the first nine months, Prologis share, at an estimated 7.7% stabilized yield; data centers were $2,034m of that. Guidance for 2026 starts rose to $5,000-5,750m.
- SEGRO is coming but not in our numbers. Prologis agreed on 4 August to buy SEGRO plc for 0.0920 Prologis shares per SEGRO share plus a partial cash alternative; SEGRO shareholders approved it on 28 September and completion is expected in the first half of 2027.
- Our value: $124.51 a share, 4.0% below the $129.65 close on 2 November 2026. Analysts' average target is $152.07; with Prologis's own five-year beta of 1.32 instead of the industry beta, our model would give $55.89.
- What to watch. Rent growth as older leases reprice, the yields on the data center pipeline, how the SEGRO deal is financed and how much new stock Prologis issues under its new $5bn programme.
Key numbers from Prologis's Q3 2026 earnings
| Measure | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total revenues | $2,387.5m | $2,213.9m | +7.8% |
| Rental revenues | $2,205.3m | $2,054.2m | +7.4% |
| Strategic capital revenues | $164.3m | $150.4m | +9.2% |
| Net earnings attributable to common stockholders | $815.7m | $762.9m | +6.9% |
| Net earnings per diluted share | $0.86 | $0.82 | +4.9% |
| Core FFO | $1,545m | $1,426m | +8.3% |
| Core FFO per diluted share | $1.60 | $1.49 | +7.4% |
| AFFO | $1,207m | $1,064m | +13.4% |
| Adjusted EBITDA | $2,081m | $1,868m | +11.4% |
| Dividend per share | $1.07 | $1.01 | +5.9% |
Sources: Prologis Q3 2026 Form 10-Q (revenues and net earnings) and Q3 2026 supplemental information (Form 8-K).
Prologis Q3 2026 earnings: what happened
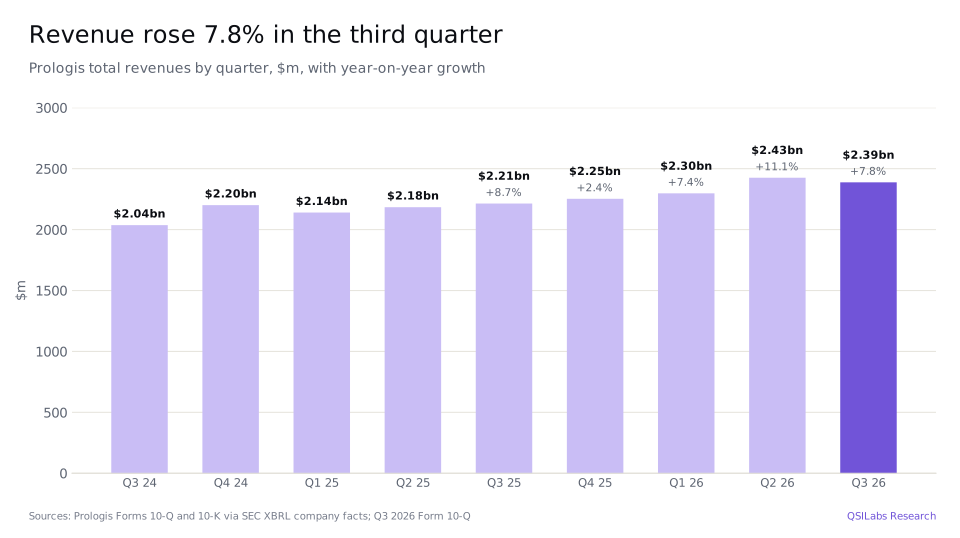
Prologis reported third-quarter results on 15 October 2026. Total revenues rose 7.8% to $2,387.5m from $2,213.9m. Rental revenues from its warehouses rose 7.4% to $2,205.3m, strategic capital revenues, the fees Prologis earns for managing property funds for other investors, rose 9.2% to $164.3m, and development management and other revenues were $17.9m. For the first nine months, total revenues were $7,110.7m, up 8.8% from $6,537.4m.
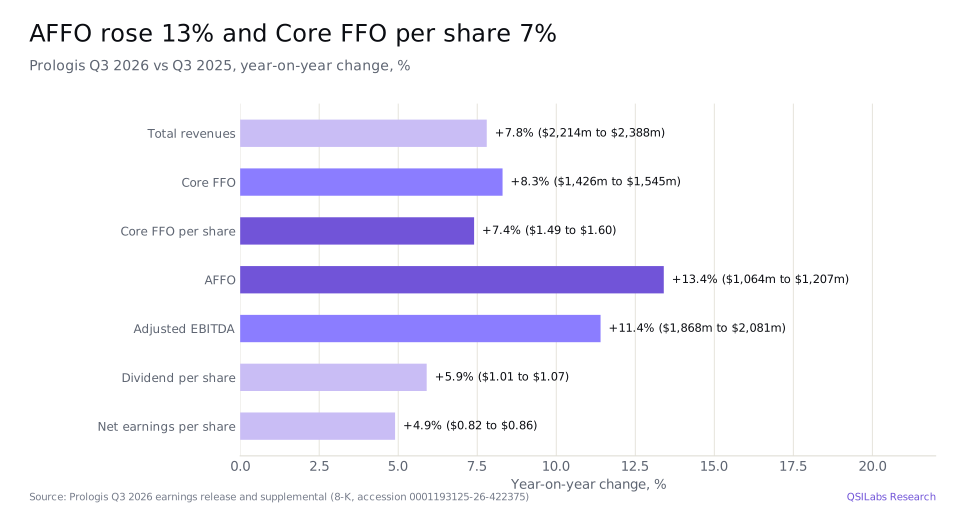
Net earnings attributable to common stockholders were $815.7m, or $0.86 a diluted share, against $762.9m and $0.82. Real estate investment trusts (REITs) are usually judged on funds from operations, which add back the depreciation of their buildings and exclude gains on property sales. Core FFO was $1,545m, up 8.3%, or $1.60 a diluted share, up 7.4%. AFFO, which also deducts the cash spent maintaining and re-leasing buildings, rose 13.4% to $1,207m. Over nine months Core FFO per share was $4.73, up 8.2% from $4.37, and AFFO was $4,002m, up 25.7%.
Prologis now expects 2026 Core FFO of $6.25-6.29 a share, against $6.22-6.30 before, which leaves about $1.54 a share for the fourth quarter at the midpoint. It lowered its range for 2026 net earnings to $4.05-4.15 a share from $4.40-4.55 and its forecast of strategic capital revenue, excluding promotes, to $650-660m from $660-680m.
The quarterly dividend was $1.07 a share, up from $1.01 a year earlier, or 67% of third-quarter Core FFO per share. Common stock dividends and unit distributions were $1,045m in the quarter.
- 31 Dec 2025PLD closes 2025 at $127.66Yahoo Finance
- 16 Jul 202652-week closing high of $150.06Yahoo Finance
- 4 Aug 2026Definitive agreement to acquire SEGRO plc for 0.0920 Prologis shares per SEGRO share, with a partial cash alternative of up to about £3.5bnForm 10-Q
- Aug 202617.25m new shares sold for about $2.4bn of net proceeds; $1.0bn placed in short-term investmentsForm 10-Q
- 16 Sep 2026Shares go ex-dividend for the quarterly dividend of $1.07Yahoo Finance
- 28 Sep 2026SEGRO shareholders approve the acquisitionForm 10-Q
- 15 Oct 2026Q3 results: Core FFO $1.60 a share; 2026 Core FFO guidance narrowed to $6.25-6.29; PLD closes at $126.94, down 2.7%8-K; Yahoo
- 28 Oct 2026Form 10-Q filed; SEGRO completion still expected in the first half of 2027Form 10-Q
- 30 Oct 2026New at-the-market equity programme of up to $5bn replaces the 2020 agreementForm 8-K
- 2 Nov 2026PLD closes at $129.65, the price used in our valuationYahoo Finance
How strong is demand for Prologis warehouses?
Steady rather than booming. Average occupancy was 95.1% in the third quarter and 95.6% at the end of the period. Prologis commenced 55.9m square feet of leases in its operating and development portfolio and kept 75.9% of tenants whose leases expired. Its chief executive, Daniel S. Letter, said the company signed 60m square feet of leases in the quarter and that "customers are running lean on inventory, and excess capacity within their networks has largely cleared."
The larger driver of growth is that rents on existing leases are still well below market. When leases rolled over in the third quarter, net effective rents on the new leases were 38.0% higher than on the old ones, and cash rents were 23.4% higher. That is why cash same-store NOI rose 5.9% even with occupancy roughly flat, and why Prologis raised its 2026 forecast for cash same-store NOI growth to 7.00-7.50%. It narrowed its average occupancy forecast to 95.25-95.50% from 95.25-95.75%.
Prologis owns or manages 5,941 buildings with 1.3bn square feet. The United States produces 84% of its NOI, Europe 9%, other Americas 5% and Asia 2%. Annualized NOI was $7.2bn and gross assets under management $238bn.
Where is Prologis investing, and how is it paying?
Prologis builds most of its growth. In the first nine months of 2026 it started $4,089m of developments, Prologis share, at an estimated stabilized yield of 7.7% and an estimated margin of 28.4%, and 64.2% of those starts were built to suit a specific customer. Data centers were $2,034m of the total. The company says it has 5.8 gigawatts of data center power secured or in an advanced stage, including 1.7 gigawatts secured. It also bought $2,089m of buildings and sold or contributed $1,855m to its funds.
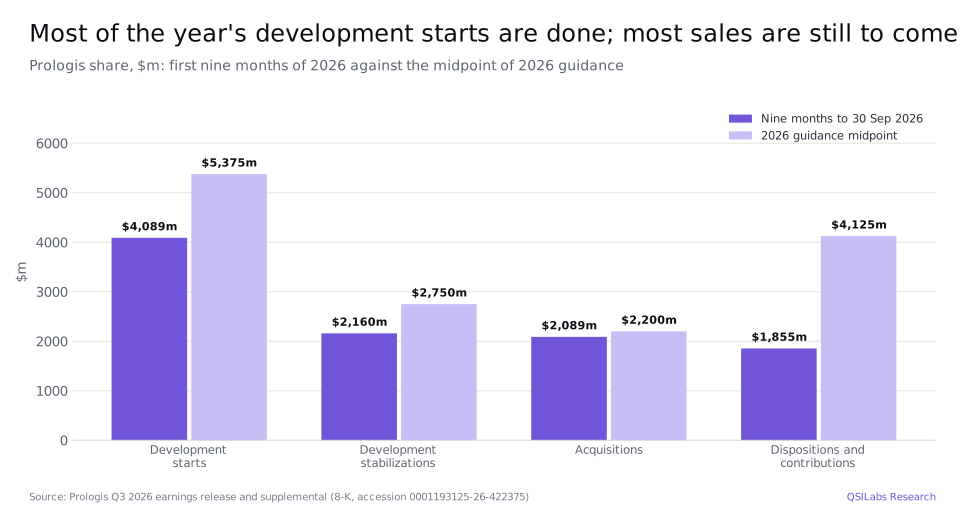
The 2026 guidance puts development starts at $5,000-5,750m, up from $4,500-5,500m, and acquisitions at $2,100-2,300m, up from $1,500-2,000m. Dispositions are now $1,750-2,500m and contributions $1,750-2,250m, both lower than before. At the midpoints that is net investment of about $3.45bn this year; because the nine-month figure is already $4.32bn, the guidance implies about $0.87bn more sold and contributed than invested in the fourth quarter.
The funding is mostly debt and new shares. Consolidated debt was $36.8bn at 30 September 2026, with a weighted average term of eight years and an effective interest rate of 3.2%. Including its share of fund debt, Prologis's weighted average interest rate was 3.3%, debt was 4.5 times adjusted EBITDA and 23.9% of total market capitalization, and its credit ratings were A from S&P and A2 from Moody's. In the quarter it and its funds raised $1.3bn of new debt at 4.0%. In August it sold 17.25m new shares for about $2.4bn of net proceeds and put $1.0bn of that into short-term investments maturing between December 2026 and February 2027. On 30 October it signed a new at-the-market agreement to sell up to $5bn of shares from time to time, replacing a 2020 agreement. Liquidity was about $8.8bn.
What does the SEGRO acquisition change?
On 4 August 2026 Prologis agreed to buy SEGRO plc, one of Europe's largest warehouse owners. SEGRO shareholders will receive 0.0920 Prologis shares for each SEGRO share and may choose a cash alternative of up to about £3.5bn in total, 25% of the consideration, at a fixed 1,031.7 pence per share, subject to scale-back. Prologis will also take on SEGRO's debt and is applying for a secondary listing of its shares in London. SEGRO shareholders approved the deal on 28 September, and Prologis expects to complete it in the first half of 2027, subject to regulatory approvals.
The deal would roughly double the 9% of NOI Prologis earns in Europe, add a large number of new shares and bring more euro and sterling debt. We have not modelled it: our forecast, share count and balance sheet are for Prologis alone, including the shares sold in August and the cash they raised.
Prologis stock Q3 2026: is PLD overvalued?
Not on our numbers by much: our model gives $124.51 a share, 4.0% below the $129.65 close on 2 November 2026. At that price the shares trade at 20.7 times the midpoint of 2026 Core FFO guidance, and the $4.28 annual dividend is a yield of 3.3%.
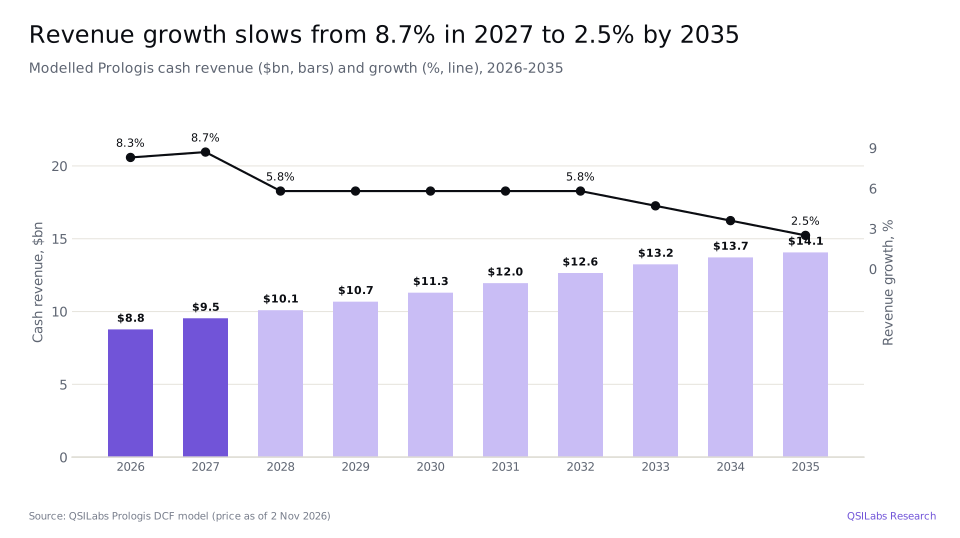
We value Prologis on its cash rents, not its accounting revenue. Our revenue line is total revenues less straight-line rent and the amortization of lease intangibles, and our operating profit is AFFO with interest, our share of fund interest and current taxes added back, on a Prologis-share basis. That profit was 68.4% of cash revenue in the first nine months of 2026, against 64.1% in 2025, and we hold the 68.4% margin. We put fourth-quarter cash revenue at $2,165.6m from S&P Global consensus rental revenue of $2.24bn, guided strategic capital revenue and the nine-month run rate of development fees, which gives cash revenue of $8.77bn for 2026, up 8.3%.
For 2027 revenue growth is 8.73%. Consensus revenue for 2027 averages $9.68bn, up 10.6%, but the highest of the six estimates, $10.51bn, appears to include SEGRO; the other five average $9.51bn, up 8.73% on 2026's $8.75bn. From 2028 to 2032 we use 5.80% a year, Mordor Intelligence's forecast for the global warehouse real estate market from 2027 to 2032, and then fade to 4.7%, 3.6% and 2.5% in 2035. That keeps Prologis at about 3.2% of Mordor's 2032 market of $393.2bn, against 3.1% of its 2026 market of $280.4bn.
Cash flow is operating profit after a 4.0% tax rate, Prologis's current tax in the first nine months of 2026 excluding tax on property sales, less net investment: development, acquisitions, dispositions and contributions together. We hold net investment at the $3.45bn guided for 2026 until 2032. At the 7.1% yield Prologis earned on its nine-month mix of developments, acquisitions and sales, that spending adds about 3.8 points a year to revenue growth in 2028, leaving about 2.0 points from rent increases on existing buildings. Net investment then falls to $2.41bn in 2033, $1.25bn in 2034 and close to nil in 2035, because our long-run growth of 2.5% equals the rent growth we assume on existing buildings. Free cash flow rises from $2.81bn in 2027 to $4.85bn in 2032 and $9.23bn in 2035. Only the part of 2026 after 2 November is discounted. A development or acquisition yielding 7.1% with rent rising 2.5% a year returns about 9.6%, above our cost of capital, so on our assumptions each $1 invested adds about $0.64 of value.
The 6.85% cost of capital uses one beta: Damodaran's January 2026 global REIT unlevered beta of 0.354, relevered at Prologis's debt-to-equity ratio of 0.34 to 0.468, with a 4.0% tax rate because a REIT pays little corporate tax. The equity risk premium of 4.54% is weighted by where Prologis earned its 2025 revenue, 91.0% in the US. With a 5.12% risk-free rate that gives a cost of equity of 7.24%. The cost of debt is 5.90% before tax and 5.67% after, and debt is 25.2% of capital at market value. Prologis's own five-year beta is 1.32, nearly three times the relevered industry beta; using it would raise the cost of capital to 9.74% and cut our value to $55.89, so the beta is the single largest assumption in this valuation. The terminal value is 78.5% of our enterprise value of $151.14bn.
From enterprise value we add cash of $3.54bn, which includes the $1.0bn of short-term investments and our share of fund cash, and deduct debt of $42.61bn, Prologis's share of consolidated and fund debt. We add land of $4.79bn and properties under development of $2.92bn, both at book cost: they earn no rent yet, and we do not add the development profit Prologis expects on them. We deduct $0.06bn of preferred stock. We add $1.85bn for October's cash flow and the fourth-quarter sales and contributions implied by guidance, which our 2026 cash flow does not carry. That gives equity value of $121.58bn, or $124.51 a share on 976.45m shares and operating partnership units, including 6.99m from equity awards.
Our previous model, dated 21 October and priced at $127.60, gave $150.40. It used the US marginal corporate tax rate from Damodaran's tables in the cost of capital, which lowered both the relevered beta and the after-tax cost of debt; with the 4.0% rate Prologis actually pays, the cost of capital rises from 6.45% to 6.85%, and at 6.45% our new forecast would give $142.02. It also assumed faster growth after 2027, a 67.5% margin and rising investment. Run on today's price, balance sheet and cost of capital, that old path gives $134.65, so the consensus, company and industry path above takes off about $10.14 a share.
How the number moves if you argue with us
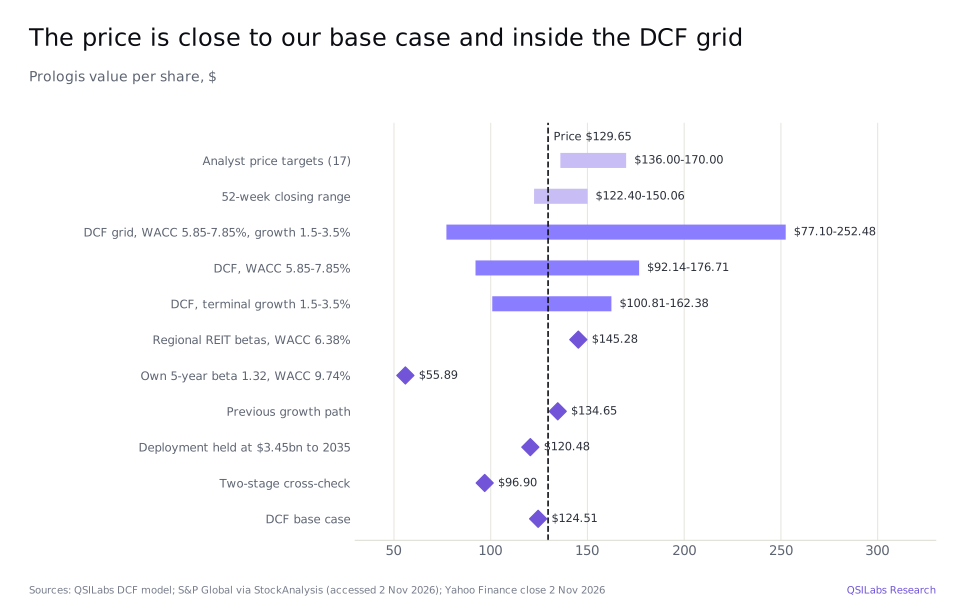
The table shows our value per share at different costs of capital and terminal growth rates. The $129.65 price sits inside the grid: it needs a cost of capital of about 6.35% with terminal growth of 2.0%, or 6.85% with growth of about 2.7%.
| Cost of capital | Growth 1.5% | Growth 2.0% | Growth 2.5% | Growth 3.0% | Growth 3.5% |
|---|---|---|---|---|---|
| 5.85% | $135.82 | $153.61 | $176.71 | $207.94 | $252.48 |
| 6.35% | $116.46 | $130.05 | $147.16 | $169.40 | $199.45 |
| 6.85% | $100.81 | $111.44 | $124.51 | $140.99 | $162.38 |
| 7.35% | $87.91 | $96.39 | $106.62 | $119.20 | $135.06 |
| 7.85% | $77.10 | $83.98 | $92.14 | $101.99 | $114.11 |
Other runs of the model: using the full consensus average for 2027 growth, 10.6%, gives $127.55. Keeping net investment at $3.45bn a year all the way to 2035, without any extra growth, gives $120.48. Regional REIT costs of capital, each with its own beta, average 6.38% and give $145.28. A two-stage version of the model, which adds ten more years in which growth slows to 2.5% and returns on new investment fall towards our cost of capital plus 2 points, gives $96.90.
The market price and our value are close, so the debate is less about whether Prologis is expensive than about what could move it: faster rent growth than the 2% a year we allow on existing buildings, higher returns on data centers, or a lower cost of capital push the value up; a beta closer to Prologis's own trading history pushes it down sharply.
Risks to the Prologis investment case
- Rent growth slows. Much of Prologis's growth comes from resetting old leases to market. If market rents stall, the 38.0% net effective rent change on rollover will shrink and same-store NOI growth will slow.
- Data center execution. About half of nine-month development starts were data centers. These projects need secured power and creditworthy tenants, and the estimated 7.7% yield on starts is not yet earned.
- The SEGRO deal. Integrating SEGRO, paying up to about £3.5bn in cash and issuing a large number of new shares adds currency, financing and execution risk that our model does not capture.
- Dilution. Prologis sold 17.25m shares in August and has a new $5bn at-the-market programme. Issuing stock below the value of the cash flows it buys would reduce value per share.
- Interest rates. The weighted average rate on Prologis's share of debt is 3.3%, while new debt in the quarter cost 4.0%. Refinancing at higher rates would lower AFFO, and higher rates would raise the cost of capital.
- Valuation risk. Our value depends heavily on a low industry beta. With Prologis's own beta of 1.32 the model would give $55.89 a share.
FAQ
What value does QSILabs put on Prologis stock?
Our discounted cash flow model gives $124.51 a share, against a $129.65 close on 2 November 2026. Across costs of capital from 5.85% to 7.85% and terminal growth from 1.5% to 3.5% the value ranges from $77.10 to $252.48. A two-stage cross-check gives $96.90.
Should I buy Prologis stock after the Q3 2026 results?
We do not give personal advice. The third quarter showed 7.4% Core FFO growth per share, 95.1% occupancy and rents on renewed leases 38.0% above the old ones. On our numbers the shares trade close to the value of their cash flows, so the outcome depends mainly on rent growth, data center returns and the cost of capital; read the risks above before deciding.
How much revenue did Prologis make in its latest quarter?
Prologis reported total revenues of $2,387.5m for the third quarter of 2026, the three months to 30 September, up 7.8% from $2,213.9m. Rental revenues were $2,205.3m and strategic capital revenues $164.3m. Net earnings were $815.7m, or $0.86 a diluted share.
What is Core FFO, and how much did Prologis earn on that basis?
Funds from operations add property depreciation back to net earnings and remove gains on property sales; Prologis's Core FFO also excludes certain other items set out in its supplemental information. Core FFO was $1,545m, or $1.60 a diluted share, in the third quarter of 2026, up from $1.49 a year earlier.
What dividend does Prologis pay?
Prologis pays a quarterly dividend of $1.07 a share, up from $1.01 a year earlier, or $4.28 a year. At the $129.65 close on 2 November 2026 that is a yield of 3.3%.
What price target do analysts have for PLD?
The 17 analysts tracked by S&P Global have an average target of $152.07, about 17% above the $129.65 close on 2 November 2026, with a median of $151.50, a low of $136 and a high of $170. Their consensus rating is Buy.
How much debt does Prologis have?
Consolidated debt was $36.8bn at 30 September 2026, at an effective interest rate of 3.2% and an average term of eight years. Including its share of fund debt, Prologis's debt was 4.5 times adjusted EBITDA and 23.9% of total market capitalization, and it is rated A by S&P and A2 by Moody's.
When will the Prologis takeover of SEGRO close?
Prologis expects to complete the acquisition in the first half of 2027, subject to regulatory approvals and other conditions. SEGRO shareholders approved it on 28 September 2026. They will receive 0.0920 Prologis shares per SEGRO share, with a cash alternative of up to about £3.5bn in total.
How did Prologis shares react to the results?
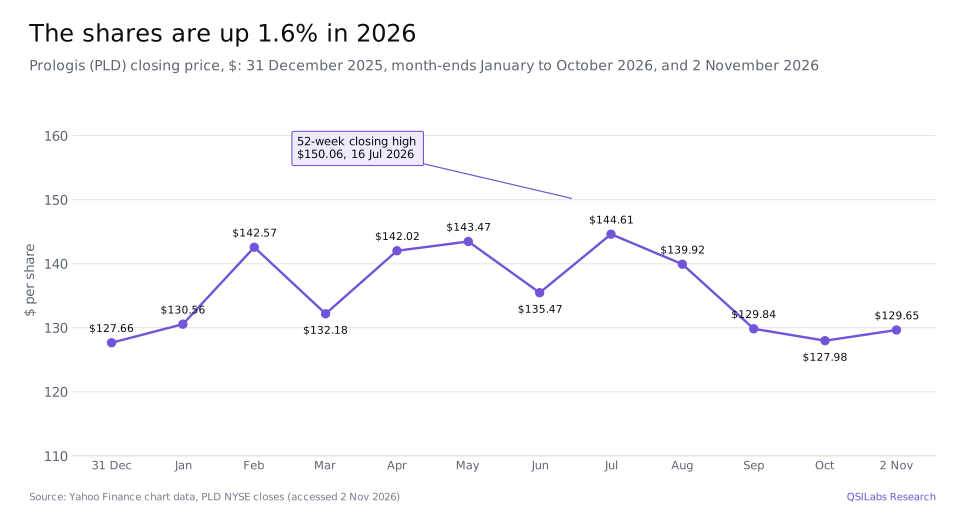
Prologis released its results on 15 October 2026, when the shares fell 2.7% to $126.94 from $130.46. They closed at $125.75 the next day and had recovered to $129.65 by 2 November 2026, 1.6% above their close at the end of 2025.
Sources
- Prologis, Inc., third-quarter 2026 earnings release (Form 8-K exhibit 99.1, 15 Oct 2026; accession 0001193125-26-422375) www.sec.gov
- Prologis, Inc., third-quarter 2026 supplemental information (Form 8-K exhibit 99.2, 15 Oct 2026; accession 0001193125-26-422375) www.sec.gov
- Prologis, Inc., Form 10-Q for the quarter ended 30 Sep 2026 (filed 28 Oct 2026; accession 0001193125-26-436160) www.sec.gov
- Prologis, Inc., Form 8-K dated 30 Oct 2026: equity distribution agreement (accession 0001104659-26-120653) www.sec.gov
- Prologis, Inc., Form 10-K for the year ended 31 Dec 2025 (accession 0001193125-26-051453): segment revenues by geography and 2025 results www.sec.gov
- SEC XBRL company facts for Prologis, Inc. (CIK 1045609): quarterly and annual revenues from Forms 10-Q and 10-K data.sec.gov
- StockAnalysis: Prologis forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: Prologis statistics (accessed 2 Nov 2026) stockanalysis.com
- Equibles: Prologis analyst estimates (accessed 2 Nov 2026) equibles.com
- Mordor Intelligence, Warehouse Real Estate Market report (accessed 2 Nov 2026) www.mordorintelligence.com
- Mordor Intelligence, United States Commercial Real Estate Market report (accessed 2 Nov 2026) www.mordorintelligence.com
- Yahoo Finance chart data: PLD closing prices and dividends (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: betas and cost of capital by industry (global and regional), January 2026 pages.stern.nyu.edu
- QSILabs Prologis discounted cash flow model (internal; price as of 2 Nov 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Welltower stock Q3 2026: seniors housing occupancy, Union Pacific stock Q3 2026: volumes and Norfolk Southern, Amazon stock Q3 2026: earnings and valuation and NextEra Energy stock Q3 2026: FPL rate base and backlog.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.