Research / Earnings and valuation
IBM Stock Q3 2026:Software Speeds Up, Cash Flow Outlook Raised
As of: Figures are as of IBM's third-quarter 2026 results (the quarter ended 30 September 2026, reported 21 October 2026 in a Form 8-K earnings release, with the Form 10-Q filed 22 October 2026). IBM's fiscal year is the calendar year, so Q3 2026 is the July-September 2026 quarter. The share price used in our valuation is the NYSE close of IBM on 30 October 2026, $257.81; the stock closed at $252.51 on 2 November 2026. Published 2 November 2026.
The short answer. IBM stock Q3 2026 results, for the July to September quarter, showed revenue growth picking up to 5%, or 6% at constant currency, led by Software and Infrastructure. Revenue was $17.1bn, operating (non-GAAP) earnings per share rose 11% to $2.95 and GAAP EPS rose 26% to $2.31. IBM kept its forecast of 4-5% revenue growth at constant currency for 2026 and now expects free cash flow to rise by more than $1bn, from $14.7bn in 2025. Our discounted cash flow model puts IBM at $190.05 per share, about 26% below the $257.81 close on 30 October 2026. The quarter was solid and the cash flow is real; the share price assumes faster growth, or a lower cost of capital, than our model does.
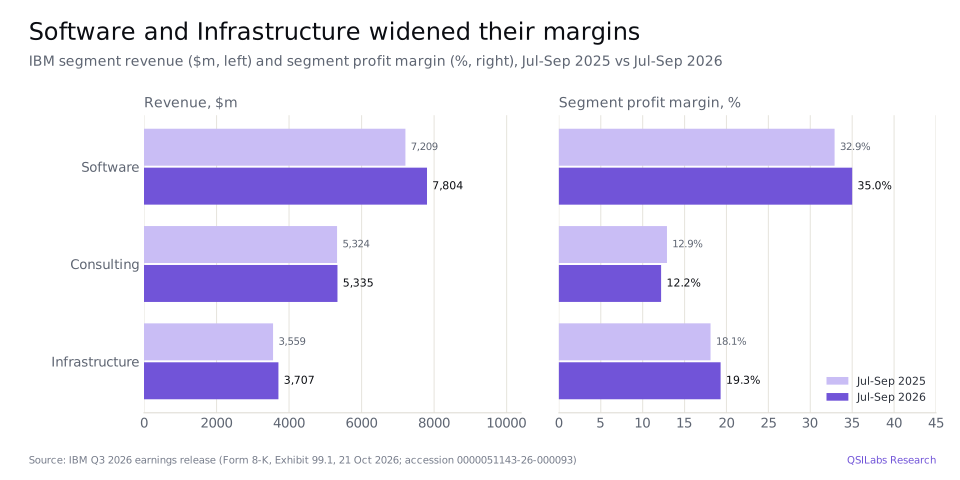
International Business Machines (IBM) now earns most of its profit from software: Red Hat's hybrid cloud platform, automation and data tools (including Confluent, bought in March 2026) and transaction-processing software that runs on its mainframes. It also sells consulting and infrastructure, chiefly the IBM Z mainframe, Power servers and storage. In the quarter to 30 September 2026, Software revenue rose 8% (9% at constant currency) and its segment profit margin widened by 2.1 points to 35.0% (IBM Q3 2026 earnings release). The shares closed at $251.46 on 21 October, before the after-hours release, rose 0.3% the next day and closed at $257.81 on 30 October, 15.4% below the $304.73 close of 3 November 2025 and 21.7% below the 52-week closing high of $329.23 set on 2 June (Yahoo Finance).
Below we go through IBM's Q3 2026 numbers against a year earlier, segment by segment, set out what the unchanged revenue outlook and the higher cash flow outlook imply for the fourth quarter, cover cash, debt and the dividend, and then value IBM stock, with every assumption laid out so you can argue with it.
Key takeaways
- Valuation: QSILabs values International Business Machines (NYSE: IBM) at $190.05 per share as of results for the quarter ended 30 September 2026, against a $257.81 close on 30 October 2026, about 26% below the market price. Our sensitivity range is about $161-230 a share.
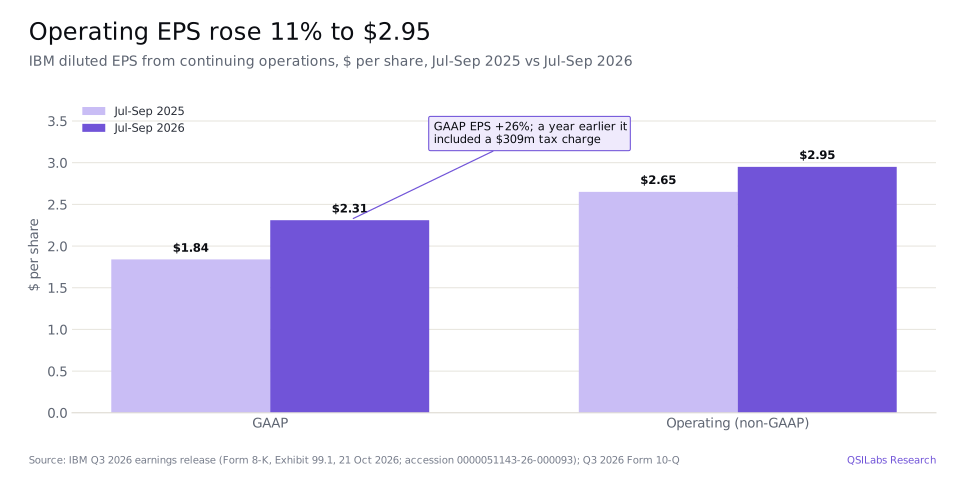
- Q3 2026 results: revenue was $17,103m in the quarter ended 30 September 2026, up 5% from $16,331m and 6% at constant currency; operating pre-tax income was $3,295m, a 19.3% margin, up 0.7 points; operating EPS was $2.95, up 11%, and GAAP EPS $2.31, up 26%.
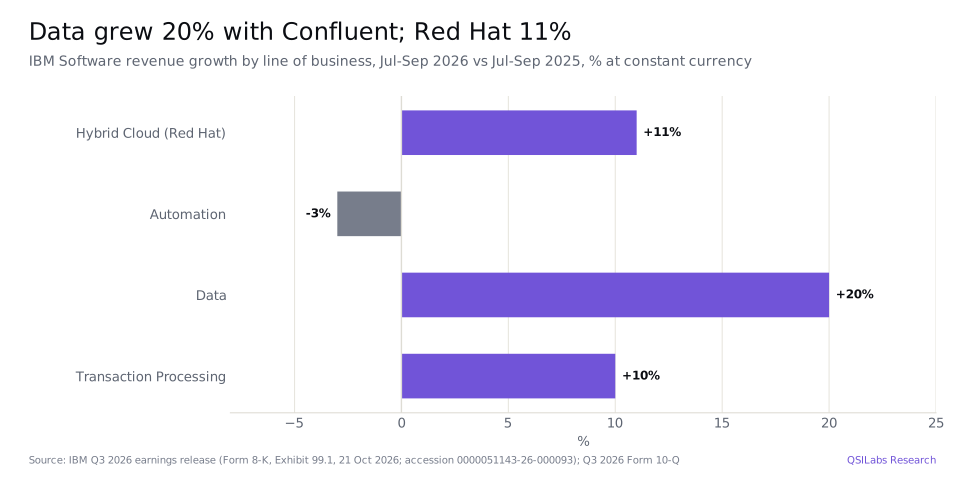
- Software: Software revenue was $7,804m, up 9% at constant currency, with Red Hat up 11% and Data up 20% at constant currency, helped by Confluent. The segment profit margin was 35.0%, up from 32.9%.
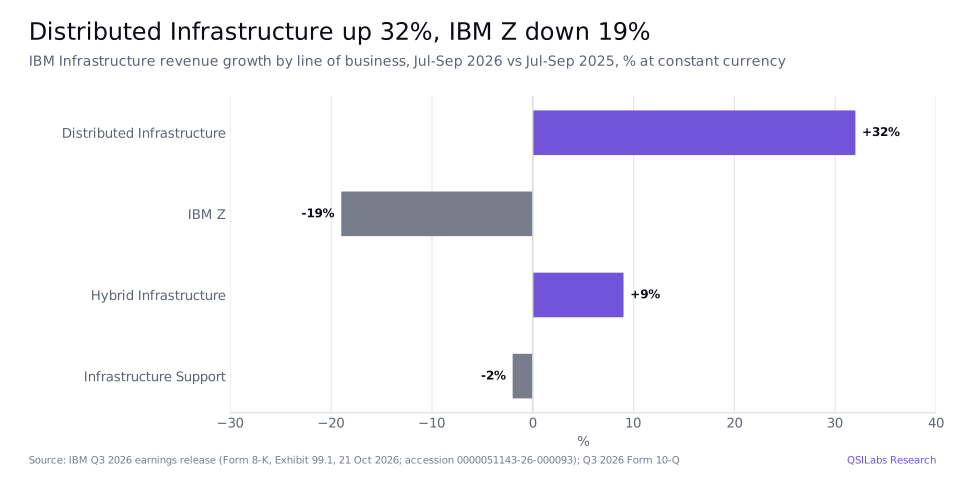
- Infrastructure: Distributed Infrastructure (storage and Power servers) grew 32% at constant currency, while IBM Z mainframe revenue fell 19% against a strong year-earlier launch quarter. IBM says Storage delivered record revenue growth.
- Outlook: IBM still expects 2026 revenue growth of 4-5% at constant currency, with profit and cash anchored to a 4% base case, and now expects 2026 free cash flow to rise by more than $1bn from $14.7bn.
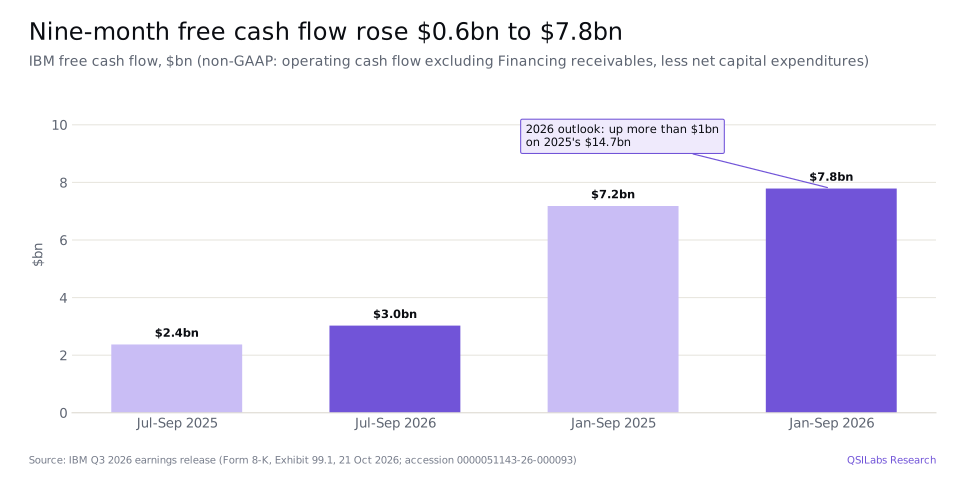
- Cash and returns: free cash flow was $3.0bn in the quarter, up $0.7bn, and $7.8bn in the first nine months, up $0.6bn. IBM paid $4.8bn of dividends in the nine months, declared a $1.69 quarterly dividend and bought back no shares.
Key numbers from IBM's Q3 2026 earnings
| July-September, $m | 2025 | 2026 | Change |
|---|---|---|---|
| Revenue | 16,331 | 17,103 | +5% |
| Software revenue | 7,209 | 7,804 | +8% |
| Consulting revenue | 5,324 | 5,335 | 0% |
| Infrastructure revenue | 3,559 | 3,707 | +4% |
| Financing revenue | 200 | 192 | -4% |
| Gross profit margin (GAAP) | 57.3% | 56.8% | -0.5 pts |
| Pre-tax income (GAAP) | 2,430 | 2,497 | +3% |
| Operating pre-tax income (non-GAAP) | 3,033 | 3,295 | +9% |
| Net income | 1,744 | 2,190 | +26% |
| GAAP EPS from continuing operations, $ | 1.84 | 2.31 | +26% |
| Operating EPS (non-GAAP), $ | 2.65 | 2.95 | +11% |
| Free cash flow (non-GAAP) | 2,373 | 3,027 | +28% |
Source: IBM Q3 2026 earnings release (Form 8-K, Exhibit 99.1, 21 October 2026) and Form 10-Q. Operating (non-GAAP) figures exclude acquisition-related charges, non-operating retirement-related costs and U.S. tax reform impacts. Free cash flow is IBM's measure: operating cash flow excluding IBM Financing receivables, less net capital expenditures.
IBM Q3 2026 earnings: what happened
Revenue of $17.1bn was up 5% on the same quarter of 2025 and up 6% at constant currency, faster than the second quarter. Chief executive Arvind Krishna said growth "accelerated to 6%, above the base case we laid out in July" (IBM 3Q26 prepared remarks). All three main segments grew at constant currency: Software 9%, Infrastructure 5% and Consulting 2%.
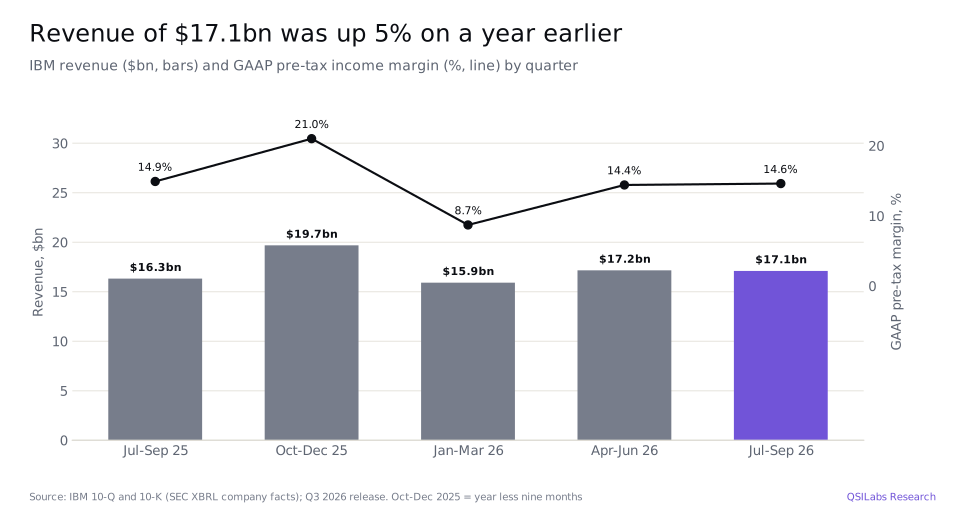
Profit grew faster than revenue on IBM's operating measures. The operating gross margin slipped 0.2 points to 58.5%, but the operating pre-tax margin rose 0.7 points to 19.3% as IBM cut general, administrative and sales costs; chief financial officer James Kavanaugh credited "productivity initiatives inside IBM". Adjusted EBITDA was $4.9bn, a 28.7% margin, up 0.6 points. On a GAAP basis the pre-tax margin fell 0.3 points to 14.6%, because acquisition-related charges after tax rose to $542m from $454m and non-operating retirement-related costs rose to $71m from $10m (IBM Q3 2026 Form 10-Q).
GAAP EPS rose 26% to $2.31, more than operating EPS, for a simple reason: a year earlier IBM booked a $309m charge for U.S. tax reform impacts, and this year it booked none. The GAAP effective tax rate was 11.9%, against 28.2%.
- 17 Mar 2026IBM completes its purchase of Confluent for $31 a share in cash, a total equity value of about $11.3bn10-Q
- 2 Jun 2026IBM closes at $329.23, its highest close of the past yearYahoo Finance
- 22 Jul 2026IBM closes at $205.77, its lowest close of the past yearYahoo Finance
- 14 Sep 2026Department of Commerce CHIPS award of up to $1bn to Anderon, IBM's quantum-wafer subsidiary, is finalized; the government takes a minority stake10-Q
- 30 Sep 2026Q3 2026 ends; IBM closes at $219.93Yahoo Finance
- 21 Oct 2026Q3 results after the market close: revenue $17.1bn, operating EPS $2.95, free cash flow outlook raised. IBM closes at $251.46 before the release8-K Ex 99.1; Yahoo Finance
- 22 Oct 2026Form 10-Q filed. IBM closes at $252.11, up 0.3%10-Q; Yahoo Finance
- 30 Oct 2026IBM closes at $257.81, the price used in our valuationYahoo Finance
- 10 Nov 2026Record date for the $1.69 quarterly dividend, payable 10 December8-K Ex 99.1
- 10 Dec 2026IBM Quantum DayIBM 3Q26 prepared remarks
How did IBM's segments do in Q3 2026?
Software
Software revenue was $7,804m, up 8%, or 9% at constant currency, and segment profit rose 15% to $2,734m. IBM said the 9% included more than 4 points of organic growth; the rest came from acquisitions such as Confluent. By line of business, at constant currency:
- Hybrid Cloud (Red Hat): up 11%, with bookings growth back in the high teens. OpenShift, Red Hat's container platform, is now a $2.4bn annual recurring revenue (ARR) business growing more than 30%, and IBM has signed nearly $800m of virtualization contracts since early 2024.
- Data: up 20% (19% as reported), driven by Confluent, the data-streaming company IBM bought for about $11.3bn of equity value.
- Transaction Processing: up 10%. This is the mainframe software that runs core banking and payment systems, and the quarter included large deals that slipped out of the second quarter.
- Automation: down 3% against a strong year earlier, despite growing bookings at HashiCorp.
Software ARR was $24.9bn, up about $2bn from a year earlier. IBM now expects full-year Software growth of about 7-8%, with about 7% as its revised base case.
Infrastructure
Infrastructure revenue was $3,707m, up 4%, or 5% at constant currency, and segment profit rose 11% to $715m, a 19.3% margin. The mix inside it moved sharply. Distributed Infrastructure, which is storage and Power servers, grew 32% at constant currency; IBM's own description is that "Storage delivered record revenue growth" and gained market share. IBM Z revenue fell 19% at constant currency, which IBM attributes to product cycle dynamics: the z17 mainframe launched in June 2025, so the year-earlier quarter was a strong one. IBM says z17 is more than $1bn of revenue ahead of the previous mainframe programme at the same point and had the strongest midrange launch in IBM Z in nearly two decades. Infrastructure Support fell 2%.
Consulting
Consulting revenue was $5,335m, flat as reported and up 2% at constant currency. Strategy and Technology grew 4% at constant currency and Intelligent Operations was flat. Signings were $5,030m in the quarter, down 2.0% at constant currency, and $15.4bn in the nine months, up 3.1%; the trailing twelve-month book-to-bill ratio was about 1.04 and the backlog $30.2bn. IBM says AI work was about 30% of Consulting revenue in the quarter and 35% of its backlog. The segment profit margin fell to 12.2% from 12.9% because IBM is spending part of its productivity savings on reusable software assets for consulting work.
Financing
IBM Financing, which lends to clients buying IBM products, had revenue of $192m, down 4%, and pre-tax profit of $108m, against $123m.
IBM's 2026 outlook after the third quarter
IBM's full-year expectations after the third quarter, from the earnings release and prepared remarks:
| 2026 expectation | After Q3 2026 |
|---|---|
| Revenue growth at constant currency | 4-5% (profit and cash anchored to a 4% base case); currency about neutral |
| Software revenue growth | about 7-8% (base case about 7%) |
| Infrastructure revenue growth | low single digits |
| Consulting revenue growth | low-to-mid single digits |
| Operating pre-tax margin | up about 1 point |
| Operating tax rate | mid-teens |
| Free cash flow | up more than $1bn from $14.7bn in 2025 |
Source: IBM Q3 2026 earnings release and 3Q26 prepared remarks (21 October 2026); 2025 free cash flow from the 2025 Form 10-K.
The revenue range implies a wide fourth quarter. IBM's 2025 revenue was $67,535m, so 4-5% growth means $70.2-70.9bn for 2026. After $50,182m in the first nine months (up 4.9%), the fourth quarter needs $20.1-20.7bn, against $19,686m a year earlier, or growth of about 2-5%. IBM's 4% base case sits at the bottom of that, while the faster Software growth in the third quarter points higher. Free cash flow of more than $15.7bn for the year implies more than $7.9bn in the fourth quarter, after $7.8bn in the first nine months.
Analysts' consensus, compiled by S&P Global, puts 2026 revenue at $70.57bn and adjusted EPS at $12.42, and 2027 revenue at $73.24bn (up 3.8%) and adjusted EPS at $13.24 (StockAnalysis).
IBM cash flow, debt and the dividend
IBM generated $4.0bn of operating cash in the third quarter, up $0.9bn, and $3.0bn of free cash flow, up $0.7bn. For the nine months, operating cash flow was $11.8bn, up $2.6bn, and free cash flow $7.8bn, up $0.6bn. IBM says its free cash flow realization, free cash flow relative to net income, has been about 130% over the last few years.
Buying Confluent cost cash and added debt. IBM spent $11.4bn on acquisitions in the first nine months; the Confluent purchase, completed on 17 March 2026 at $31 a share, had a total consideration of $11.6bn and added $7.2bn of goodwill. Cash, restricted cash and marketable securities fell $3.4bn in the nine months to $11.1bn, and total debt rose $2.6bn to $63.8bn, of which $12.7bn is IBM Financing debt backed by client receivables. Goodwill reached $74.9bn.
IBM pays a quarterly dividend of $1.69 a share, payable on 10 December 2026 to holders of record on 10 November. That is $6.76 a year, a yield of 2.6% at $257.81. IBM says that with the December payment it will have paid consecutive quarterly dividends every year since 1916. It paid $1.6bn of dividends in the third quarter and $4.8bn in the nine months, and it has not bought back shares since it completed the Red Hat acquisition in 2019.
Quantum computing does not show up in the numbers yet, but IBM is spending on it. In September the Department of Commerce finalized a CHIPS award of up to $1bn to Anderon, an IBM subsidiary that will make quantum wafers; IBM is contributing $1bn and the government holds a minority equity interest, which appears as a $669m noncontrolling interest on IBM's balance sheet. DARPA selected IBM for Stage C of its Quantum Benchmarking Initiative, and IBM holds a Quantum Day on 10 December.
IBM stock Q3 2026 valuation: how our DCF compares with the price
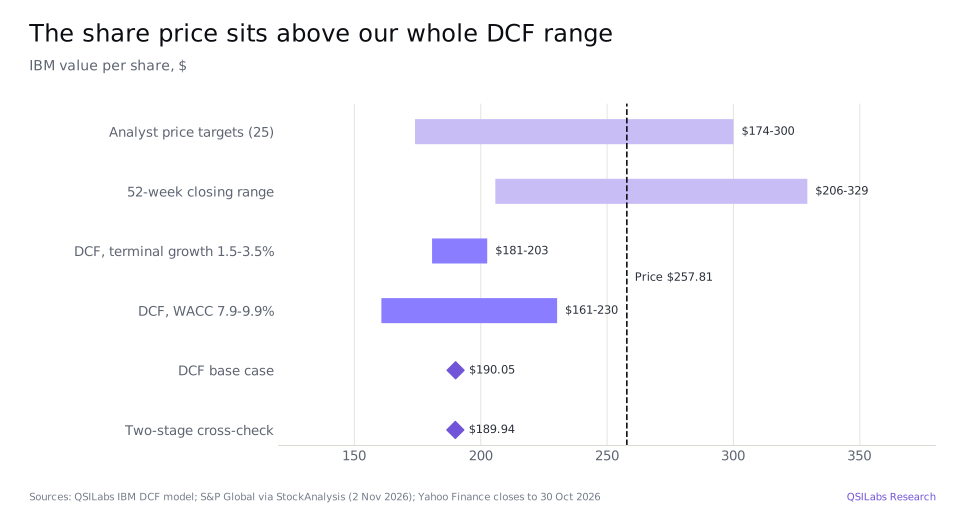
Our base case puts IBM at $190.05 a share, against $257.81 at the 30 October close and $252.51 on 2 November. The stock trades at about 20.8 times consensus 2026 adjusted EPS and 19.5 times 2027, and at a free cash flow yield of about 6.4% on IBM's 2026 outlook. Analysts are more positive than we are: 25 analysts rate it a Buy on average, with a mean price target of $259.30 and a range of $174-300.
Method
We discount IBM's free cash flow to the firm for 2026-2035 at a weighted average cost of capital (WACC) of 8.94%, the January 2026 figure for computer services companies from Aswath Damodaran at NYU Stern, and add a terminal value growing at 2.5% a year. A bottom-up check on IBM's own capital structure gives 9.17%. Cash flows are discounted from the middle of each year.
Our revenue path follows sources rather than a straight line:
| Year | Revenue growth | Basis |
|---|---|---|
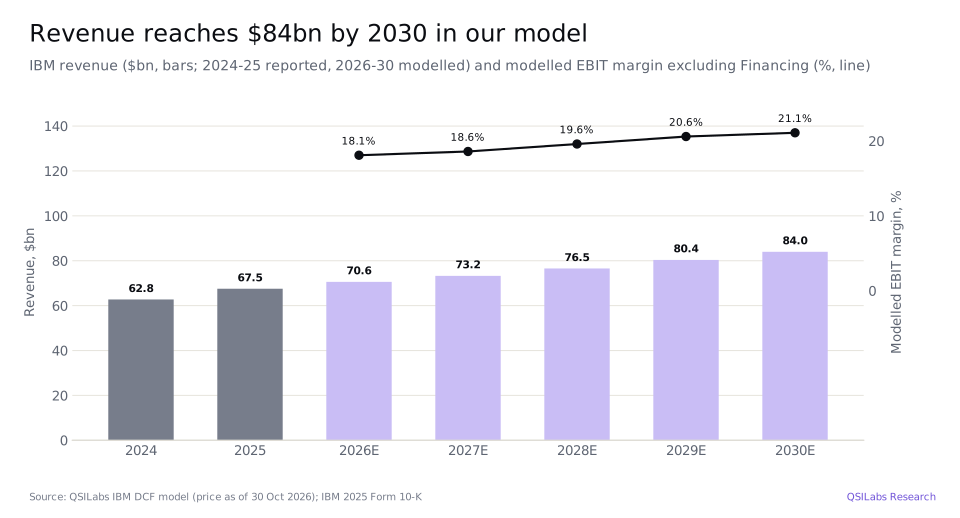
| 2026 | 4.5% | IBM outlook of 4-5% at constant currency (midpoint); consensus $70.57bn |
| 2027 | 3.8% | Consensus revenue of $73.24bn |
| 2028 | 4.5% | Halfway between consensus and IBM's model |
| 2029 | 5.0% | IBM's Investor Day model of 5%+ sustainable revenue growth |
| 2030-2035 | 4.5% falling to 2.5% | Fade of about half a point a year to terminal growth |
IBM's medium-term model, set out at its February 2025 Investor Day, is 5% or more revenue growth a year, about 10% Software growth and about 1 point of operating pre-tax margin expansion a year (IBM Investor Day 2025). The market backdrop supports growth at that level: Gartner forecasts worldwide software spending to grow 14.6% in 2027 and IT services 4.9% (Gartner).
The other main assumptions:
- Margins: GAAP operating profit (EBIT) excluding IBM Financing of 18.1% of revenue in 2026 (nine months reported plus consensus for the fourth quarter), 18.6% in 2027 (in line with consensus EPS growth), then about 1 point a year to 20.6% in 2029, per IBM's model, and 21.4% from 2031. GAAP EBIT is lower than IBM's operating measure because it carries acquisition amortization.
- Tax: 17% on operating profit, a little above IBM's mid-teens operating tax rate.
- Investment: capital spending, including capitalized software, of $2.2bn in 2026, rising over time so that by 2035 net investment matches what 2.5% growth requires at a 15% return on new capital.
- Free cash flow to the firm: $14.7bn in 2026, rising to $16.7bn in 2030 and easing to $15.2bn by 2035 as investment rises. This is not the same as IBM's own free cash flow measure: it is before interest, after our notional tax, and excludes IBM Financing.
- Bridge to equity: we subtract all $63.8bn of interest-bearing debt, including IBM Financing's, and add back the $13.3bn of Financing receivables that debt funds. Financing profit is left out of the cash flows so it is not counted twice.
| Enterprise value to equity, $m | Amount |
|---|---|
| Present value of 2026-2035 free cash flow | 100,700 |
| Present value of terminal value | 119,633 |
| Enterprise value | 220,333 |
| Plus cash and marketable securities | 11,058 |
| Less total debt, including IBM Financing's 12,652 | -63,817 |
| Plus IBM Financing receivables, at book | 13,256 |
| Less noncontrolling interest (Anderon) | -669 |
| Plus cash generated 30 September to 30 October, less interest | 1,055 |
| Equity value | 181,216 |
| Diluted shares, millions | 953.5 |
| Value per share | $190.05 |
Source: QSILabs IBM DCF model; balance sheet from the Q3 2026 Form 10-Q. The terminal value is 54% of enterprise value and implies 10.3 times terminal-year EBITDA. A two-stage version of the model gives $189.94.
How the number moves if you argue with us
| WACC \ terminal growth | 1.5% | 2.0% | 2.5% | 3.0% | 3.5% |
|---|---|---|---|---|---|
| 7.94% | $214.62 | $221.79 | $230.22 | $240.28 | $252.54 |
| 8.44% | $196.45 | $202.01 | $208.45 | $216.01 | $225.03 |
| 8.94% | $180.74 | $185.08 | $190.05 | $195.81 | $202.56 |
| 9.44% | $167.04 | $170.45 | $174.31 | $178.73 | $183.84 |
| 9.94% | $154.98 | $157.67 | $160.69 | $164.10 | $168.00 |
Value per share, QSILabs IBM DCF model; WACC in rows, terminal growth in columns.
A point of WACC either way moves the value by about $30-40 a share, and every cell in the grid is below $257.81: the closest, a 7.94% WACC with 3.5% terminal growth, gives $252.54. Reaching the share price on our numbers takes a lower cost of capital than that, or faster growth and wider margins than IBM's own medium-term model. That is possible if Software keeps growing near 10% and the margin keeps widening by a point a year beyond 2029, but it is not our base case.
Risks to the IBM investment case
- Upside: Software compounding. If Red Hat, OpenShift and Confluent keep Software growth near IBM's 10% medium-term target, Software becomes a larger share of the mix and margins keep rising. That is the main way our value would be too low.
- Mainframe cycle. IBM Z revenue swings with product launches. z17 is now in its second year, and the next fall in mainframe revenue would weigh on Infrastructure and on Transaction Processing software.
- Consulting. Signings fell 2% at constant currency in the quarter and the margin narrowed. Consulting is labor-intensive and exposed to cuts in client budgets.
- Acquisitions and debt. IBM has spent heavily on Red Hat, Apptio, HashiCorp and Confluent; goodwill is $74.9bn and debt $63.8bn. Integration problems or impairments would hurt, and higher rates would raise IBM's interest cost.
- AI competition. Enterprise AI software and services are contested by the largest cloud providers and AI labs. IBM's partnerships, including a new one with OpenAI, do not guarantee it keeps its share.
- Pensions. IBM's retirement-related plans are large; we do not deduct the net deficit because after tax it is under 1% of enterprise value, but market moves can change that.
- Valuation. At about 21 times 2026 earnings, the stock already prices in more growth than our model; any slowdown in Software would hit a stock priced that way.
FAQ
What is QSILabs' value for IBM stock after Q3 2026 earnings?
QSILabs values IBM at $190.05 per share using a discounted cash flow model with an 8.94% WACC and 2.5% terminal growth, as of results for the quarter ended 30 September 2026. That is about 26% below the $257.81 close on 30 October 2026. Our sensitivity range across WACCs of 7.9-9.9% is about $161-230.
Is IBM stock a buy after its Q3 2026 results?
We do not give buy or sell recommendations. On our model the shares trade above our estimate of the value of IBM's future cash flows, even with generous assumptions. Analysts disagree: 25 analysts rate IBM a Buy on average, with a mean target of $259.30. The answer depends on how fast you think Software can grow beyond 2027.
How much did IBM earn in the third quarter of 2026?
IBM earned net income of $2,190m in the third quarter of 2026, or $2.31 a diluted share from continuing operations, up 26%. On its operating (non-GAAP) basis it earned $2,812m, or $2.95 a share, up 11%, on revenue of $17,103m.
Why did IBM Z mainframe revenue fall when IBM says z17 is doing well?
IBM Z revenue fell 19% at constant currency because the year-earlier quarter included strong early sales of the z17 mainframe, launched in June 2025. Mainframe revenue moves in cycles that follow launches. IBM says z17 sales are more than $1bn ahead of the previous programme at the same point.
How much did IBM pay for Confluent?
IBM paid $31 a share in cash for Confluent, completing the deal on 17 March 2026. The total consideration was $11.6bn, of which $7.2bn was recorded as goodwill. Confluent's data-streaming products are part of IBM's Data business, which grew 20% at constant currency in the third quarter.
What is IBM's dividend yield?
IBM pays a quarterly dividend of $1.69 a share, or $6.76 a year, a yield of about 2.6% at the 30 October 2026 price of $257.81. The next payment is on 10 December 2026 to holders of record on 10 November. IBM has paid a quarterly dividend every year since 1916 and does not currently buy back shares.
How did IBM shares react to the Q3 2026 results?
IBM reported after the market closed on 21 October 2026, when the shares closed at $251.46. They rose 0.3% to $252.11 on 22 October and closed at $257.81 on 30 October. That was 15.4% below the $304.73 close of 3 November 2025 and 21.7% below the 52-week closing high of $329.23 on 2 June 2026.
How much free cash flow does IBM expect in 2026?
IBM expects 2026 free cash flow to rise by more than $1bn from $14.7bn in 2025, which means more than $15.7bn. It generated $7.8bn in the first nine months, so the fourth quarter, IBM's strongest, needs more than $7.9bn.
What is Anderon?
Anderon LLC is an IBM subsidiary set up to manufacture quantum computing wafers. On 14 September 2026 the U.S. Department of Commerce finalized a CHIPS award of up to $1bn to it, $650m at closing and $350m on milestones; IBM is contributing $1bn and the government holds a minority equity stake.
Sources
- IBM, third-quarter 2026 earnings release (Form 8-K, Exhibit 99.1, 21 Oct 2026; accession 0000051143-26-000093) www.sec.gov
- IBM, Form 10-Q for the quarter ended 30 Sep 2026 (filed 22 Oct 2026; accession 0000051143-26-000095) www.sec.gov
- IBM, 3Q26 earnings prepared remarks (21 Oct 2026) www.ibm.com
- IBM, Form 10-K for 2025 (accession 0000051143-26-000010) www.sec.gov
- IBM, Form 10-Q for the quarter ended 30 Jun 2026 (accession 0000051143-26-000078) www.sec.gov
- IBM, Investor Day 2025 presentation (Form 8-K, Exhibit 99.1, 12 Feb 2025; accession 0000051143-25-000010) www.sec.gov
- SEC XBRL company facts: IBM quarterly revenue and pre-tax income data.sec.gov
- StockAnalysis: IBM forecast and analyst ratings, S&P Global data (page updated 27 Oct 2026, accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: IBM statistics (accessed 2 Nov 2026) stockanalysis.com
- Gartner, worldwide IT spending forecast press release (21 Oct 2026) www.gartner.com
- Yahoo Finance chart data: IBM closing prices and dividends (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry, computer services (January 2026) pages.stern.nyu.edu
- QSILabs IBM DCF model (internal; price as of 30 Oct 2026)
Disclaimer
This article is for information only and is not investment advice or a recommendation to buy or sell any security. QSILabs estimates are opinions based on public information and our own model, and they may be wrong. Figures are as of the dates stated. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Microsoft stock Q3 2026: earnings and valuation, Oracle stock Q3 2026: OCI, RPO and capex and Cisco stock Q3 2026: AI networking orders.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.