Research / Earnings and valuation
CrowdStrike Stock Q3 2026:Record Net New ARR and Revenue Up 26%
As of: Figures are as of CrowdStrike's fiscal Q2 FY2027 results (the quarter ended 31 July 2026, reported 26 August 2026 in a Form 8-K) and its Form 10-Q for that quarter, filed 27 August 2026. CrowdStrike's fiscal year ends on 31 January, so fiscal Q2 FY2027 covers May to July 2026; its fiscal Q3, August to October 2026, is due to be reported in early December. Share figures are adjusted for the 4-for-1 stock split of July 2026. The share price used in our valuation is the Nasdaq close of CRWD on 30 October 2026, $250.43; analyst data were accessed on 2 November 2026. Published 2 November 2026.
The short answer. CrowdStrike stock Q3 2026 rests on the company's fiscal Q2 FY2027, the quarter to 31 July 2026, its latest reported results. Revenue rose 26% to $1.47bn, annual recurring revenue (ARR) rose 25% to $5.84bn and net new ARR rose 51% to $333m, which the company called a record. Accounts using Falcon Flex, its flexible enterprise licensing model, had more than $2.29bn of ending ARR, up 101%. On a non-GAAP basis the operating margin was 25%, but after $399m of stock-based compensation and related payroll taxes CrowdStrike still made a GAAP operating loss of $33m. Our discounted cash flow model values CRWD at $39.02 a share, against a $250.43 close on 30 October 2026. The business is growing quickly and producing cash; the share price assumes far more growth and much higher margins after stock pay than we forecast.
Key takeaways
- Revenue up 26%. Fiscal Q2 FY2027 revenue was $1,470.9m, up from $1,169.0m a year earlier and $1,385.6m in the April quarter. Subscription revenue rose 27% to $1,400.3m.
- ARR growth is speeding up. Ending ARR was $5,841.4m, up 25%. Net new ARR was $332.8m, up 51% from $221.1m, the company's best quarter on that measure.
- Falcon Flex is spreading. Ending ARR from accounts that have adopted Falcon Flex exceeded $2.29bn, up 101%. Half of subscription customers (51%) now use six or more modules.
- Two profit pictures. Non-GAAP operating income rose 46% to $371.6m, a 25% margin. GAAP operating loss narrowed to $33.2m from $105.5m, because stock-based compensation and related payroll taxes rose 44% to $399.0m, 27% of revenue.
- Cash flow rose. Operating cash flow was $530.3m and free cash flow $377.4m, both second-quarter records according to the company, against $332.8m and $283.6m a year earlier. Cash was $5.01bn against $746m of debt.
- Guidance raised. For fiscal 2027, to 31 January 2027, CrowdStrike expects revenue of $5.99bn to $6.01bn, ending ARR of $6.60bn to $6.61bn and non-GAAP EPS of $1.25 to $1.26. It raised its net new ARR growth outlook by 6.3 points to 34% at the midpoint.
- Our value: $39.02 a share, about 84% below the $250.43 close on 30 October 2026. A two-stage cross-check gives $41.45; analysts' average target is $248.45.
- What to watch. Fiscal Q3 results, expected in early December; whether net new ARR keeps growing faster than ARR; and whether stock-based compensation starts to fall as a share of revenue.
Key numbers from CrowdStrike's Q2 FY2027 earnings
| Metric | Q2 FY2027 (Jul 2026) | Q2 FY2026 (Jul 2025) | Change |
|---|---|---|---|
| Revenue | $1,470.9m | $1,169.0m | +26% |
| Subscription revenue | $1,400.3m | $1,102.9m | +27% |
| Ending ARR | $5,841.4m | $4,656.7m | +25% |
| Net new ARR | $332.8m | $221.1m | +51% |
| GAAP subscription gross margin | 78% | 77% | +1 pt |
| GAAP operating income (loss) | -$33.2m | -$105.5m | Loss narrowed |
| Non-GAAP operating income | $371.6m | $255.0m | +46% |
| Non-GAAP operating margin | 25% | 22% | +3 pts |
| Stock-based compensation and payroll tax | $399.0m | $276.7m | +44% |
| GAAP diluted EPS | $0.01 | -$0.07 | n/m |
| Non-GAAP diluted EPS | $0.31 | $0.23 | +35% |
| Operating cash flow | $530.3m | $332.8m | +59% |
| Free cash flow | $377.4m | $283.6m | +33% |
| Cash and cash equivalents (period end) | $5,013.8m | $5,230.1m (31 Jan 2026) | -4% |
CrowdStrike Q2 FY2027 earnings: what happened
CrowdStrike, the Austin, Texas cybersecurity company best known for its Falcon platform for protecting computers, cloud workloads and user identities, reported results for its fiscal second quarter, the three months to 31 July 2026, on 26 August, and filed its Form 10-Q the next day. Its fiscal year ends on 31 January, so fiscal Q2 FY2027 covers May to July 2026. Its fiscal Q3, which lines up most closely with calendar Q3, ended on 31 October and has not yet been reported; the Q2 results are the latest available.
Revenue was $1,470.9m, up 6.2% from $1,385.6m in the April quarter and 25.8% from $1,169.0m a year earlier. Year-on-year growth has risen in each of the last six quarters, from 19.8% in Q1 FY2026 to 25.6% in Q1 FY2027 and 25.8% in Q2. Subscription revenue, almost all of the total, was $1,400.3m, up 27%; professional services, mainly incident response and consulting, brought in $70.6m.
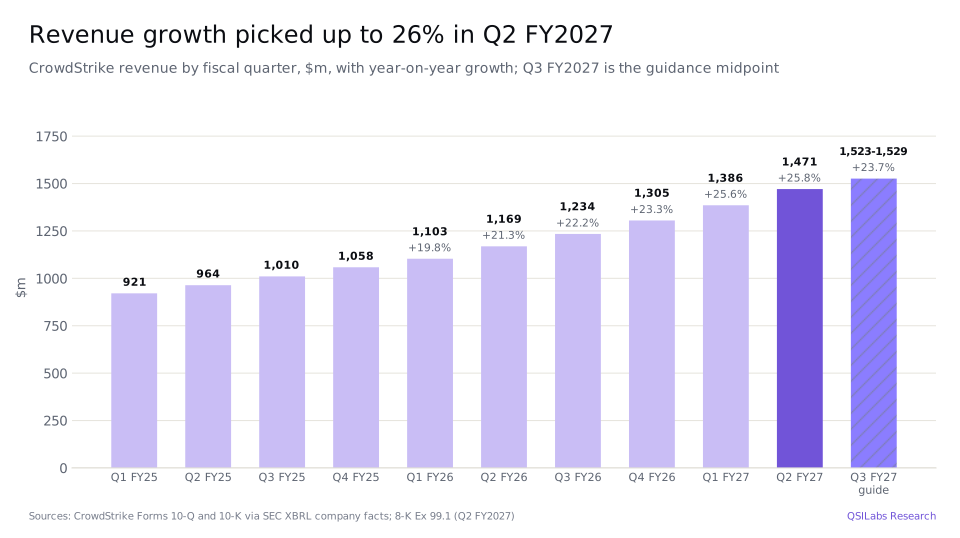
"Q2 was the best quarter in CrowdStrike's history," chief executive George Kurtz said in the results release. "Every enterprise will run on AI, and securing it is the largest market opportunity in our history." Chief financial officer Burt Podbere called it "a record-breaking quarter", pointing to record net new ARR, record net new ARR from new customers, higher dollar-based gross and net retention rates and record second-quarter cash flow.
Costs grew more slowly than revenue. Total GAAP gross margin was 75%, against 74% a year earlier. Operating expenses rose 17% to $1,130.1m: sales and marketing rose 14% to $510.0m, research and development rose 30% to $444.2m and general and administrative costs were flat at $176.0m. The GAAP operating loss narrowed to $33.2m, or 2.3% of revenue, from $105.5m, or 9.0%.
Interest income of $43.9m on the company's cash pile turned that operating loss into a small pre-tax profit, and a tax benefit left GAAP net income attributable to CrowdStrike at $5.3m, or $0.01 a diluted share, against a loss of $70.2m a year earlier. Non-GAAP net income, which excludes stock-based compensation and other items, was $322.9m, or $0.31 a share, against $0.23. The quarter also included a $14.5m net recovery of costs related to the July 2024 outage, against $35.7m of costs a year earlier.
- 31 Jan 2026Fiscal 2026 ends: revenue $4.81bn (+22%), GAAP operating loss $293m; the secured revolving credit facility had expired in JanuarySEC XBRL (Form 10-K); Form 10-Q
- 3 Feb 2026Acquires Seraphic, a browser security company, for $327.5m in cashForm 10-Q
- 20 Feb 2026Acquires SGNL, an identity security company, for $627.9m in cashForm 10-Q
- 24 Feb 2026CRWD closes at $87.56 (split-adjusted), its 52-week closing lowYahoo Finance
- 6 Apr 2026Board adds $500m to the share repurchase programme, taking it to $1.5bnForm 10-Q
- 1 Jul 20264-for-1 stock split takes effect after the closeForm 10-Q
- Jul 2026Agrees to buy the technology assets of XM Cyber for $145m in cash and stock, plus further sharesForm 10-Q
- 31 Jul 2026Fiscal Q2 FY2027 ends: revenue $1,471m (+26%), ARR $5.84bn, net new ARR $333m8-K Ex 99.1
- 26 Aug 2026Q2 results; full-year net new ARR growth outlook raised to 34% at the midpoint8-K Ex 99.1
- 27 Aug 2026Form 10-Q filed; CRWD closes at $227.96, up 20.5% on the dayForm 10-Q; Yahoo Finance
- 6 Oct 2026CRWD closes at $278.86, its 52-week closing highYahoo Finance
- 30 Oct 2026CRWD closes at $250.43 on Nasdaq, the price used in our valuationYahoo Finance
- 2 Nov 2026CRWD closes at $241.81; Deutsche Bank upgrades to Buy with a $300 targetYahoo Finance; StockAnalysis
- Early Dec 2026Fiscal Q3 FY2027 results (quarter to 31 October) expectedStockAnalysis
How fast is CrowdStrike's ARR growing?
Annual recurring revenue is the annualised value of CrowdStrike's subscription contracts at a point in time, and the company treats it as its main measure of growth. Ending ARR was $5,841.4m at 31 July 2026, up 25% from $4,656.7m a year earlier. Net new ARR, the increase in the quarter, was $332.8m, up 51% from $221.1m and up from $255.8m in the April quarter. For the first half, net new ARR was $588.6m, up 42% from $414.8m.
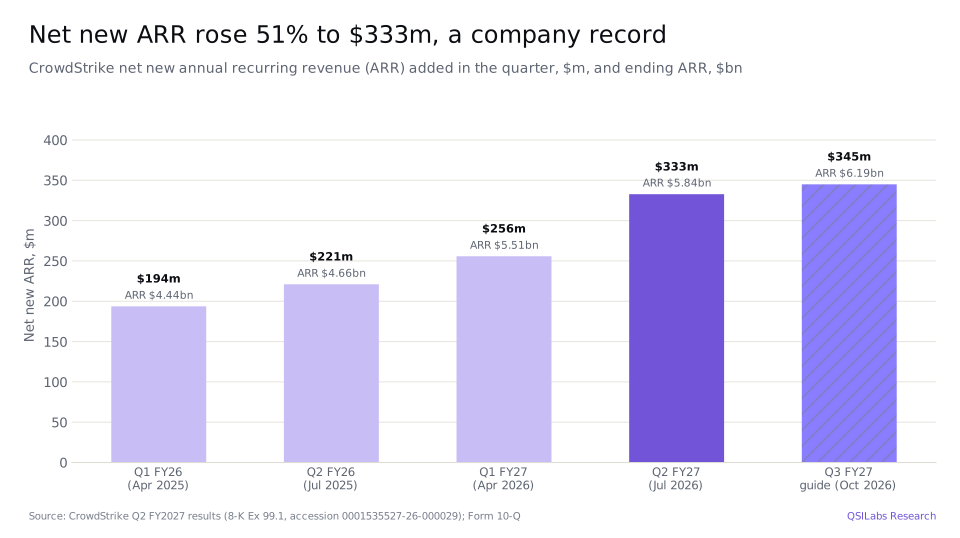
The acceleration matters because net new ARR leads revenue: ARR added now is recognised as subscription revenue over the following year or more. Faster net new ARR growth than ARR growth, 51% against 25%, means the base is likely to grow faster in future quarters if it continues. The guidance points that way. The midpoint of the Q3 ARR range, $6,186.4m, implies about $345m of net new ARR for the quarter, and the full-year midpoint of $6,607.5m implies about $1.35bn for fiscal 2027, which the company says is 34% growth. That would leave roughly $421m for the fourth quarter.
Other measures support the picture. Remaining performance obligations, the contracted revenue not yet recognised, were $10.7bn at 31 July, of which CrowdStrike expects to recognise about 46% in the next 12 months. Deferred revenue was $4.84bn. The 10-Q says the dollar-based net retention rate, which measures how much existing customers spend a year later, "improved sequentially", though the company did not give the figure.
What is Falcon Flex and why does it matter?
Falcon Flex is CrowdStrike's enterprise licensing model. Customers commit to a broad platform investment up front and then draw it down across products over time, shifting spend between security areas as their needs change, rather than buying each product on a separate contract. The 10-Q describes it as a key part of the company's enterprise strategy.
The company said ending ARR from accounts that have adopted Falcon Flex exceeded $2.29bn at 31 July, up 101% from a year earlier. That is about 39% of total ARR, so a large and growing share of the customer base now buys through Flex. Module adoption also rose: 51% of subscription customers used six or more modules, 35% seven or more and 26% eight or more.
Flex works by making it easier for a customer to try more products. That should lift spending per customer over time, but it also brings risks the 10-Q spells out: if customers do not fully use the products they commit to, their spending could fall at renewal, which would show up in the net retention rate in later periods.
CrowdStrike has also been buying its way into new areas. In February it paid $327.5m in cash for Seraphic, a browser security company, and $627.9m for SGNL, an identity security company; goodwill rose to $2.25bn from $1.36bn as a result. In July it agreed to buy the technology assets of XM Cyber, which maps attack paths through company networks, for $145m in cash and stock plus further shares to be set at closing.
Is CrowdStrike profitable?
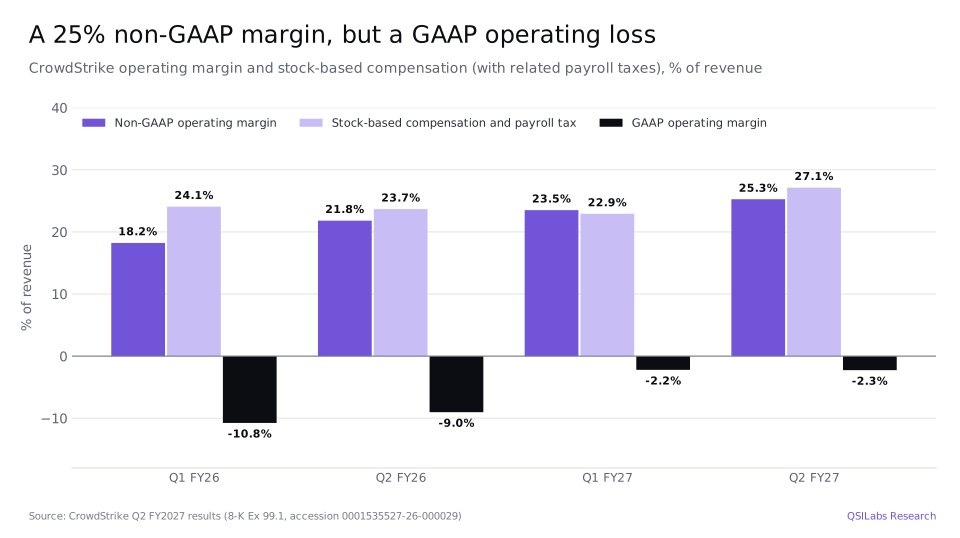
It depends on the measure. On the company's non-GAAP basis, which excludes stock-based compensation, related payroll taxes, amortisation of acquired intangibles, acquisition costs and outage-related items, operating income was $371.6m, a 25% margin, up from $255.0m and 22% a year earlier. On a GAAP basis, CrowdStrike made an operating loss of $33.2m.
Nearly all of the gap is stock pay. Stock-based compensation expense and related employer payroll taxes were $399.0m in the quarter, up 44% from $276.7m and equal to 27.1% of revenue, against 23.7% a year earlier. Research and development carried the most, $158.7m, followed by general and administrative at $96.1m and sales and marketing at $95.9m.
We think the GAAP figure is the more useful one for valuing the company. Stock awards are a real cost to shareholders: they replace cash pay and dilute existing owners. CrowdStrike's weighted average basic share count rose to 1,019.4m from 999.6m on a split-adjusted basis a year earlier, even after it spent $175.6m buying back 1.92m shares in the first half. StockAnalysis reports that shares outstanding grew 3.2% over the past year.
The trend is improving. The GAAP operating margin was -10.8% in Q1 FY2026 and -9.0% in Q2 FY2026, against -2.2% and -2.3% in the last two quarters, because non-GAAP margins have widened faster than stock pay. Fiscal 2026 as a whole ended with a GAAP operating loss of $293m on revenue of $4.81bn.
Where does CrowdStrike's revenue come from?
The United States supplied $954.5m of revenue in the quarter, 65% of the total, up 22% from $784.7m. International revenue grew faster. Europe, the Middle East and Africa rose 40% to $263.7m, 18% of the total; Asia Pacific rose 34% to $157.9m, 11%; and other regions rose 21% to $94.8m. No single country other than the US provided 10% or more of revenue.
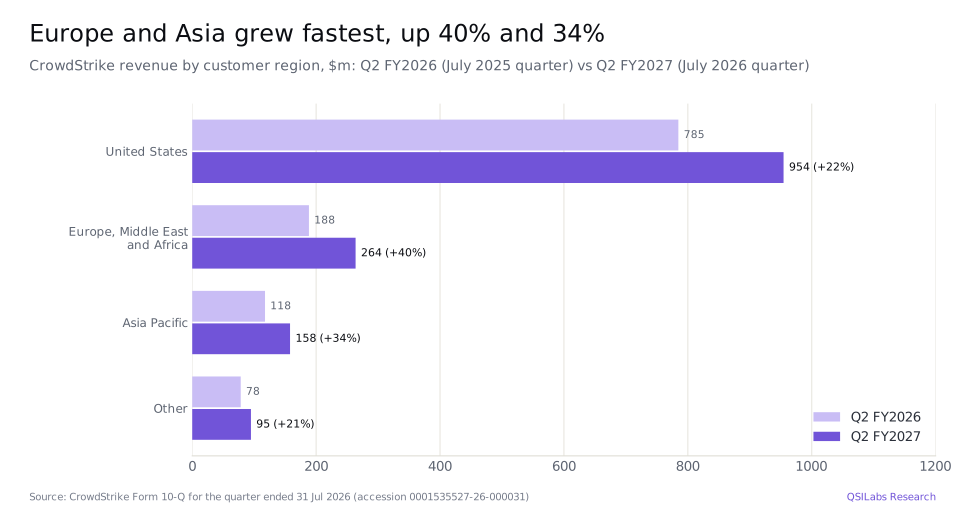
The faster growth abroad fits with the company's expanded partnership with Schwarz Digits, part of Germany's Schwarz Group, which it says will bring the Falcon platform to more European enterprises. The release also cites new work with Amazon Web Services and AI gateway partners including Databricks, Google Cloud and Microsoft Azure.
How much cash does CrowdStrike generate?
Operating cash flow was $530.3m in the quarter, up 59% from $332.8m, and free cash flow, after $124.4m of property and equipment purchases, $26.5m of capitalised software and small deferred compensation items, was $377.4m, up 33% from $283.6m. Capital spending rose to 8% of revenue from 3% a year earlier. For the first half, free cash flow was $845.9m, up 50%.
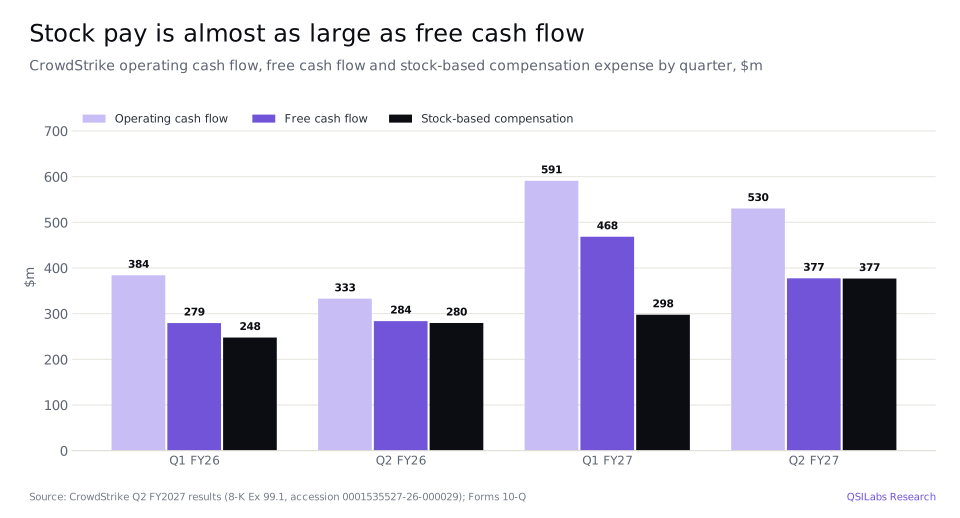
Free cash flow looks strong partly because customers pay in advance, so deferred revenue funds the business, and partly because stock-based compensation is not a cash cost. Stock-based compensation expense in the cash flow statement was $376.9m in the quarter, almost exactly equal to free cash flow. Across the four quarters in the chart below, the first two quarters of fiscal 2026 and of fiscal 2027, free cash flow totalled $1.41bn and stock-based compensation $1.20bn.
The balance sheet is strong. Cash and cash equivalents were $5,013.8m at 31 July, down from $5,230.1m at the end of January after $881.4m of acquisitions and $175.6m of buybacks in the first half. The only debt is $750m of 3.00% senior notes due in 2029, carried at $746.2m, so net cash was about $4.27bn. The company's secured revolving credit facility expired in January 2026. CrowdStrike pays no dividend; $1.3bn remained under its $1.5bn buyback authorisation at 31 July, and it made no repurchases in the second quarter.
What did CrowdStrike guide for Q3 and fiscal 2027?
For the quarter ending 31 October 2026, CrowdStrike expects:
- revenue of $1,523.2m to $1,529.2m;
- ending ARR of $6,184.4m to $6,188.4m;
- non-GAAP operating income of $372.7m to $375.9m;
- non-GAAP EPS of $0.31 on 1,048m diluted shares.
The revenue midpoint is 23.7% above the $1,234.2m of the October 2025 quarter and 3.8% above the July quarter, and implies a non-GAAP operating margin of about 24.5%.
For fiscal 2027, to 31 January 2027, it raised its guidance to revenue of $5,991.1m to $6,011.1m, ending ARR of $6,603.0m to $6,611.9m, non-GAAP operating income of $1,497.2m to $1,508.4m and non-GAAP EPS of $1.25 to $1.26, with a 21% non-GAAP tax rate. The revenue midpoint, $6.0bn, is 24.7% above fiscal 2026's $4.81bn; it implies about $1.62bn of revenue in the fourth quarter. Consensus forecasts compiled by S&P Global, as reported by StockAnalysis, are in line: $6.01bn of revenue and $1.26 of EPS for fiscal 2027, and $7.38bn and $1.61 for fiscal 2028.
CrowdStrike does not guide on GAAP operating income or stock-based compensation, saying the items are hard to predict.
Why did CrowdStrike stock jump after earnings?
CRWD closed at $189.18 on 26 August, the day of the results, and rose 20.5% the next day to $227.96, its biggest one-day gain of the past year. The company's filings do not explain share price moves; the results showed net new ARR accelerating sharply and a higher full-year net new ARR outlook, and we do not attribute the rise to any one cause. The shares kept rising to a 52-week closing high of $278.86 on 6 October, then eased to $250.43 by 30 October and $241.81 on 2 November.
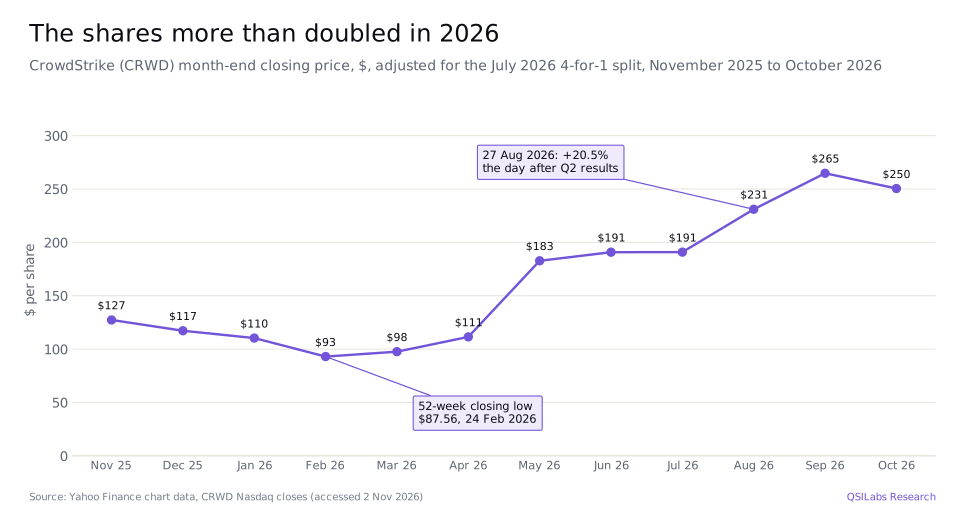
The rise has been steep. On a split-adjusted basis CRWD closed 2025 at $117.19 and fell to $87.56 on 24 February 2026; by 30 October it was up 114% for the year and 81% from $137.98 a year earlier. Daily moves of 7% or more happened 11 times in the past year, including a 12.1% gain on 14 July and a 13.9% gain on 14 September. The company completed a 4-for-1 stock split on 1 July 2026; all prices and per-share figures here are adjusted for it.
CrowdStrike stock Q3 2026: is CRWD overvalued?
On our numbers, yes, by a wide margin. Our discounted cash flow model values CrowdStrike at $39.02 a share, against a $250.43 close on 30 October 2026, about 84% lower. At that price the company's equity was worth about $257bn on 1,027m shares, and its enterprise value, after net cash of about $4.3bn, about $253bn. That is 42 times consensus fiscal 2027 revenue and 34 times fiscal 2028 revenue, about 199 times consensus fiscal 2027 non-GAAP EPS of $1.26 and 139 times the consensus fiscal 2027 free cash flow of $1.82bn.
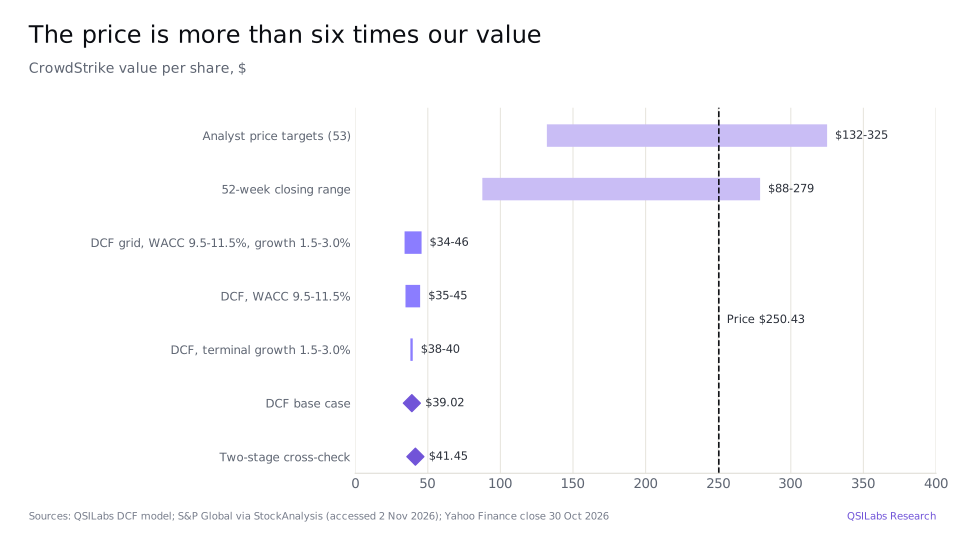
We are not saying the business is weak. CrowdStrike is growing revenue at 26%, ARR growth is accelerating and it turns about a quarter of revenue into free cash flow. We are saying the price assumes far more than our forecast: that revenue keeps growing well above 20% a year for much longer, that margins after stock pay end up well above those of mature security software companies, or that investors should discount the cash flows at a much lower rate. Holding our forecast fixed, the share price implies a cost of capital of about 3.8%, against our 10.5%.
Analysts are much more optimistic. The 53 analysts tracked by S&P Global rate CrowdStrike a Buy on average, with an average price target of $248.45, a median of $250 and a range from $132 to $325; 31 rate it Strong Buy, 10 Buy, 11 Hold and 1 Sell. Deutsche Bank upgraded the shares to Buy with a $300 target on 2 November, and Bank of America ($290, Hold), Mizuho ($275), KeyBanc ($265) and Citi ($295) raised their targets in October.
Method
We forecast revenue and operating margin year by year to fiscal 2036, apply a 21% tax rate, capital spending and working capital, and discount the cash flows at a 10.5% weighted average cost of capital. The cost of capital comes from Damodaran's January 2026 data for US system and application software companies: a beta of 1.28, a cost of equity of 10.81% and an after-tax cost of debt of 4.85%, with a 5.12% risk-free rate. A bottom-up check with a beta of 1.0 gives 10.1%. After fiscal 2036 we assume growth of 2.5% a year and a 15% return on new investment; that terminal value is 59% of our enterprise value of $35.7bn. Adding net cash and other small items gives equity value of $40.1bn, or $39.02 a share on 1,027.2m shares.
We treat stock-based compensation as an operating cost, as GAAP does, and so count only shares already issued rather than adding unvested awards. Our margin each year is the consensus non-GAAP operating margin less stock-based compensation and related payroll taxes, which gives -1.9% for fiscal 2027 and 4.4% for fiscal 2028. From there it rises steadily to 32.3% by fiscal 2035, close to the 33.1% median of established security software companies such as Check Point, Fortinet, Gen Digital, VeriSign and Akamai.
For revenue we use consensus: $6.01bn in fiscal 2027, up 25%, and $7.38bn in fiscal 2028, up 23%. Growth then slows by two points a year, to 20% in fiscal 2029, 16% in 2031, 10% in 2034 and 6% in 2036, when revenue reaches $19.5bn, more than three times this year's level.
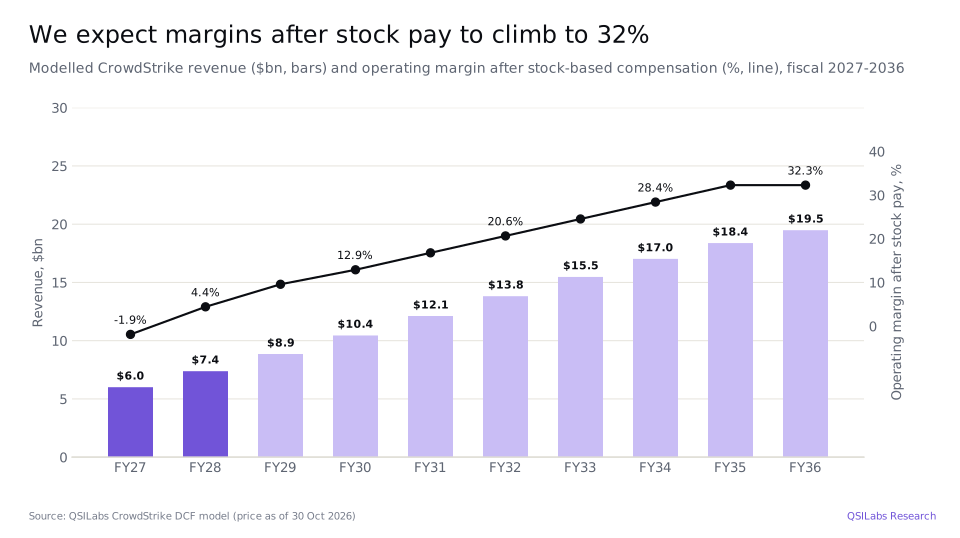
We forecast unlevered free cash flow of $443m in fiscal 2027, against the consensus free cash flow forecast of $1.82bn, rising to $952m in fiscal 2028 and about $4.5bn by fiscal 2035. Ours is lower mainly because we deduct stock-based compensation; the cash that customers prepay, which grows with revenue, adds back part of the difference.
How the number moves if you argue with us
The table shows our value per share at different costs of capital and terminal growth rates. Even at a 9.5% cost of capital and 3.0% terminal growth, the model reaches $45.71, less than a fifth of the share price.
| Cost of capital | Growth 1.5% | Growth 2.0% | Growth 2.5% | Growth 3.0% |
|---|---|---|---|---|
| 9.5% | $43.08 | $43.85 | $44.72 | $45.71 |
| 10.0% | $40.39 | $41.00 | $41.68 | $42.44 |
| 10.5% | $38.01 | $38.49 | $39.02 | $39.62 |
| 11.0% | $35.89 | $36.27 | $36.69 | $37.15 |
| 11.5% | $34.00 | $34.30 | $34.63 | $34.99 |
The bigger levers are how long growth lasts and how far stock pay falls as a share of revenue. If revenue kept growing above 20% for most of the decade, or stock-based compensation fell much faster than we assume, our cash flows would be materially higher. If investors instead judge the company on non-GAAP profit, ignoring the cost of stock awards, they will reach a much higher value than we do. To reach the share price with our cost of capital, the terminal value would need to be about 11 times what we assume.
Risks to the CrowdStrike investment case
- Valuation risk. At about 42 times this year's revenue and nearly 200 times non-GAAP EPS, the shares price in years of fast growth. The 20.5% one-day rise after the results, and frequent 7% daily moves, show how sharply the price can react to news.
- Stock-based compensation and dilution. Stock pay was 27% of revenue in the quarter and rose 44%. If it does not fall as a share of revenue, GAAP profits and per-share value will lag the non-GAAP figures.
- July 2024 outage. A faulty content update for the Falcon sensor on 19 July 2024 crashed many Windows systems. Lawsuits continue, including a Delta Air Lines case in which discovery is under way, and the 10-Q says the incident has led to longer sales cycles and customer commitment packages with discounts and extra modules.
- Regulatory inquiries. The 10-Q discloses requests for information from the US Department of Justice and the SEC relating to the company's recognition of revenue and reporting of ARR for transactions with certain customers, as well as the outage. The company says it is cooperating.
- Competition. CrowdStrike competes with Microsoft, Palo Alto Networks, SentinelOne and others across endpoint, cloud, identity and security data products. Bundling by larger software vendors could pressure prices.
- Falcon Flex and retention. Flex customers commit up front; if they do not use what they buy, renewals could shrink, and the 10-Q warns that incentives can reduce the net retention rate in later periods.
- Acquisition risk. CrowdStrike spent about $955m in cash on two deals in February and has another pending. Integrating them while growing headcount adds execution risk.
- Upside risk. If AI adoption drives a lasting rise in security spending, as the company's chief executive argues, and CrowdStrike keeps net new ARR growing above 30%, revenue and margins could beat our forecast and our value would rise.
FAQ
What value does QSILabs put on CrowdStrike stock?
QSILabs values CrowdStrike at $39.02 a share, based on a discounted cash flow model updated with fiscal Q2 FY2027 results and the Form 10-Q. That is about 84% below the $250.43 close on 30 October 2026. A two-stage cross-check gives $41.45; analysts' average price target is $248.45.
Is CrowdStrike stock a buy in Q3 2026?
Our model says CRWD trades far above what its cash flows justify once stock-based compensation is counted as a cost, because the price assumes much faster growth for much longer than we forecast. The business is strong: revenue up 26%, record net new ARR of $333m and $377m of free cash flow in the July quarter. This is not investment advice.
Why does a Q3 2026 article cover CrowdStrike's fiscal Q2 2027?
CrowdStrike's fiscal year ends on 31 January, so its fiscal Q2 FY2027 covers May to July 2026 and its fiscal Q3 covers August to October 2026. The fiscal Q3 results are not due until early December, so the Q2 results, reported on 26 August 2026, are the latest available for our Q3 2026 earnings series.
How much revenue did CrowdStrike make in its latest quarter?
CrowdStrike's revenue for fiscal Q2 FY2027, the quarter to 31 July 2026, was $1,470.9m, up 26% from $1,169.0m a year earlier and 6% from $1,385.6m in the April quarter. Subscription revenue was $1,400.3m and professional services $70.6m. It expects $1,523m to $1,529m in the October quarter.
What does CrowdStrike sell?
CrowdStrike sells cybersecurity software by subscription through its cloud-based Falcon platform. Products protect computers and servers (endpoint security), cloud workloads, user and AI-agent identities, browsers and security data (SIEM), and it sells incident response and other services. Customers can buy individual modules or commit up front through Falcon Flex.
What was the July 19 incident and is it still affecting CrowdStrike?
On 19 July 2024 CrowdStrike released a faulty content update for its Falcon sensor that crashed many Windows computers worldwide. Two years later it still faces lawsuits, including one from Delta Air Lines, and government inquiries. In the July 2026 quarter it recorded a $14.5m net recovery of related costs.
When does CrowdStrike report its next earnings?
CrowdStrike's fiscal Q3 FY2027 ended on 31 October 2026. StockAnalysis estimates that results will be reported on 1 December 2026; the company had not confirmed a date in its filings when we published. It has guided revenue of $1,523.2m to $1,529.2m and non-GAAP EPS of $0.31 for the quarter.
Does CrowdStrike pay a dividend?
No. CrowdStrike does not pay a dividend. It returns cash through buybacks instead: it bought back 1.92m shares for $175.6m in the first half of fiscal 2027, none of them in the July quarter, and had $1.3bn left under its $1.5bn authorisation at 31 July 2026.
What price target do analysts have for CrowdStrike?
The 53 analysts tracked by S&P Global, as reported by StockAnalysis on 2 November 2026, have an average price target for CrowdStrike of $248.45, a median of $250, a low of $132 and a high of $325, with a consensus rating of Buy. Our DCF value of $39.02 is far below all of them.
Why is CrowdStrike's GAAP profit so much lower than its non-GAAP profit?
Mainly because of stock-based compensation. In the July 2026 quarter, stock-based compensation and related payroll taxes were $399.0m, 27% of revenue. Non-GAAP figures exclude that cost, giving $371.6m of operating income, while GAAP figures include it, giving an operating loss of $33.2m.
Sources
- CrowdStrike Holdings, Inc., results for the second quarter of fiscal 2027, ended 31 Jul 2026 (Form 8-K, Exhibit 99.1, 26 Aug 2026; accession 0001535527-26-000029) www.sec.gov
- CrowdStrike Holdings, Inc., Form 10-Q for the quarter ended 31 Jul 2026 (filed 27 Aug 2026; accession 0001535527-26-000031) www.sec.gov
- SEC XBRL company facts for CrowdStrike (CIK 1535527): quarterly and annual revenue, operating income and cash flow from Forms 10-Q and the fiscal 2026 Form 10-K (accession 0001535527-26-000010) data.sec.gov
- StockAnalysis: CrowdStrike forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: CrowdStrike statistics (accessed 2 Nov 2026) stockanalysis.com
- Yahoo Finance chart data: CRWD closing prices, split-adjusted (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry (US), January 2026 pages.stern.nyu.edu
- QSILabs CrowdStrike discounted cash flow model (internal; price as of 30 Oct 2026)
Disclaimer
This article is for information only and is not investment advice, a recommendation or an offer to buy or sell any security. QSI Labs and its authors may hold positions in the securities discussed. Forecasts and valuations are estimates that depend on assumptions that may prove wrong. Figures are taken from company filings and third-party sources believed to be reliable, but we do not guarantee their accuracy. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Palo Alto Networks stock Q3 2026: NGS ARR and CyberArk, Microsoft stock Q3 2026, Palantir stock Q3 2026: AIP and Oracle stock Q3 2026: OCI and RPO.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.