Research / Earnings and valuation
Coca-Cola Stock Q3 2026:Volume Up 5% as Guidance Rises Again
As of: Figures are as of The Coca-Cola Company's Q3 2026 results (quarter ended 2 October 2026), reported on 27 October 2026 in its earnings release (Form 8-K, Exhibit 99.1) and in the Form 10-Q filed on 28 October 2026. The share price is the NYSE close of KO on 30 October 2026, $94.08. Published 2 November 2026.
The short answer. Coca-Cola stock Q3 2026 results were strong and broad: net revenues rose 7% to $13.4bn, organic revenues also grew 7%, unit case volume rose 5% and operating margin widened to 33.4% from 32.0%. Comparable EPS rose 11% to $0.91 and management raised its full-year guidance for the second time. Our discounted cash flow model puts The Coca-Cola Company at $55.88 per share, about 41% below the $94.08 close on 30 October 2026. The business is doing well; the price already assumes it keeps doing well for decades at a lower cost of capital than we use.
Coca-Cola's third quarter of 2026, the three months ended 2 October, was a volume quarter. Unit case volume grew 5%, led by India, China, Mexico and Brazil, and concentrate sales rose 7%, two points ahead of volume because of the timing of shipments to bottlers (Coca-Cola Q3 2026 earnings release). Price/mix added only 1%, so the growth came mostly from people buying more drinks rather than paying more for them. Net income attributable to shareowners was $4.01bn, or $0.93 a share, against $3.70bn, or $0.86, a year earlier (Form 10-Q). The shares fell 1.6% on results day, from $92.70 to $91.18, then rose to $94.08 by 30 October and are up 34.6% since the end of 2025 (Yahoo Finance).
In this article we go through the Q3 2026 numbers against a year earlier, segment by segment, the categories that drove volume, the raised guidance, the pending sale of the Africa bottling business, cash flow and the dividend, the IRS tax case, and our valuation of KO, with every assumption laid out so you can argue with it.
Key takeaways
- Valuation: QSILabs values The Coca-Cola Company (NYSE: KO) at $55.88 per share as of Q3 2026, against a $94.08 close on 30 October 2026, about 41% below the market price. Our value was $58.29 before the Form 10-Q, when the shares closed at $91.18 on 27 October.
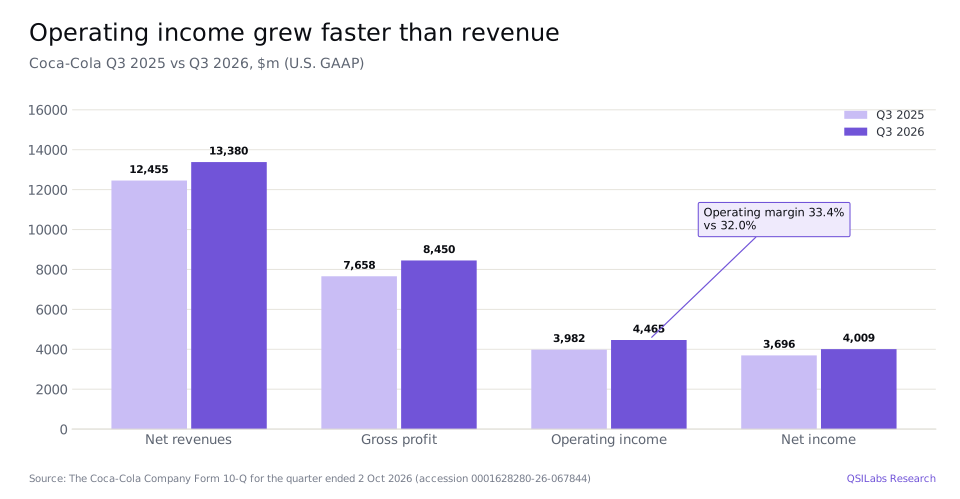
- Q3 2026 results: net operating revenues were $13,380m in the quarter ended 2 October 2026, up 7% from $12,455m; operating income was $4,465m, up 12%; EPS was $0.93, up 8%, and comparable EPS $0.91, up 11%, including a 2-point currency tailwind.
- Volume: global unit case volume grew 5%. Coca-Cola Zero Sugar grew 16%, Trademark Coca-Cola 5% and water 8%; North America volume was even while Latin America and Asia Pacific grew 6%.
- Guidance raised: full-year 2026 organic revenue growth is now at least 5%, comparable EPS growth at least 11% (from 9-10%) and free cash flow at least $13.0bn (from about $12.4bn).
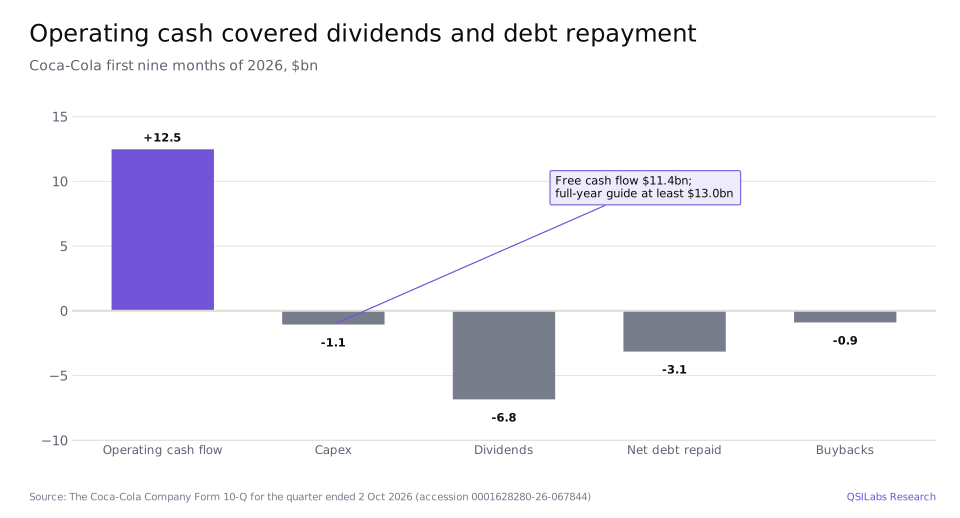
- Cash and returns: operating cash flow was $12.5bn and free cash flow $11.4bn in the first nine months; the quarterly dividend is $0.53 a share, a 2.3% yield at $94.08.
- What changes in 2027: the sale of part of Coca-Cola Beverages Africa to Coca-Cola HBC is expected to close by the end of 2026; the company expects it to cut 2027 revenue by about 8% but comparable EPS by only about 2%.
Key numbers from Coca-Cola's Q3 2026 earnings
| Q3 2026 vs Q3 2025, $m | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Net operating revenues | 12,455 | 13,380 | +7% |
| Gross profit | 7,658 | 8,450 | +10% |
| Selling, general and administrative expenses | 3,618 | 3,975 | +10% |
| Operating income | 3,982 | 4,465 | +12% |
| Equity income | 644 | 653 | +1% |
| Income before income taxes | 4,183 | 4,833 | +16% |
| Net income attributable to shareowners | 3,696 | 4,009 | +8% |
| Earnings per share, diluted ($) | 0.86 | 0.93 | +8% |
| Average diluted shares (m) | 4,313 | 4,314 | 0% |
Source: Coca-Cola Form 10-Q for the quarter ended 2 October 2026, condensed consolidated statements of income (accession 0001628280-26-067844). Gross margin was 63.2% against 61.5% a year earlier. Income taxes rose to $777m from $500m, so net income grew more slowly than pre-tax income.
Coca-Cola Q3 2026 earnings: what happened
Coca-Cola grew revenue, margin and earnings at once in Q3 2026. Net operating revenues rose $925m to $13,380m, gross profit rose $792m and operating income rose $483m to $4,465m. The company spent more on marketing and operating costs, with SG&A up 10% to $3,975m, but revenue growth and a currency tailwind more than covered it. Comparable operating margin, which strips out items such as restructuring charges, rose to 32.9% from 31.9%, and comparable currency-neutral operating income grew 8% (earnings release).
Below operating income the picture was mixed. Interest expense fell to $354m from $391m and interest income rose to $224m from $185m. Equity income from bottlers in which Coca-Cola owns stakes was $653m against $644m. Other income was a $155m loss against a $237m loss. The tax charge rose to $777m from $500m, an effective rate of 16.1% against 12.0%, which is why EPS grew 8% while operating income grew 12%.
For the first nine months, revenue was $39,232m, up 9%, operating income $13,496m, up 13%, and net income attributable to shareowners $12,358m, up 14%. Diluted EPS was $2.86 against $2.51 (10-Q). One caution on the nine-month comparison: the first quarter of 2026 had six more days than the first quarter of 2025, and the fourth quarter of 2026 will have six fewer days than the fourth quarter of 2025, so the full year evens out but the quarters do not (earnings release).
- 25 Jun 2026US Court of Appeals for the Eleventh Circuit hears Coca-Cola's appeal in its transfer-pricing case with the IRS10-Q
- 2 Oct 2026Third quarter ends; the company holds $13.7bn of cash and short-term investments and $41.6bn of debt10-Q
- Oct 2026Board approves the regular quarterly dividend of $0.53 a share, payable on 15 December to holders of record on 1 December10-Q
- 27 Oct 2026Q3 2026 results; full-year guidance raised; KO closes at $91.18, down 1.6% on the day8-K Ex 99.1; Yahoo Finance
- 28 Oct 2026Form 10-Q filed for the quarter ended 2 October 202610-Q
- 30 Oct 2026KO closes at $94.08, up 34.6% since the end of 2025Yahoo Finance
- By end-2026Expected closing of the sale of part of Coca-Cola Beverages Africa to Coca-Cola HBC, subject to regulatory approvals10-Q
How did each Coca-Cola segment do in Q3 2026?
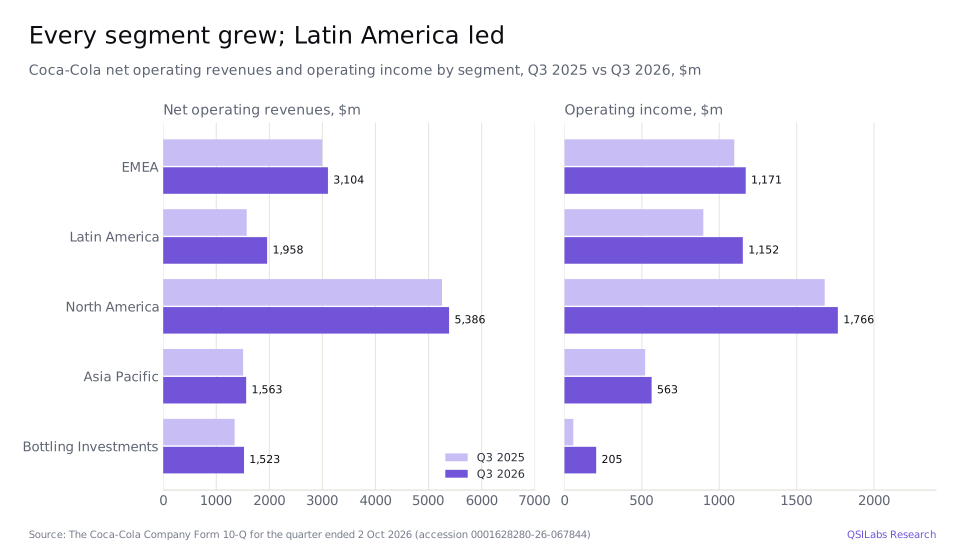
All five Coca-Cola operating segments grew revenue and operating income in Q3 2026. Latin America was the standout, with net revenues up 25% and operating income up 29%, helped by a large currency tailwind. North America, the biggest segment by revenue, grew more slowly: revenue rose 3% and operating income 5%.
Europe, Middle East and Africa
EMEA net revenues rose 4% to $3,104m and operating income 7% to $1,171m. Organic revenues grew 7% on 6% higher concentrate sales and 1% price/mix, but divestitures, chiefly the sale of finished product operations in Nigeria in the fourth quarter of 2025, took 3 points off reported growth. Unit case volume rose 5%, with Trademark Coca-Cola up 6% and water, sports, coffee and tea up 5% (10-Q).
Latin America
Latin America net revenues rose 25% to $1,958m: concentrate sales added 8 points, price/mix 7 points and currency 9 points. Organic revenues rose 16% and unit case volume 6%. Operating income rose 29% to $1,152m, a margin of 58.8%; excluding currency, comparable operating income grew 14%. Mexico's centenary campaign contributed to volume growth in the quarter (earnings release).
North America
North America net revenues rose 3% to $5,386m on 2% higher concentrate sales and 1% price/mix, with unit case volume even. Trademark Coca-Cola grew 2% while water, sports, coffee and tea fell 4% and sparkling flavors 2%. Operating income rose 5% to $1,766m (10-Q). North America is about 40% of segment revenue, so its flat volume is the main thing holding the group's growth below the international rate.
Asia Pacific
Asia Pacific net revenues rose 4% to $1,563m. Concentrate sales rose 8% and unit case volume 6%, but price/mix was minus 2 points and currency minus 3 points. Operating income rose 8% to $563m, and comparable currency-neutral operating income grew 14%.
Bottling Investments
Bottling Investments, which holds the bottlers Coca-Cola owns directly, mainly in India and Africa, grew net revenues 13% to $1,523m and unit case volume 8%. Operating income rose to $205m from $57m. This is the lowest-margin part of the group, at 13.5% in the quarter against 33-59% in the geographic segments, and it is the part that shrinks when the Africa sale closes.
What drove Coca-Cola's unit case volume in Q3 2026?
Volume growth in Q3 2026 came from sparkling drinks and water. Sparkling soft drinks grew 5%: Trademark Coca-Cola grew 5% and Coca-Cola Zero Sugar grew 16%, both with growth in every geographic segment, while Diet Coke and Coca-Cola Light grew 6% and sparkling flavors 3%. Water, sports, coffee and tea grew 5%, with water up 8% but sports drinks down 3% on a decline in Asia Pacific. Juice, value-added dairy and plant-based drinks were even, as growth in fairlife, Maaza and Minute Maid offset the Nigeria sale (earnings release). The company also gained value share in total nonalcoholic ready-to-drink beverages.
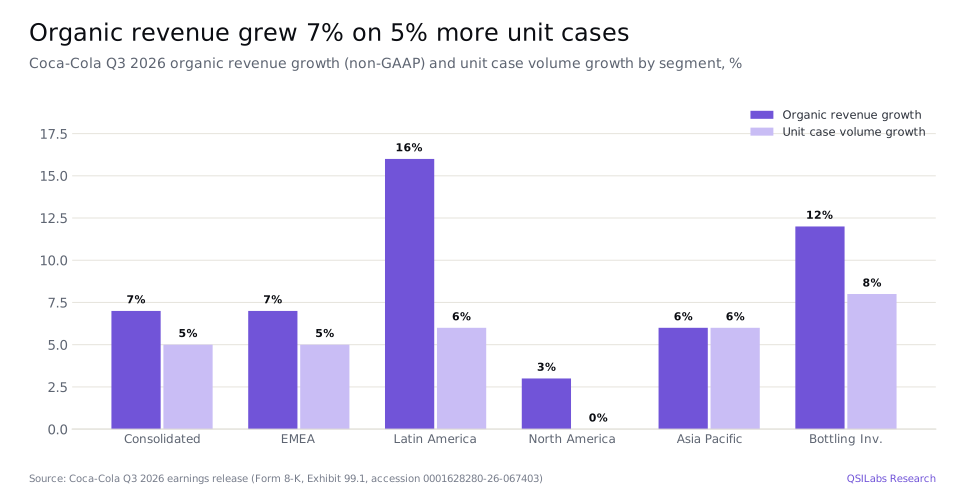
Unit case volume is measured at the consumer level, including drinks sold by independent bottlers, so it is the best single gauge of demand. Concentrate sales, which is what Coca-Cola actually invoices, ran 2 points ahead of volume in the quarter because of shipment timing; that gap tends to reverse, which is one reason to treat 7% organic growth as slightly flattering.
Did Coca-Cola raise its 2026 guidance?
Yes. On 27 October 2026 Coca-Cola raised its full-year 2026 guidance for organic revenue, earnings and free cash flow. The company now expects:
| 2026 guidance item | Before Q3 | After Q3 |
|---|---|---|
| Organic revenue growth (non-GAAP) | About 5% | At least 5% |
| Acquisitions and divestitures, revenue | 2-3% headwind | About 2% headwind |
| Underlying effective tax rate (non-GAAP) | 19.9% | 19.7% |
| Comparable currency-neutral EPS growth, excluding acquisitions and divestitures | 7-8% | At least 9% |
| Comparable EPS growth (non-GAAP) | 9-10% | At least 11% |
| Cash from operations | About $14.6bn | At least $15.2bn |
| Capital expenditures | About $2.2bn | About $2.2bn |
| Free cash flow (non-GAAP) | About $12.4bn | At least $13.0bn |
Source: Coca-Cola Q3 2026 earnings release. Comparable EPS growth includes about a 3% currency tailwind and about a 1% headwind from acquisitions and divestitures.
For the fourth quarter, the company expects about a 1% currency tailwind and about a 4% headwind from acquisitions and divestitures on comparable net revenues, and six fewer days than a year earlier. That is why analysts expect Q4 revenue of about $11.3bn, 4.4% below the $11.8bn of Q4 2025, even with underlying growth intact (S&P Global consensus via StockAnalysis). For 2027 the company flagged a slight currency headwind, an approximately 8% revenue headwind and about a 2% comparable EPS headwind from acquisitions and divestitures, and will give full guidance with Q4 results.
CEO Henrique Braun said the quarter showed "our system's sustained momentum, giving us confidence in our updated full year guidance."
What is the Coca-Cola Beverages Africa sale?
In October 2025 Coca-Cola agreed to sell part of its interest in its African bottling operations to Coca-Cola HBC AG, a bottler in which it already owns an equity stake. Closing is subject to regulatory approvals and is expected by the end of 2026, at which point Coca-Cola will deconsolidate the business. Coca-Cola HBC also has an option to buy Coca-Cola's remaining 25% within six years of closing (10-Q).
The business is held for sale, with $6,275m of assets and $3,003m of liabilities on the balance sheet at 2 October 2026. Coca-Cola wrote it down by $1,274m in 2025, mostly because of accumulated currency translation losses, and has since reversed $61m of that charge in 2026.
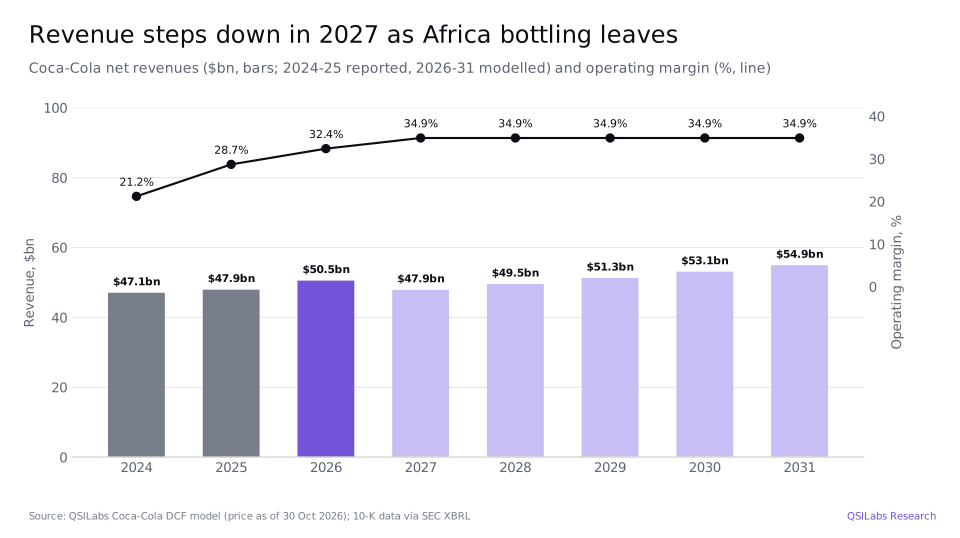
The financial effect is the classic refranchising trade. Bottling is capital-heavy and low-margin; concentrate is light and high-margin. Removing the African bottlers takes about 8% off 2027 revenue but, by the company's estimate, only about 2% off comparable EPS. Reported growth will look weak in 2027 while margins jump. We model exactly that: 2027 revenue falls 5.3% to $47.9bn, but operating income still rises 1.9% to $16.7bn and operating margin moves to 34.9% from 32.4%.
Coca-Cola cash flow, dividend and buybacks
Coca-Cola generated $12.5bn of operating cash flow in the first nine months of 2026 and spent $1.06bn on capital projects, leaving $11.4bn of free cash flow. A year earlier, operating cash flow was only $3.65bn because the company made the $6.1bn final milestone payment for fairlife in March 2025 (10-Q). Full-year guidance of at least $15.2bn of operating cash and $13.0bn of free cash flow implies at least $1.6bn of free cash flow in the fourth quarter.
Coca-Cola's dividend and share repurchases
The quarterly dividend is $0.53 a share, up from $0.51 in 2025, or $2.12 a year: a 2.3% yield at the 30 October close. The board approved the next payment in October, payable on 15 December 2026 to shareowners of record on 1 December. Dividends paid in the first nine months were $6.84bn against $4.39bn a year earlier; the nine months of 2026 included three quarterly payments against two in 2025.
Buybacks are modest. Coca-Cola repurchased 10.0m shares under its authorised plan in the first nine months at an average $78.77, for $787m, and total treasury purchases including shares surrendered by employees were $900m. The diluted share count was 4,314m in Q3, the same as a year earlier, and 4,301.9m shares were outstanding on 26 October 2026.
Balance sheet
At 2 October 2026 Coca-Cola held $13.7bn of cash, cash equivalents and short-term investments plus $2.9bn of marketable securities, against $41.6bn of debt, with no commercial paper outstanding. Net debt was about $25.0bn. The company repaid $3.2bn of debt in the nine months and issued almost none. Its equity-method stakes in bottlers and other companies were carried at $20.7bn.
What is the Coca-Cola IRS tax case?
The IRS case is the largest open risk on Coca-Cola's balance sheet. The US Tax Court ruled for the IRS on how much income Coca-Cola should report from its foreign licensees for 2007-2009, and the company paid $6.0bn of tax and interest in September 2024 while it appeals. The US Court of Appeals for the Eleventh Circuit heard the case on 25 June 2026; a decision was pending when the 10-Q was filed.
Coca-Cola still concludes it is more likely than not to win, and carries a $538m reserve. If it loses, it would not get back the $6.0bn deposit or the $589m of interest receivable, and it estimates the remaining tax and interest for 2010-2025 at about $14bn as of 31 December 2025, growing by about $1.4bn in the first nine months of 2026 (10-Q). We do not adjust our value for the case. As a rough scale, a full loss would cost about $3.6 a share on top of the deposit, while a win would return about $1.5 a share of cash.
Coca-Cola stock Q3 2026: is KO overvalued?
On our numbers, yes. We value Coca-Cola at $55.88 a share, against a $94.08 close on 30 October 2026: the price is 68% above our value. At $94.08 the company is worth about $405bn in the market, or roughly 27.5 times the $3.42 of 2026 EPS that analysts expect. Our value fell $2.41 after the 10-Q, from $58.29.
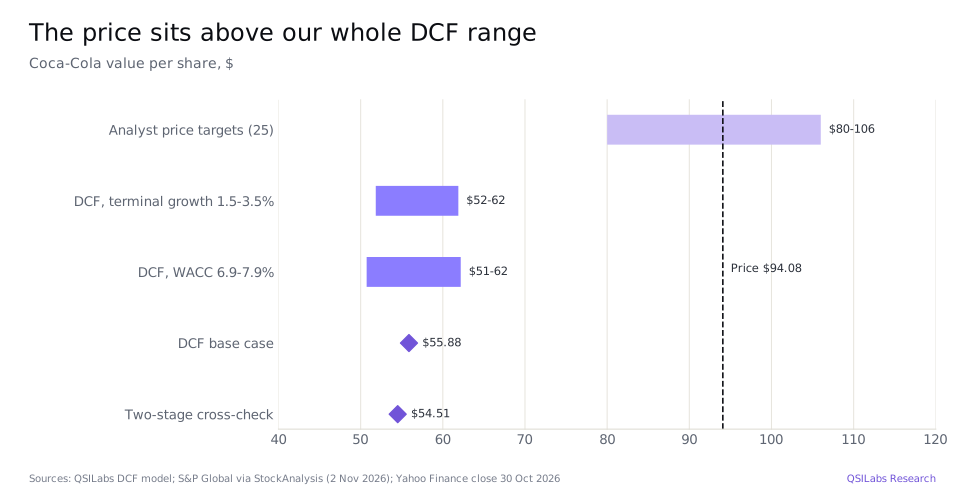
The gap is not about the quarter. Coca-Cola is a high-return business: it earns operating margins above 30% on concentrate it sells to bottlers that carry most of the capital. The question is what that is worth. Our model has the company's operating income growing from $16.4bn in 2026 to $22.0bn in 2035, about 3.3% a year, with revenue growth of 3.5% after the 2027 Africa step down. At a 7.4% cost of capital, that gives an enterprise value of $247bn. For the market price to be right with the same forecast, investors would need to accept a cost of capital of about 5.4%, or expect cash flow to grow by about 5.6% a year forever at our 7.4% rate.
Analysts are more positive. The 25 analysts in the S&P Global consensus rate KO a Buy with an average target of $97.75, a range of $80 to $106, and several raised targets after the quarter, for example from $98 to $106 and from $100 to $104 (StockAnalysis).
Method
We forecast Coca-Cola's revenue, operating margin, tax, capital spending and working capital for 2026 to 2035, discount the unlevered free cash flow at a 7.4% weighted average cost of capital, based on the soft-beverage industry data published by Aswath Damodaran, and add a terminal value with 2.5% growth. The terminal value is 64% of enterprise value. We then add cash and marketable securities of $16.6bn and equity stakes and other items of $21.3bn, mostly the $20.7bn carrying value of equity-method investments, and subtract $41.6bn of debt and $2.2bn of noncontrolling interests, giving equity value of $241.1bn, or $55.88 across 4,314m diluted shares. A two-stage cross-check gives $54.51.
The main forecast inputs are:
- 2026 revenue: $50.5bn, up 5.4%, with fourth-quarter revenue of $11.3bn, in line with consensus. Fourth-quarter operating margin is 25.5%.
- 2027 revenue: $47.9bn, down 5.3%: 3.5% underlying growth, less the 8% Africa headwind and a slight currency headwind.
- Growth after 2027: 3.5% a year through 2035, before the 2.5% terminal rate.
- Operating margin: 32.4% in 2026 and 34.9% from 2027, because the exited bottlers carry far lower margins than the rest of the group.
- Tax: 19.7%, the company's underlying rate for 2026.
- Capital spending: $2.2bn in 2026 and $2.1bn in 2027, rising from 4.4% of revenue to 6.7% by 2035 so that terminal growth is paid for by reinvestment.
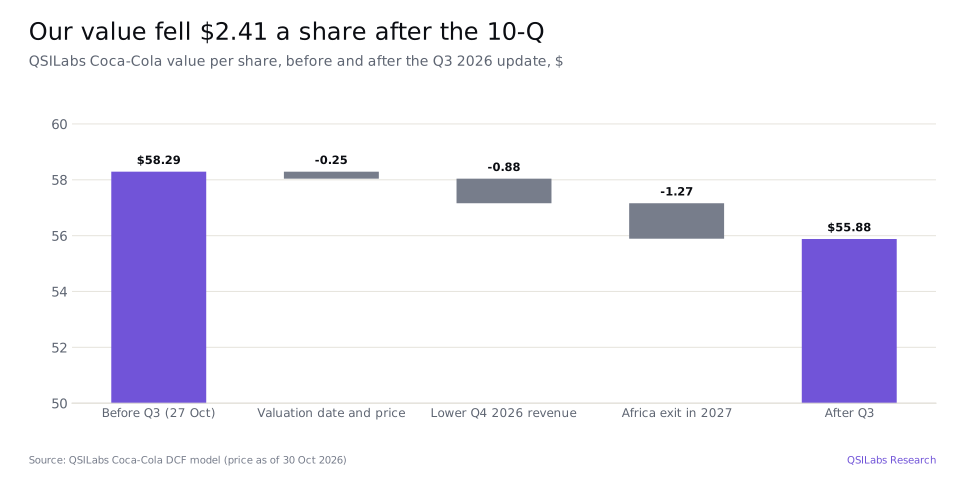
Most of the $2.41 fall comes from two forecast changes. Our earlier fourth-quarter estimate did not allow for the six fewer days, so we lowered Q4 2026 revenue to the $11.3bn consensus. And we now take out the Africa bottlers in 2027 in line with the company's guidance, lowering revenue while raising the margin: our 2027 revenue estimate is now 9.8% lower than before, but 2027 operating income only 3.9% lower.
How the number moves if you argue with us
| Value per share, $ | g = 1.5% | g = 2.0% | g = 2.5% | g = 3.0% | g = 3.5% |
|---|---|---|---|---|---|
| WACC 6.4% | 62.76 | 66.02 | 70.09 | 75.32 | 82.29 |
| WACC 6.9% | 56.79 | 59.22 | 62.18 | 65.87 | 70.61 |
| WACC 7.4% | 51.84 | 53.68 | 55.88 | 58.55 | 61.89 |
| WACC 7.9% | 47.67 | 49.08 | 50.73 | 52.71 | 55.12 |
| WACC 8.4% | 44.10 | 45.19 | 46.46 | 47.95 | 49.72 |
Source: QSILabs Coca-Cola DCF model. Even a 6.4% cost of capital with 3.5% growth forever gives $82.29, still below the share price. The price needs either a lower discount rate than any in this table or faster growth, forever, than the 3.7% a year by which Coca-Cola's revenue grew from 2022 to 2025.
Risks to the Coca-Cola investment case
The risks cut both ways. On the upside for the shares:
- A lower cost of capital. Coca-Cola is among the most stable large businesses in the world, and many investors treat it as a bond substitute. If they keep accepting a 5-6% return, the price can stay above our value.
- Faster growth. Organic growth of at least 5% in 2026 is above the 3.5% we assume from 2028. If emerging markets keep growing volume at mid-single digits, our forecast is too low.
- Winning the tax case would return about $6.6bn of cash.
On the downside:
- The IRS case. A loss would cost the $6.6bn deposit and interest plus an estimated $15bn or more of further tax and interest, and would raise the tax rate on future earnings.
- North America volume was even in Q3, with water, sports, coffee and tea down 4%. The largest segment is not growing volume.
- Currency. Latin America's 25% revenue growth included 9 points of currency, and the company expects a slight currency headwind in 2027.
- Refranchising execution. The Africa sale still needs regulatory approvals, and the 2027 numbers depend on it closing as planned.
FAQ
What is QSILabs' value for Coca-Cola stock after Q3 2026 earnings?
QSILabs values The Coca-Cola Company (KO) at $55.88 per share as of Q3 2026 results, based on a discounted cash flow model with a 7.4% cost of capital and 2.5% terminal growth. The shares closed at $94.08 on 30 October 2026, about 68% above that value. Our sensitivity range is roughly $51-62 a share.
Is Coca-Cola stock a buy after Q3 2026?
On our valuation, Coca-Cola stock is expensive: the $94.08 price sits above our whole DCF range of about $51-62. The 25 analysts in the S&P Global consensus disagree, rating KO a Buy with an average target of $97.75. This is analysis, not investment advice.
How much did Coca-Cola earn in Q3 2026?
Coca-Cola earned $4.01bn, or $0.93 a share, in Q3 2026, the quarter ended 2 October 2026, up from $3.70bn, or $0.86, a year earlier. Comparable EPS was $0.91, up 11%. Net operating revenues were $13.38bn, up 7%.
Why did Coca-Cola's revenue grow in Q3 2026?
Revenue grew 7% because concentrate sales rose 7% and price/mix added 1%, with a 1-point currency tailwind offset by a 1-point divestiture headwind. Unit case volume grew 5%, led by India, China, Mexico and Brazil, and Coca-Cola Zero Sugar volume rose 16%.
What is Coca-Cola's 2026 guidance?
Coca-Cola expects 2026 organic revenue growth of at least 5%, comparable EPS growth of at least 11%, comparable currency-neutral EPS growth excluding acquisitions and divestitures of at least 9%, and free cash flow of at least $13.0bn. It raised all of these on 27 October 2026.
What is Coca-Cola's dividend?
Coca-Cola pays a quarterly dividend of $0.53 a share, or $2.12 a year, a yield of about 2.3% at the 30 October 2026 price of $94.08. The next payment is on 15 December 2026 to shareowners of record on 1 December.
How will the Africa bottling sale affect Coca-Cola?
The sale of part of Coca-Cola Beverages Africa to Coca-Cola HBC, expected to close by the end of 2026, will reduce 2027 revenue by about 8% but comparable EPS by only about 2%, according to the company. Revenue falls, but operating margin rises because bottling is a low-margin business.
What is the Coca-Cola IRS tax case?
Coca-Cola is appealing a US Tax Court ruling on transfer pricing with its foreign licensees. It paid $6.0bn in 2024 for 2007-2009 and estimates a further $14bn of potential tax and interest for 2010-2025 if it loses. The Eleventh Circuit heard the appeal on 25 June 2026; the company believes it is more likely than not to win.
Sources
- The Coca-Cola Company, Form 10-Q for the quarter ended 2 Oct 2026 (filed 28 Oct 2026; accession 0001628280-26-067844) www.sec.gov
- The Coca-Cola Company, Q3 2026 earnings release (Form 8-K, Exhibit 99.1, 27 Oct 2026; accession 0001628280-26-067403) www.sec.gov
- SEC EDGAR XBRL company facts for The Coca-Cola Company (CIK 21344): 10-K revenue and operating income, 2024-2025 data.sec.gov
- StockAnalysis: Coca-Cola forecast and analyst ratings, S&P Global data (accessed 2 Nov 2026) stockanalysis.com
- StockAnalysis: Coca-Cola statistics (accessed 2 Nov 2026) stockanalysis.com
- Yahoo Finance chart data: KO closing prices (November 2025 to November 2026) query1.finance.yahoo.com
- Damodaran Online: cost of capital by industry (Beverage, soft) pages.stern.nyu.edu
- QSILabs Coca-Cola discounted cash flow model (internal; price as of 30 Oct 2026)
Disclaimer
This article is for information only and is not investment advice or a recommendation to buy or sell any security. QSILabs estimates are opinions based on public information and our own model, and they may be wrong. Figures are as of the dates stated. Do your own research or consult a licensed adviser before investing.
More from QSI Labs
Related analysis: Johnson & Johnson stock Q3 2026: talc and Tremfya, Visa stock Q3 2026, Chevron stock Q3 2026 and AbbVie stock Q3 2026.
Read our white paper, QSI Labs: An AI-Native Trading Firm Built on a Training Loop (October 2026), available on request, or browse the research index.